

Intel (INTC) just got a reality check from Wall Street.
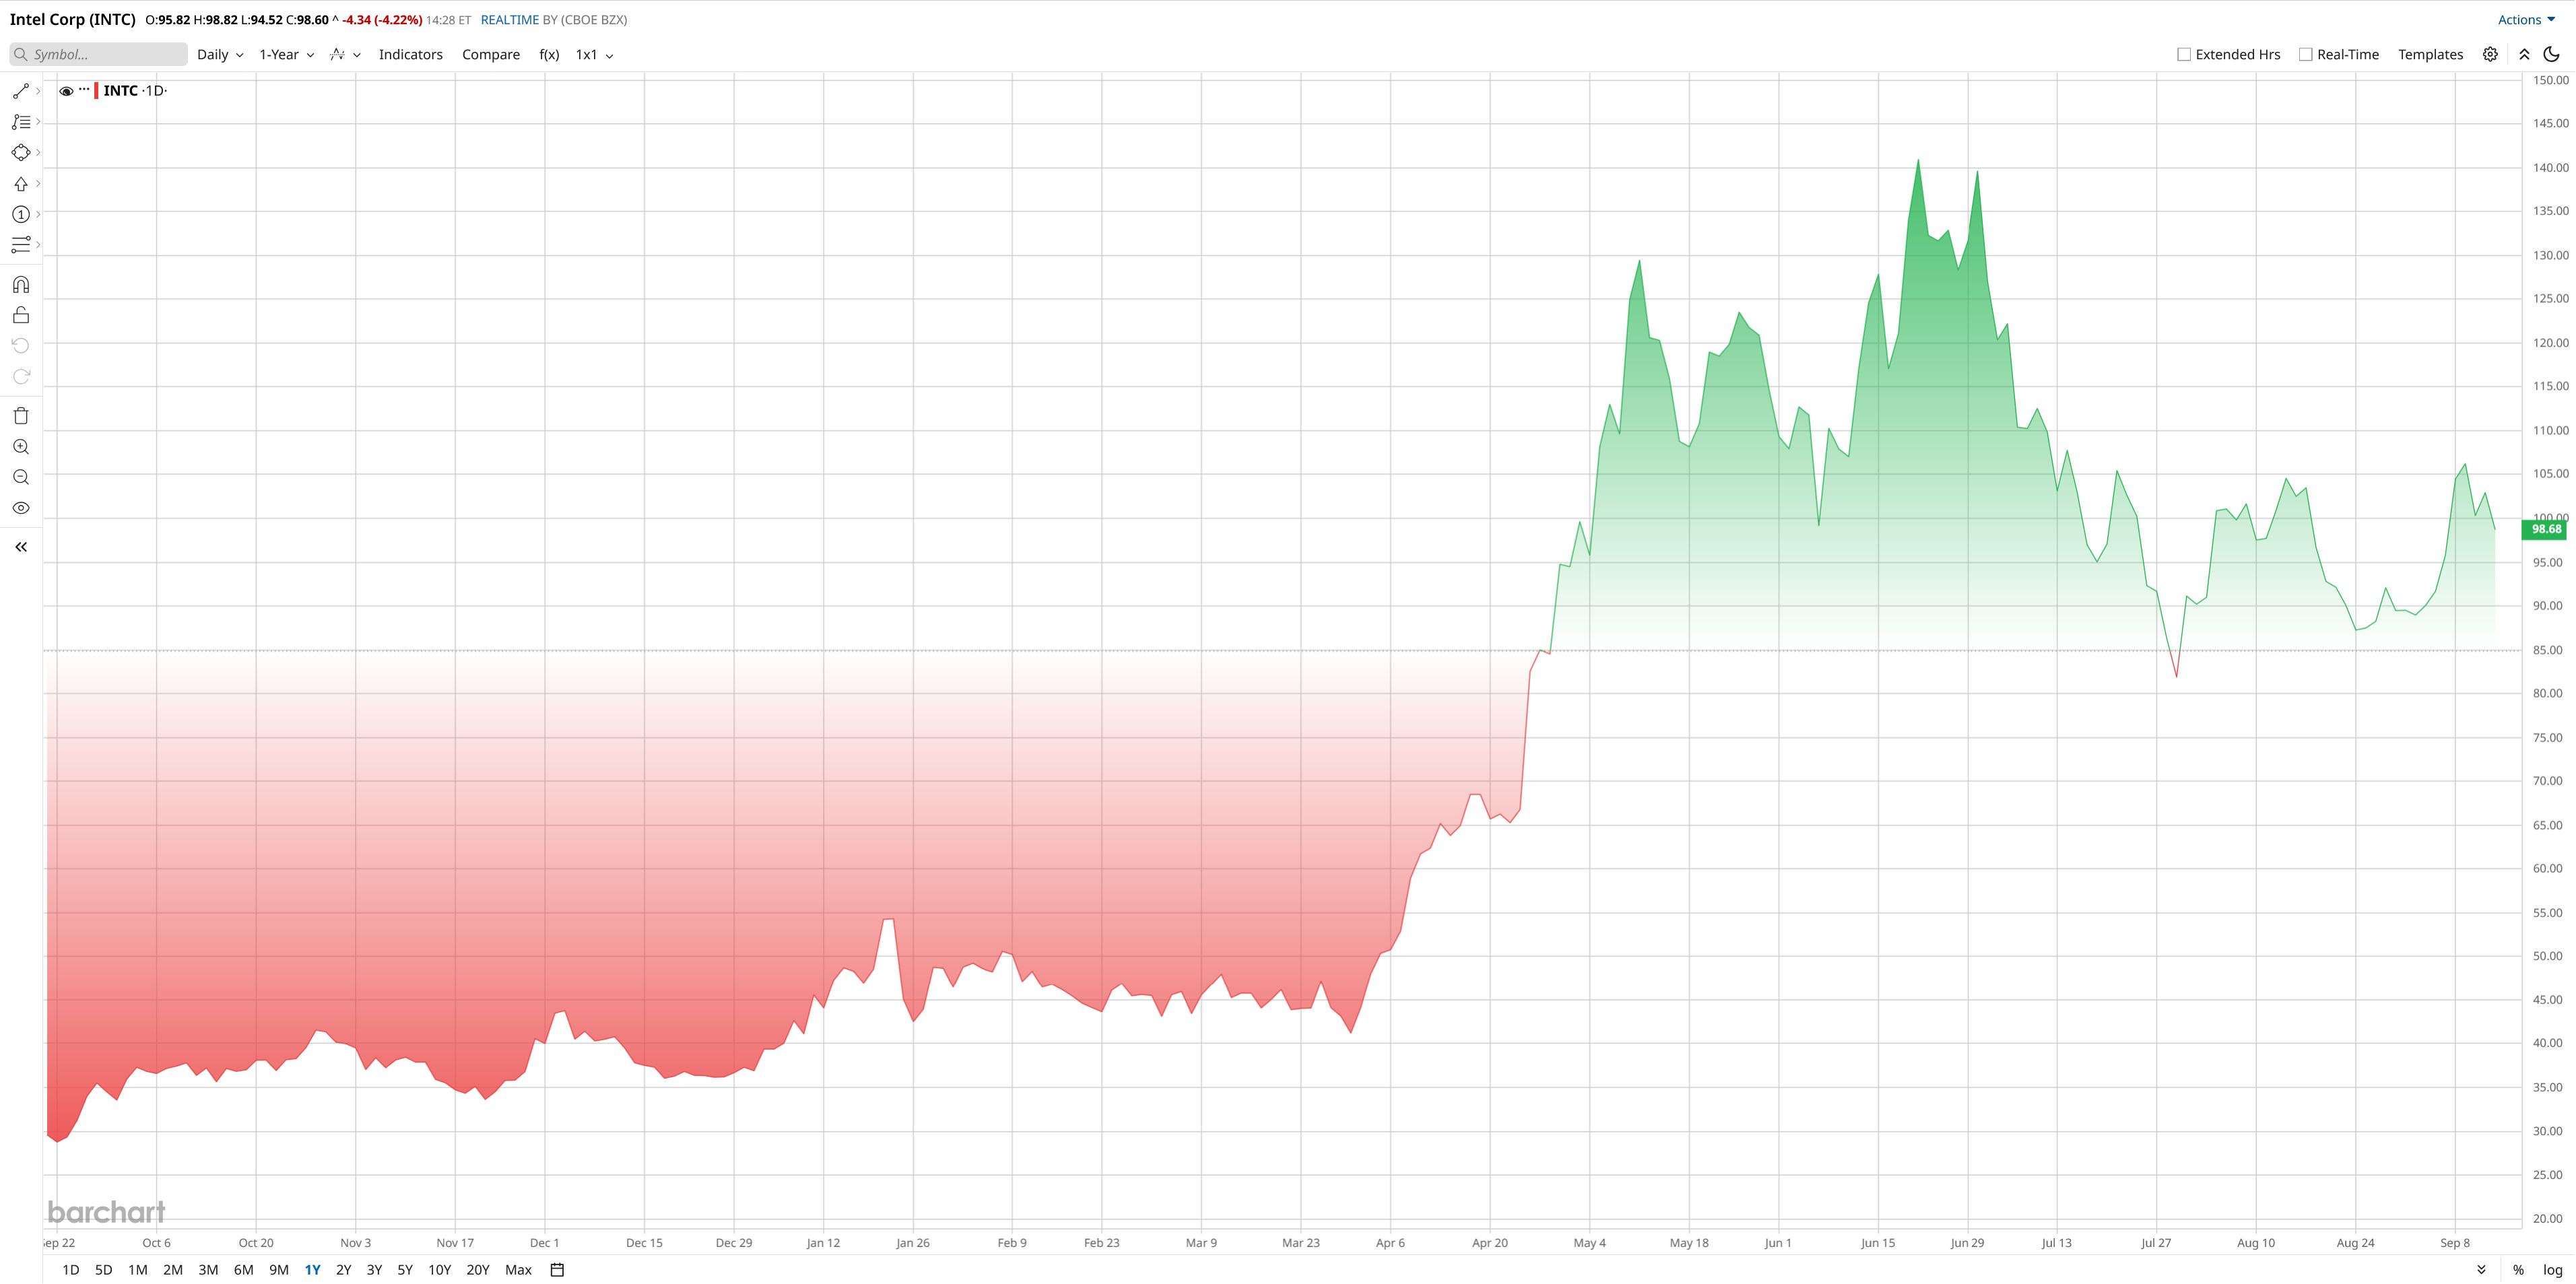
Shares of Intel fell as much as 6% on Thursday and are falling again today, as investors are taking profits following the stock’s huge recent rally. The move came after Piper Sandler initiated coverage with a “Neutral” rating and a $110 price target, putting fresh attention on whether Intel’s AI-driven comeback is already fully reflected in the stock price.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
The timing is important. Intel shares had jumped roughly 9% in the previous session and remained up more than 167% in 2026. That kind of run creates a much higher bar for future gains. Investors now need to see continued earnings growth, stronger manufacturing execution, and more evidence that Intel can turn AI demand into sustainable profits.
Intel’s turnaround has been one of the biggest semiconductor stories of 2026, but the stock is no longer trading like a beaten-down turnaround play.
 www.barchart.com
What Piper Sandler’s $110 Target Means
Piper Sandler’s “Neutral” rating does not mean the firm expects Intel’s turnaround to fail.
Instead, the message is that much of the optimism may already be priced into INTC stock. Analyst David O’Connor sees Intel benefiting from the rapid adoption of agentic AI, which is driving demand for server CPUs. Piper Sandler expects supply to remain constrained for these products for years, potentially creating a strong runway for Intel’s Data Center business.
But that bullish operating backdrop is being weighed against valuation.
Intel also needs to prove that its foundry ambitions can translate into meaningful long-term customer wins. Piper Sandler specifically highlighted Intel’s progress with advanced manufacturing and customer interest around its next-generation 14A process. The issue is that investors are already pricing in substantial improvement.
In other words, the $110 target suggests some upside from recent levels, but not enough to justify chasing the stock after such a massive rally.
Q2 Numbers Show Why Bulls Are Excited
The latest quarter explains why investors became so optimistic in the first place.
Intel reported second-quarter revenue of $16.1 billion, up 25% year-over-year (YoY). Non-GAAP earnings came in at 42 cents per share, while non-GAAP gross margin expanded to 41.8% from 29.7% a year earlier. Data Center and AI revenue jumped 59% to $6.3 billion, while Intel Foundry revenue increased 31% to $5.8 billion.
The company also guided for third-quarter revenue between $15.8 billion and $16.8 billion, with adjusted EPS of 38 cents. Those numbers indicate the recovery is gaining traction rather than simply benefiting from easier comparisons.
Still, there are weak spots. Intel posted an $11 billion net loss in the quarter, and its transformation requires enormous investment in manufacturing capacity and equipment. The company raised its 2026 capital spending outlook to more than $20 billion as it prepares for higher demand across products and foundry operations.
Intel Is Betting Beyond Traditional CPUs
Intel is also trying to build a much broader AI business.
The company recently launched its next-generation Xeon 6+ server processor, its first server-class product built on Intel 18A. It is also expanding into rack-scale AI infrastructure, advanced packaging, physical AI, and robotics, with more than 130 customers adopting or testing its latest Core Ultra processors for edge AI applications.
At the same time, Intel is pouring money into manufacturing and foundry capacity. In August, the company announced a $15 billion common-stock offering, with proceeds intended for capital expenditures and working capital. The offering was later upsized to $20 billion, highlighting how aggressively Intel is funding its next phase of expansion.
Wall Street Is Split on INTC Stock
Piper Sandler is not alone in urging caution, but Wall Street remains far from united.
Northland upgraded INTC stock to “Outperform” and assigned a $120 target, reflecting confidence in the company’s foundry opportunity. Mizuho, meanwhile, maintained a “Neutral” rating while cutting its target from $109 to $92, pointing to valuation and execution concerns. UBS also moved its view higher more recently, while other analysts remain cautious about how much of Intel’s AI recovery is already reflected in the share price.
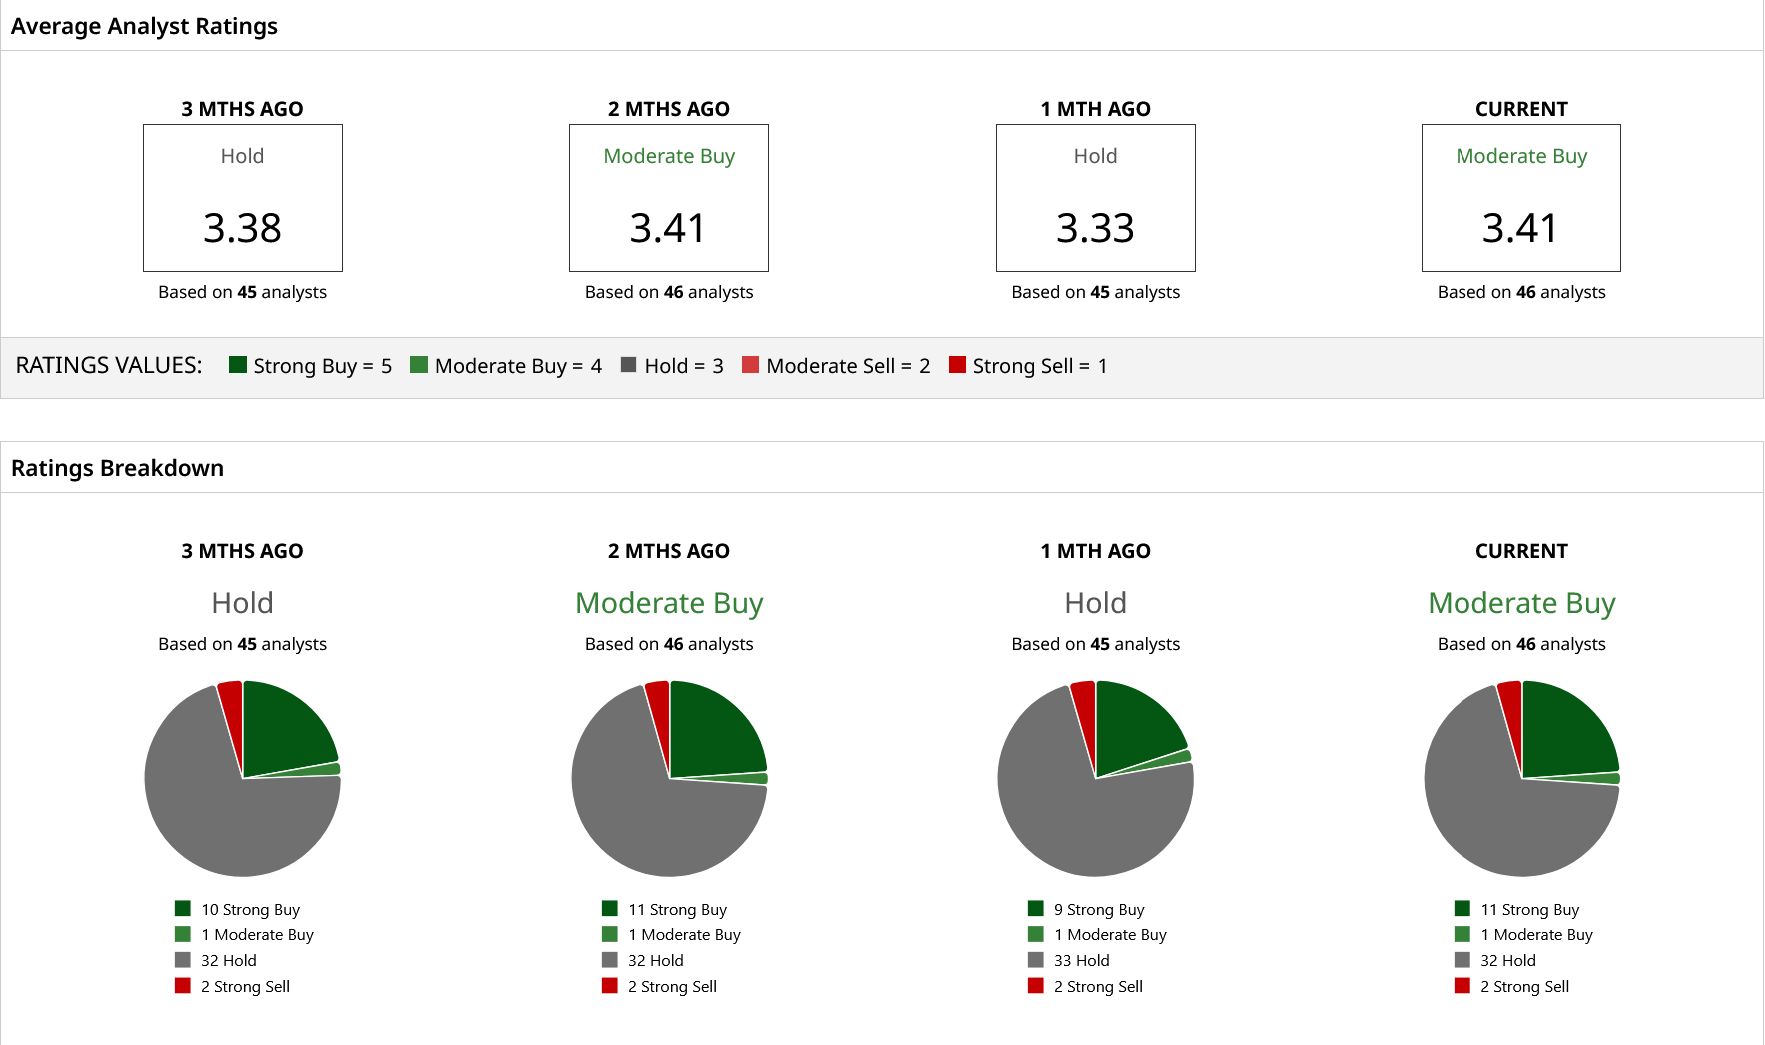
Overall, it's an improvement from consensus “Hold” to "Moderate Buy" in the past month; still, INTC's mean price target of $113.90 implies upside room of 15% from here.
That leaves investors with a complicated setup. Intel’s business is improving, AI demand is creating new opportunities, and its manufacturing strategy is gaining credibility. But after such a massive stock rally, the company has less room for mistakes.
Piper Sandler’s $110 target is ultimately a warning that Intel may have become a better company faster than it has become a better bargain.
 www.barchart.com
On the date of publication, Nauman Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Intel Stock Just Got a Stark Warning From Wall Street Billionaire Michael Saylor Says You Now Have to Put Typos in Your Messages to Prove a Human Wrote Them: ‘If You Put Errors In It, I Believe You Typed It’ Dell Stock Is Up 331% Over the Past Year and Still Could Run Higher Unusually High Volume in Deep Out-of-the-Money Vertiv Call Options Shows Investors Bullish on VRT