

New York-based Take-Two Interactive Software, Inc. (TTWO) is a major global video-game publisher and developer behind some of the industry's biggest franchises, including Grand Theft Auto, Red Dead Redemption, NBA 2K, Borderlands, Civilization, WWE 2K, and Zynga’s mobile games. Its business spans console, PC, and mobile gaming through three key labels: Rockstar Games, 2K, and Zynga.
Companies with a market cap between $10 billion and $200 billion are typically referred to as “large-cap stocks, and TTWO, with a market cap of $41.7 billion, fits the label. The company’s biggest competitive advantage is its deep portfolio of highly recognizable intellectual property. Rockstar’s Grand Theft Auto franchise alone has sold more than 470 million units, while GTA V has surpassed 230 million units sold worldwide. Moreover, Grand Theft Auto VI is scheduled for Nov. 19, 2026, alongside new installments of NBA 2K, WWE 2K, PGA TOUR 2K and other franchises.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
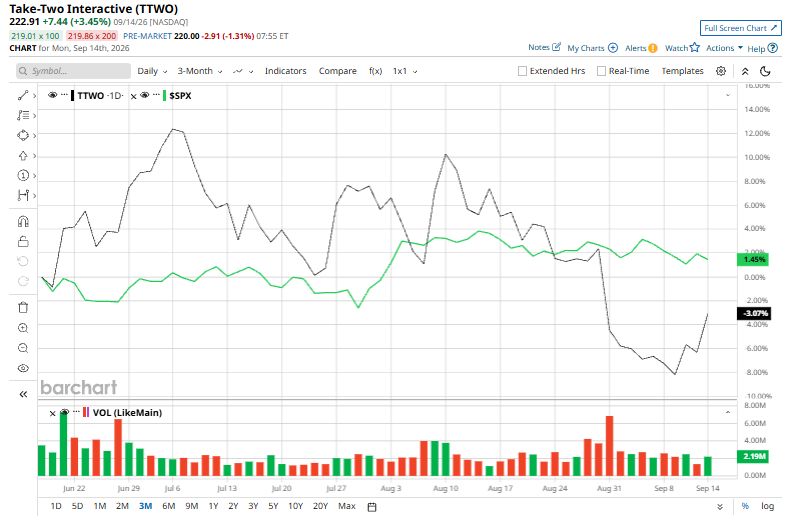
However, Take-Two’s stock has hit a rough patch despite its blockbuster gaming portfolio. After touching a 52-week high of $265.94 on July 7, TTWO has since retreated 16.2%. The weakness has also persisted recently, with shares declining 5.3% over the past three months, trailing the S&P 500 Index ($SPX), which has rallied 2.5%.
 www.barchart.com
Zooming out, the gap becomes harder to ignore. TTWO has fallen 9.5% over the past 52 weeks, while the S&P 500 has gained 15.7%. In 2026, the stock is down 12.9%, compared with an 11.3% gain for the index.
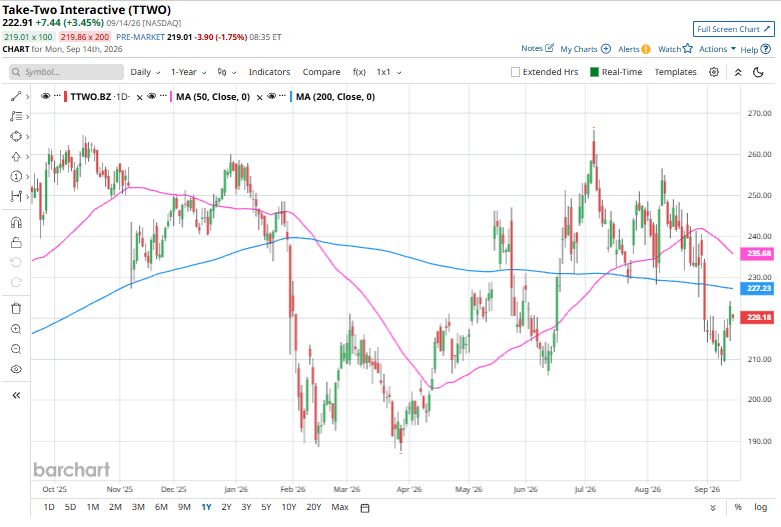
The technical picture isn’t helping either. TTWO has traded below both its 50-day and 200-day moving averages since last month, pointing to increasingly bearish momentum.
 www.barchart.com
TTWO’s blockbuster franchises haven’t been enough to keep the stock ahead of the broader market over the past year. Investors remain wary of its near-term growth trajectory, with revenue rising just 7.1% annually over the past three years and sales projected to decline 14.6% over the next 12 months. The company’s hit-driven model and elevated game-development costs add to the uncertainty, while weak free cash flow leaves less room to reinvest, repurchase shares, and return capital to investors. With expectations for GTA VI already sky-high, Take-Two is under pressure to deliver.
TTWO’s recent underperformance looks even more pronounced against Electronic Arts Inc. (EA), with EA shares surging 31.3% over the past year and gaining 2.6% in 2026, leaving Take-Two playing catch-up.
Still, Wall Street sees plenty of upside ahead. The 29 analysts covering TTWO have a consensus “Strong Buy” rating, and the average price target of $290.40 implies 30.3% upside from current levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.