

Hewlett Packard Enterprise Company (HPE) is becoming a major beneficiary of the enterprise artificial intelligence (AI) infrastructure growth. While many companies are working on AI applications, Hewlett Packard primarily focuses on infrastructure, supplying servers, networking, and other technology essential for large-scale AI deployment.
The company’s latest quarterly results showed rising demand, with both revenue and profit exceeding analyst expectations and robust growth across all segments. Its integration of Juniper Networks has further strengthened the company’s position in AI networking, giving the company greater access to the infrastructure needs driven by AI's rapid growth.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
In fact, HPE stock jumped 12.4% on Friday, Sept. 11, after Oracle (ORCL) announced during its recent earnings call that it intends to sustain large investments in AI. As part of this strategy, Oracle aims to expand its worldwide AI infrastructure by implementing Hewlett Packard’s routing and switching platforms in all its data centers.
For Hewlett Packard, Oracle’s plans are particularly significant given the sheer scale of its AI spending. Oracle’s remaining performance obligations (RPO) grew $209 billion during Q1 FY2027 to $664 billion, including more than $30 billion in additional AI cloud contracts.
More broadly, the rise of agentic AI could further increase the need for this kind of infrastructure as enterprises move toward AI systems that can handle increasingly complex workloads. That creates a potentially powerful growth opportunity for Hewlett Packard.
About Hewlett Packard Stock
Headquartered in Spring, Texas, Hewlett Packard is a global technology company serving businesses and public-sector organizations with IT infrastructure and digital solutions. Its portfolio spans enterprise servers, data storage, hybrid cloud platforms, networking and cybersecurity technologies, and flexible IT financing.
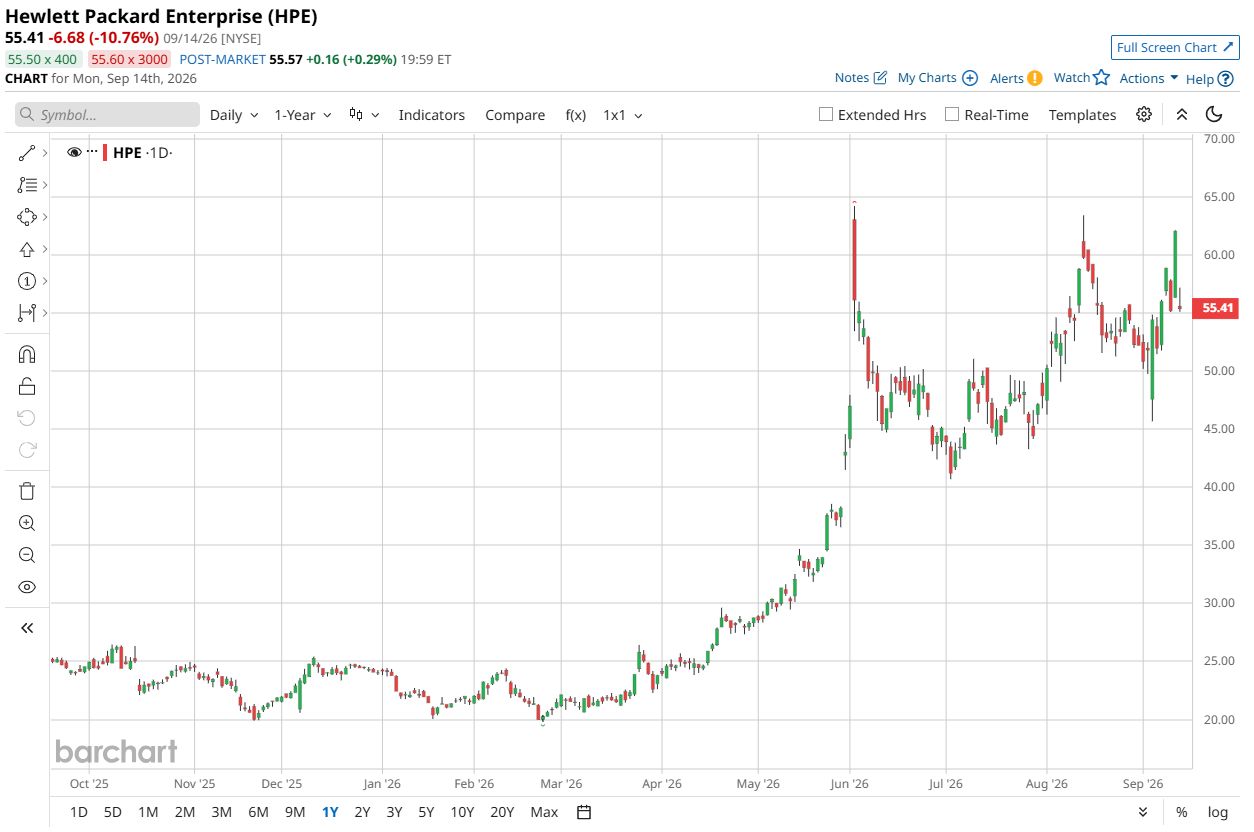
With a market cap of nearly $82.4 billion, HPE stock has delivered a striking run for shareholders. Its shares have gained 124.1% over the last 52 weeks and are up 130.7% in 2026. Even over the past three months, the stock has jumped 15%.
 www.barchart.com
Despite those gains, HPE stock does not appear particularly expensive relative to its industry. The stock is currently trading at 16.24 times forward adjusted earnings and 1.78 times sales. Both multiples sit well below their respective industry averages, suggesting a valuation discount that could offer an attractive entry point for long-term investors.
Furthermore, Hewlett Packard currently pays an annual dividend of $0.57 per share, representing a 0.92% yield. The company is scheduled to pay its most recent dividend of $0.14 per share on Friday, Oct. 16, to shareholders of record as of Thursday, Sept. 17.
Hewlett Packard Surpasses Q3 Earnings
On Sept. 2, Hewlett Packard reported its Q3 FY2026 earnings results, beating Wall Street expectations. Total revenue increased 33.7% year-over-year (YOY) to $12.21 billion, exceeding Street expectations of $11.99 billion.
The composition of that growth is particularly noteworthy. Cloud & AI revenue rose 25.4% YOY to $9 billion, led by server revenue, which increased 35.3%. Networking was the standout performer, with reported revenue up 74.9% from the year-ago period to $2.9 billion.
The order trends were arguably even more encouraging. Networking orders grew 36%, substantially faster than revenue, while networks for AI orders hit a record $700 million during the quarter. Cumulative networks for AI orders reached $2.2 billion, leading Hewlett Packard to raise its fiscal-year target to $2.5 billion-$3 billion.
The backlog metrics reinforce demand strength. Hewlett Packard’s total AI systems backlog stood at $7.6 billion at quarter-end, while AI systems orders reached $2.4 billion, up more than 30% sequentially. AI systems backlog also increased 14% sequentially.
The improvement was not confined to the top line. Non-GAAP net income grew 155.2% from the previous year’s quarter to $1.6 billion, while adjusted EPS grew 152.3% from the year-ago value to $1.11, ahead of analyst estimates of $0.94. Moreover, free cash flow came in at $958 million.
With both demand and profitability moving in the right direction, Hewlett Packard has become more confident about the road ahead. For full-year FY2026, the company is targeting revenue growth of 34% to 37%, with the networking segment alone expected to accelerate further by 73% to 74%. The company also raised its non-GAAP diluted net EPS outlook to a range of $3.75 to $3.85.
Plus, Hewlett Packard is looking beyond the current fiscal year. It has raised its growth framework for FY2027, lifting its revenue growth outlook range to 13% to 17%. It is also raising expectations for non-GAAP diluted net EPS growth to a range of 16% to 20%. For Q4 FY2026 alone, the tech pioneer is targeting revenues of $13.9 billion to $14.8 billion, while non-GAAP EPS is projected at $1.20 to $1.30.
On the other hand, analysts expect Q4 FY2026 EPS to grow 116.7% YOY to $1.17. For full FY2026, they forecast bottom-line growth of 116.9% from the previous year to $3.34, while their FY2027 estimates call for 27% growth from last year to $4.24.
What Do Analysts Expect for Hewlett Packard Stock?
Evercore ISI's Amit Daryanani now considers Hewlett Packard to be only “In-Line,” down a peg from his previous recommendation of “Outperform.” Despite the rating change, Daryanani maintained his $65 price target.
The more cautious view stands in contrast to several other analysts who remain upbeat following Hewlett Packard’s latest earnings report. Citi analyst Asiya Merchant maintains a “Buy” rating with a $76 price target, citing strong demand. Goldman Sachs analyst Katherine Murphy also maintains a “Buy” rating on HPE stock with a $75 price target, following the Q3 earnings beat.
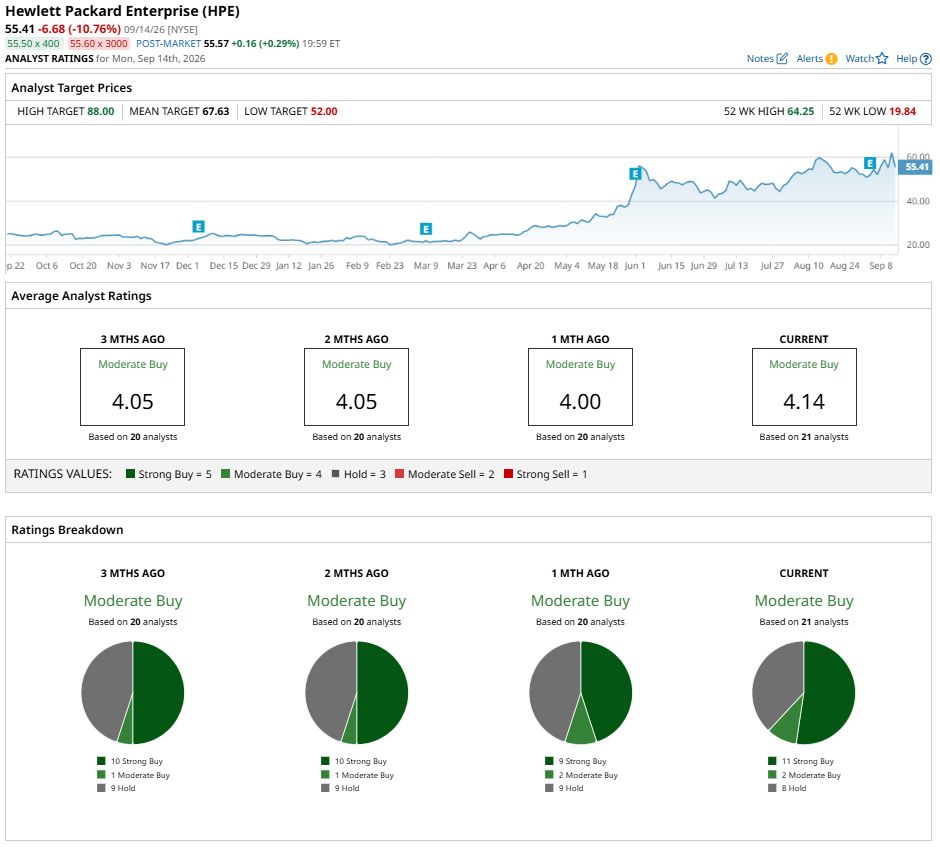
Raymond James analyst Simon Leopold is even more bullish. He reiterated an “Outperform” rating on HPE stock while raising his price target to $86 from $74. The broader Wall Street picture therefore remains firmly positive. Hewlett Packard currently carries a “Moderate Buy” rating. Of the 21 analysts covering its stock, 11 recommend “Strong Buy,” two recommend “Moderate Buy,” and eight suggest “Hold.”
That consensus is notable given how strongly HPE stock has already performed. The stock’s average price target of $67.63 represents potential upside of 22.1%. Meanwhile, the Street-High target of $88 suggests a gain of 58.8% from current levels.
 www.barchart.com
On the date of publication, Aanchal Sugandh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Dear Future Holtec Nuclear Stock Investors, Mark Your Calendars for September 18 Market Weakness Is Growing: Time to Look at Bear Call Spreads? How Agentic AI Could Drive HPE Stock Much Higher S&P Futures Gain as Oil Retreats, Fed Rate Decision in Focus