

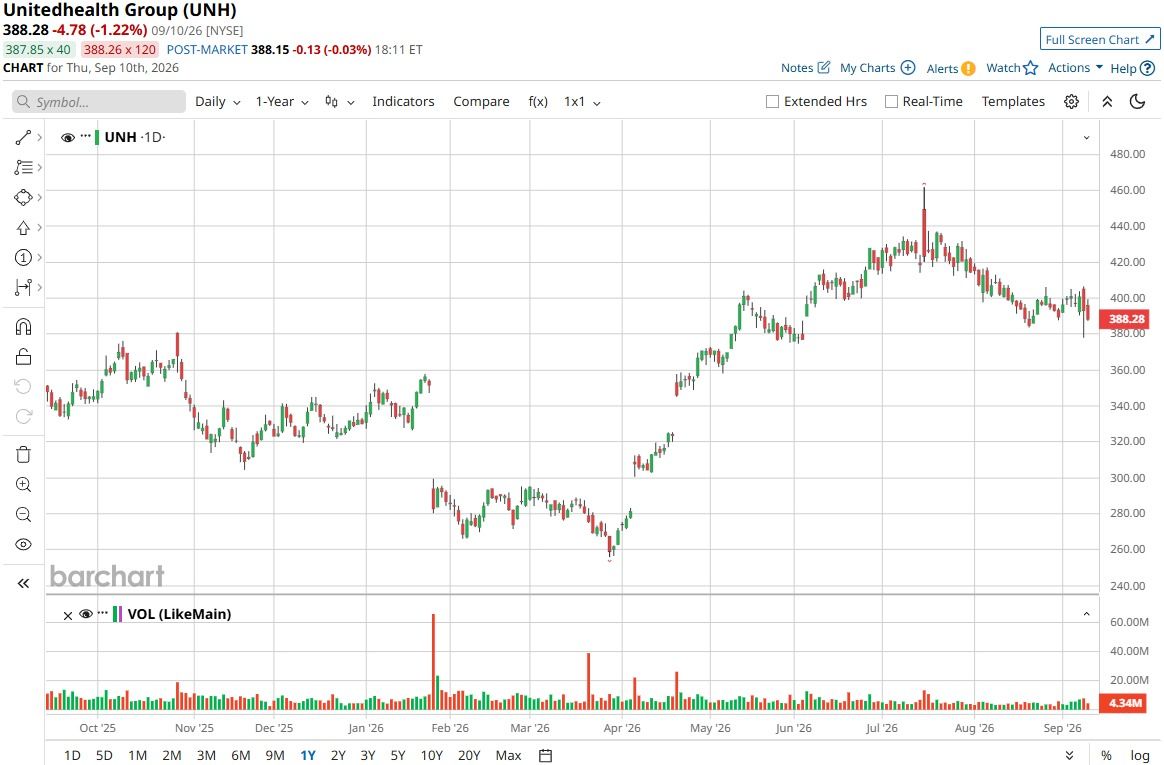
For much of 2025, UnitedHealth Group (UNH) looked like a company under siege as higher medical costs and weaker margins rattled investors. UNH stock sold off sharply, and questions emerged around the company’s earnings outlook as well as the health of its long-standing growth story.
That picture is starting to improve in 2026. UnitedHealth's latest results showed a clear turnaround in profitability as it generated $112 billion in revenue and $8 billion in earnings from operations. Management also raised the company's full-year adjusted EPS outlook to a range of $19.50 to $20 and increased its operating cash flow forecast to about $24 billion. Those moves suggest UnitedHealth sees its recovery as more than a short-term earnings rebound.
More Yield, Less Trap: Sign up free to get Barchart’s daily Dividend Investor newsletter straight to your inbox.
This improving earnings and cash flow profile carries particular weight for dividend investors, as UnitedHealth now pays an annualized dividend of $9.28 per share, offering a yield above 2.4%. With shares rebounding from their 2025 lows, can UnitedHealth’s improving margins and cash generation support both continued dividend growth and further upside? Let’s take a closer look.
UnitedHealth’s Improving Profitability
Based in Eden Prairie, Minnesota, UnitedHealth Group operates UnitedHealthcare, its health-benefits arm, and Optum, which provides pharmacy benefits, care delivery, data, and technology services. With a market capitalization of $337 billion, the company serves consumers, employers, governments, care providers, and health plans across its insurance and services platforms.
On Sept. 15, UNH stock closed the session at $375.93 per share. The stock has gained 15% year-to-date (YTD) and more than 11% over the past 52 weeks.
 www.barchart.com
UNH stock has a PEG ratio of 1.4 times, which is below the sector median of about 1.8 times. Meanwhile, the price-to-cash flow (P/CF) multiple of about 18 times is above the sector median of around 15 times.
UnitedHealth currently pays a forward annual dividend of $9.28 per share, which equates to a 2.4% yield. Investors who owned UNH stock as of the Sept. 14 record date will receive a $2.32 quarterly payment on Sept. 22.
That payout is backed by improving earnings momentum. On July 16, the company reported second-quarter 2026 results that included $112 billion in revenue. The figure came in slightly ahead of the $110.6 billion consensus estimate and was flat with the prior year. Meanwhile, adjusted EPS of $6.38 beat the $4.88 consensus estimate.
UnitedHealth's medical care ratio was 86.7% for Q2, helped by product changes, improved medical management, and better-aligned pricing. This measure included $860 million of favorable prior-period development, mainly tied to 2026 service dates.
UnitedHealthcare served 48.5 million consumers, generating $86 billion in revenue and $3.9 billion in earnings. Optum supported more than 120 million consumers, generated $65.7 billion in revenue, and delivered $4 billion in earnings in Q2.
Operating margin expanded to 7.1% from 4.6% a year earlier, reflecting a meaningful improvement in profitability. That progress supported $8 billion of earnings from operations and a 4.9% net margin.
Cash flow from operations was $11.1 billion, equal to 1.9 times net income, providing substantial coverage for the dividend. The debt-to-capital ratio was 41.2% as of June 30, 2026. Margin expanded 160 basis points year-over-year (YOY), adding support to UNH’s broader turnaround thesis.
What Is Supporting UnitedHealth’s Recovery?
UnitedHealth Group is pairing its operational recovery with a larger commitment to shareholders. Management now expects to repurchase at least $5 billion of common stock in 2026, raising its original buyback target. The firm had already repurchased $4 billion of shares through mid-July.
The company is also directing resources toward programs that could improve affordability, access, and member engagement over time. UnitedHealth’s partnership with University of Tennessee Health Sciences will expand health hubs into more Tennessee communities. The initiative connects residents with local support and resources that address health-related social needs.
In July, UnitedHealthcare also introduced a new spending account benefit that gives eligible consumers greater flexibility in using health plan funds. The offering expands choices for qualified healthcare and everyday wellness expenses.
In addition, UnitedHealthcare expanded child and family behavioral coaching access to 13 million commercial members. The program provides families with support for behavioral and emotional challenges beyond conventional insurance coverage.
Together, these initiatives show how UnitedHealth is approaching its recovery on two fronts. The buybacks return excess capital to shareholders, while care access and engagement programs could help the company manage costs and strengthen member relationships over time.
Wall Street Expects the Recovery to Continue
UnitedHealth Group is due to report its Q3 2026 results on Oct. 27. Analysts expect EPS of $4.03, up 38% YOY from earnings of $2.92 per share.
On July 22, Bernstein kept a “Buy” rating on UNH stock and assigned a $512 price target, pointing to 35% potential upside from current levels. Around the same time, UBS reiterated its “Buy” rating and lifted its target to $490 from $460, citing a stronger-than-expected Q2 performance and improving Medicare Advantage trends.
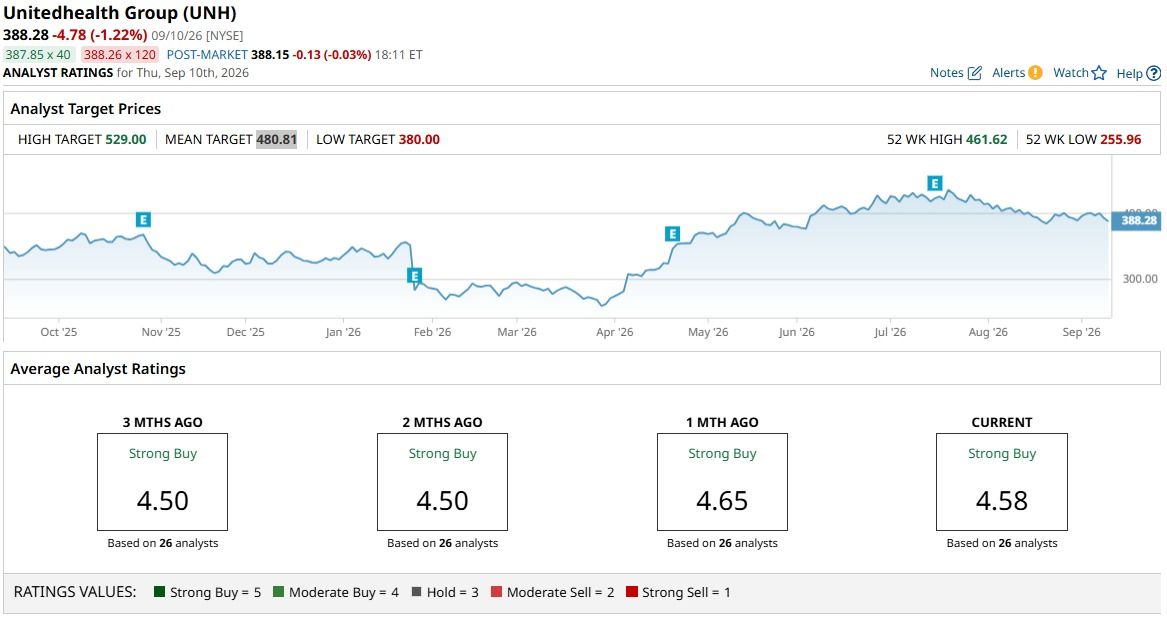
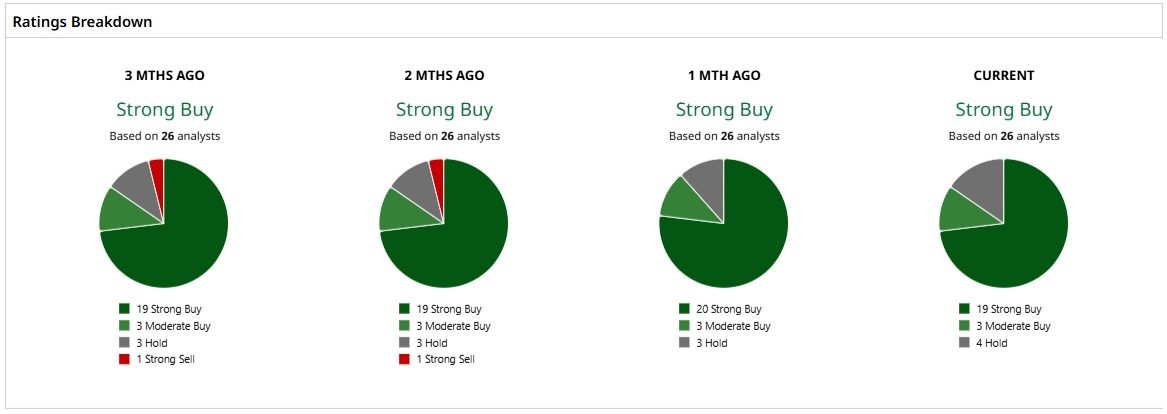
The broader Wall Street view remains constructive. UNH stock has a consensus “Strong Buy” rating among 26 analysts with coverage. The average price target of $480.81 points to potential upside of 27% from current levels.
 www.barchart.com
 www.barchart.com
Conclusion
UnitedHealth’s 2026 turnaround looks increasingly credible. Improving margins, stronger cash flow, a larger buyback plan, and a $9.28 annual dividend provide tangible support for the UNH stock investment case. Wall Street also sees meaningful upside if Medicare Advantage trends and Optum’s recovery continue. Overall, the most likely path forward is further progress, although quarterly results may remain uneven. For investors seeking dividend income and a recovering earnings story, UNH stock looks worth keeping on the radar.
On the date of publication, Ebube Jones did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
This Dividend Stock Is Staging a Turnaround in 2026 and Pays More Than 2.4% This Dividend Stock Is Beating the Market in 2026 and Yields 2.36% This High-Yield Construction Stock Just Raised Its Dividend by 40% Dear Intuit Stock Fans, Mark Your Calendars for September 17