

Needham’s senior analyst Mike Cikos says Okta (OKTA) shares are worth buying ahead of the company’s upcoming annual conference. Cikos maintained a “Buy” rating on OKTA this morning and raised his price target to $230, signaling potential upside of more than 20% from current levels.
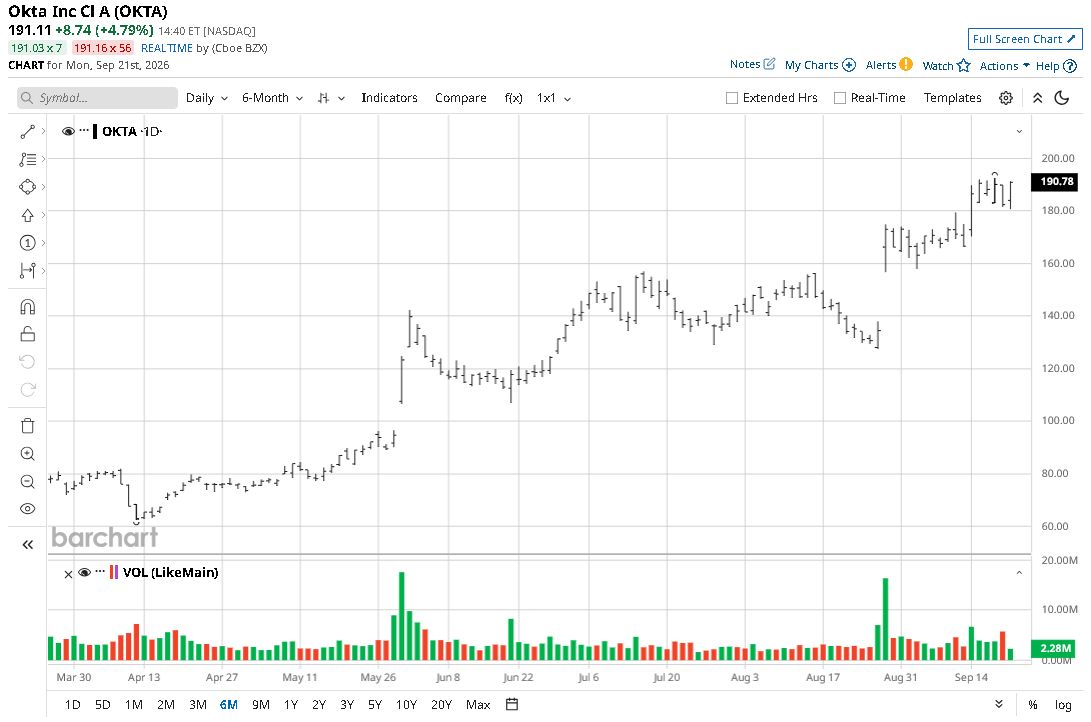
His bullish research note is significant given Okta stock has already been a major outperformer in 2026, currently trading at more than 2x its price at the start of this year.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
 www.barchart.com
Needham’s Bullish View on Okta Stock
Cikos raised his price target on OKTA shares primarily because of strong secular tailwinds across enterprise identity and access management (IAM).
According to the analyst, recent industry surveys suggest about 75% of tech leadership teams plan to increase their budget allocations toward enterprise identity security.
And OKTA remains uniquely positioned to capture this expanding TAM as organizations prioritize zero-trust infrastructure, he added.
In his research report, Mike Cikos highlighted the upcoming conference and product unveilings as immediate near-term catalysts.
Specifically, the company is expected to showcase next-gen, artificial intelligence-driven identity governance, privileged access controls, and threat protection tools designed to “deepen platform monetization” and sustain high top-line growth.
What Else Makes OKTA Shares Attractive?
Beyond core demand metrics, Needham points to OKTA’s strategic ecosystem expansions as a key growth engine.
Collaborations and platform integrations with major industry titans, including ServiceNow (NOW) and AI pioneer Anthropic, reinforce the firm’s position as the neutral, enterprise-grade identity layer.
These partnerships unlock significant long-term cross-selling opportunities by embedding OKTA deeper into enterprise AI workflows and automated service management systems.
Combined with strong Q2 earnings and solid underlying financial health, Cikos expects these AI-driven integrations to improve customer retention, lifetime value metrics, and operating margins.
That said, OKTA stock has a history of closing both September and October in the red — a seasonal pattern that somewhat dulls its near-term appeal.
What’s the Consensus View on Okta?
Investors should also note that other Wall Street firms are not nearly as bullish on OKTA shares as Needham.
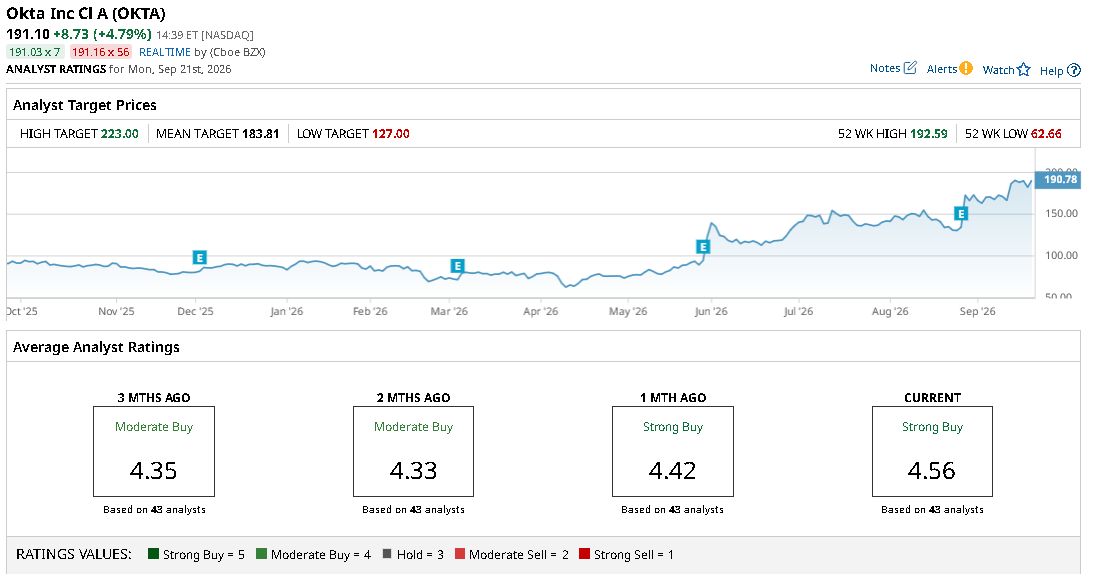
While the consensus rating on Okta remains at “Strong Buy,” the mean price target of about $184 suggests much of the upside is already baked into the company’s share price at current levels.
 www.barchart.com
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
‘Substantially Higher Than a Car’: XPeng’s CEO on What Each Robot Could Earn. First It Has to Survive a Brutal Price War. Needham Just Upped Its Price Target on OKTA Stock. Here's Why. Why It’s Time to Load Up on Meta Stock As Snap Partners With Nvidia on Its Specs, Here’s How You Should Play SNAP Stock