

Henry Schein, Inc. (HSIC), headquartered in Melville, New York, provides health care products and services to dental practitioners, laboratories, physician practices, and ambulatory surgery centers, government, institutional health care clinics, and other alternate care clinics. Valued at $9.5 billion by market cap, the company provides shop supplies, as well as dental and medical solutions and services to improve operational success and clinical outcomes.
Companies worth $2 billion or more are generally described as “mid-cap stocks,” and HSIC fits right into that category with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the medical distribution industry. A 94-year leader in healthcare distribution, HSIC is known for quality and reliability. Its product mix spans exclusive deals and private-label consumables serving 1 million+ customers. Under its BOLD+1 plan, acquisitions expand its footprint in software, specialty, and services to fuel digital transformation and long-term growth.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
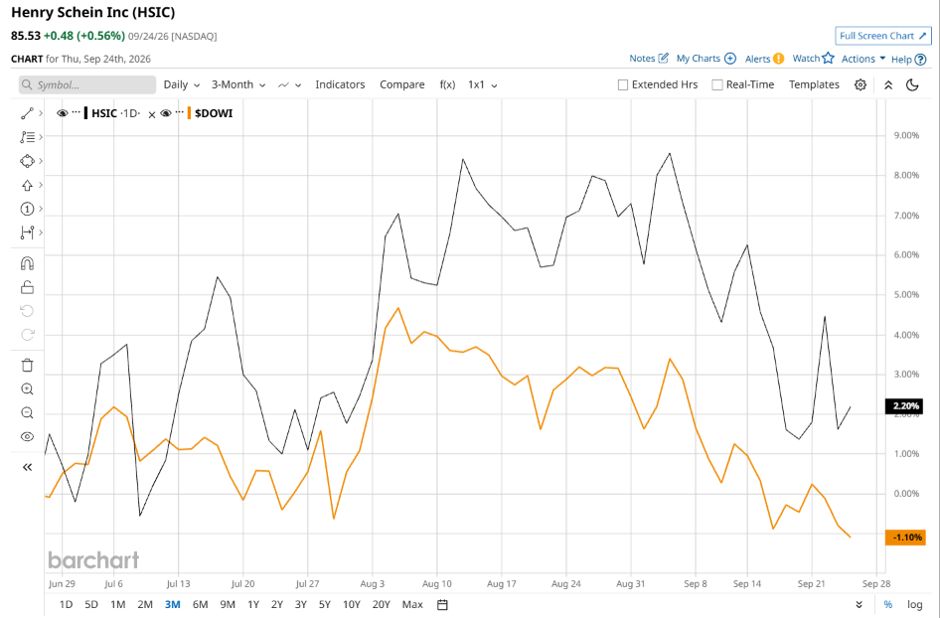
Despite its notable strength, HSIC slipped 7.2% from its 52-week high of $92.18, achieved on Aug. 4. Over the past three months, HSIC stock has gained 3.3%, outperforming the Dow Jones Industrials Average’s ($DOWI) 1.1% dip during the same time frame.
 www.barchart.com
In the longer term, shares of HSIC rose 13.2% on a YTD basis and climbed 26.2% over the past 52 weeks, outperforming DOWI’s YTD gains of 6.8% and 11.8% returns over the last year.
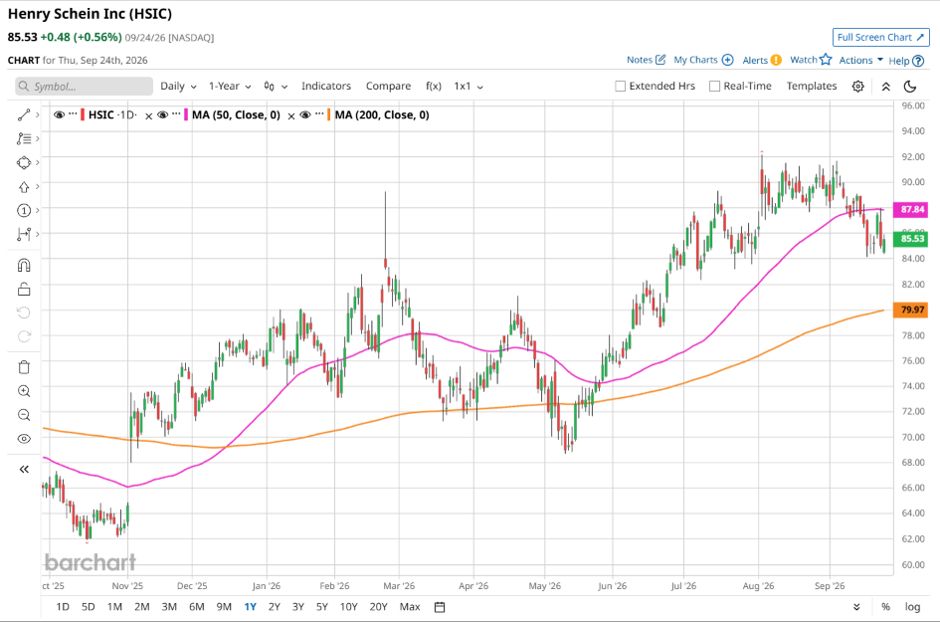
To confirm the bullish trend, HSIC has been trading above its 200-day moving average since early November, 2025, with slight fluctuations. However, the stock is trading below its 50-day moving average since mid-September.
 www.barchart.com
HSIC posted strong outperformance driven by robust internal sales and dental merchandise gains, despite softer U.S. demand and pressure on gross margins. Growth was propelled by market share gains across North America, expansion of the Henry Schein One platform (now at 13,000 Dentrix Ascend subscribers), and demand for AI tools alongside high-margin specialty lines like implants and S.I.N. 360. Management also reaffirmed its target of over $200 million in operating income gains through procurement, outsourcing, and pricing strategies while continuing strategic tech investments.
On Aug. 4, HSIC shares rose over 3% after reporting its Q2 results. Its adjusted EPS of $1.27 exceeded Wall Street expectations of $1.22. The company’s revenue was $3.5 billion, exceeding Wall Street forecasts of $3.4 billion. HSIC expects full-year adjusted EPS in the range of $5.29 to $5.39.
In the competitive arena of medical distribution, McKesson Corporation (MCK) has lagged behind HSIC, with 6% gains on a YTD basis and 14.3% returns over the past 52 weeks.
Wall Street analysts are reasonably bullish on HSIC’s prospects. The stock has a consensus “Moderate Buy” rating from the 18 analysts covering it, and the mean price target of $97.88 suggests a potential upside of 14.4% from current price levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
This Stock Pays a 6% Yield — and Has Raised Its Dividend for 28 Straight Years SpaceX’s Weight in the Nasdaq-100 Is Set to Double, But There Are More Important Catalysts to Watch for SPCX Stock JPMorgan Just Upgraded CoreWeave Stock. Here's Why. The Bond Market is Breaking Down. Here’s Why – And How Investors Can Navigate Spiking Yields & Sinking Small-Caps.