

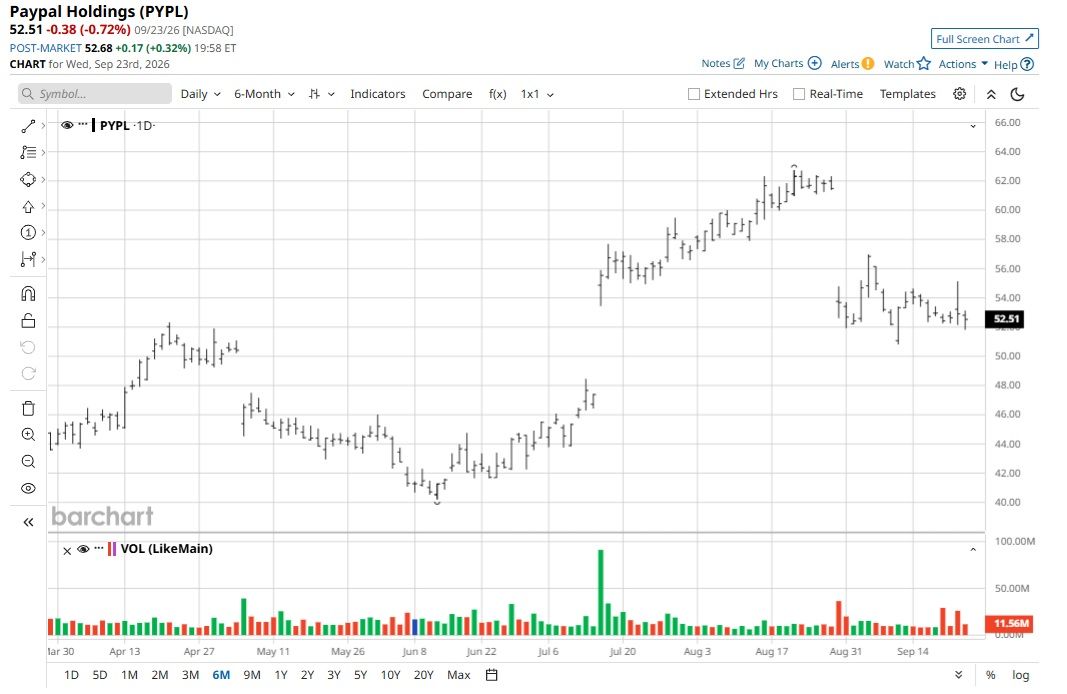
PayPal (PYPL) stock has witnessed significant volatility in the last 52 weeks, correcting from a high of $79.21 to a low of $38.46 earlier this year. The downside catalysts included a disappointing fourth quarter of fiscal 2025, a weaker-than-expected profit outlook for 2026, and a sudden CEO change. At 52-week lows, PYPL stock was then supported by a roughly $53 billion takeover approach from Stripe and Advent International, which helped PayPal stock surge. But the premium evaporated when the consortium abandoned its bid. Since then, the focus has returned to the company’s potential turnaround plan.
Most recently, PayPal’s partnership with Meta Platforms (META) for Muse AI shopping bots has created some excitement and positive price action. Payment apps have been partnering with AI models in an effort to make online shopping easier for consumers. As a part of its turnaround plan, PayPal also recently reduced its India headcount by 600 employees as part of global restructuring to curb operational costs. At the same time, it remains to be seen whether Venmo can be monetized to boost profitability.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
About PayPal Stock
Headquartered in San Jose, California, PayPal is a technology platform with products that enable digital payments and simplify commerce experiences for consumers and merchants. As of December 2025, PayPal connected consumers and merchants with 439 million active accounts across approximately 200 markets.
On the consumer side, the company provides digital wallets and other solutions that allow individuals to shop and pay with PayPal and Venmo both online and in-person. On the merchant side, PayPal offers online branded checkout solutions. Further, PayPal is also a provider of buy now, pay later (BNPL) solutions. Backed by its strong global presence, the payments company processed $1.79 trillion in total payment volume in 2025.
For Q2 fiscal 2026, PayPal reported revenue growth of 5% on a year-over-year (YOY) basis to $8.7 billion. For the same period, total payment volume increased 10% YOY to $486.4 billion. While growth has been muted, PayPal also reported healthy free cash flow of $1.8 billion for the quarter.
It’s worth noting that PayPal stock trades at a forward price-to-earnings (P/E) ratio of 9.7 times. Considering the valuation, it’s unsurprising that PYPL stock has trended higher by 23% in the last six months.
 www.barchart.com
Venmo Can Create Value
Venmo is a potential value creator within PayPal’s payment ecosystem. In April 2026, CEO Enrique Lores made Venmo a separate business division. This should allow the company to focus on the growth driver, while Venmo as a standalone business segment may be an attractive candidate for sale at the same time.
In terms of growth, PayPal reported total TPV growth of 8% and 9% for Q1 and Q2 of fiscal 2026, respectively. TPV growth reported by Venmo came in at 14% for the same two periods. Clearly, two consecutive quarters of mid-teens growth makes Venmo a potential source of turnaround for PayPal. The key factor, however, is that Venmo has millions of users and has been under-monetized. Even if the user base remains the same and revenue per user growth is boosted, there will be a significant impact on revenue, EBITDA margin, and free cash flows.
Finally, PayPal reported a cash buffer of $15.3 billion in Q2. The company also has an annualized FCF potential of $7.2 billion. PayPal’s financial flexibility is high and provides headroom for investment in product development, while value creation is also likely to sustain through share repurchases and dividends.
What Do Analysts Say About PYPL Stock?
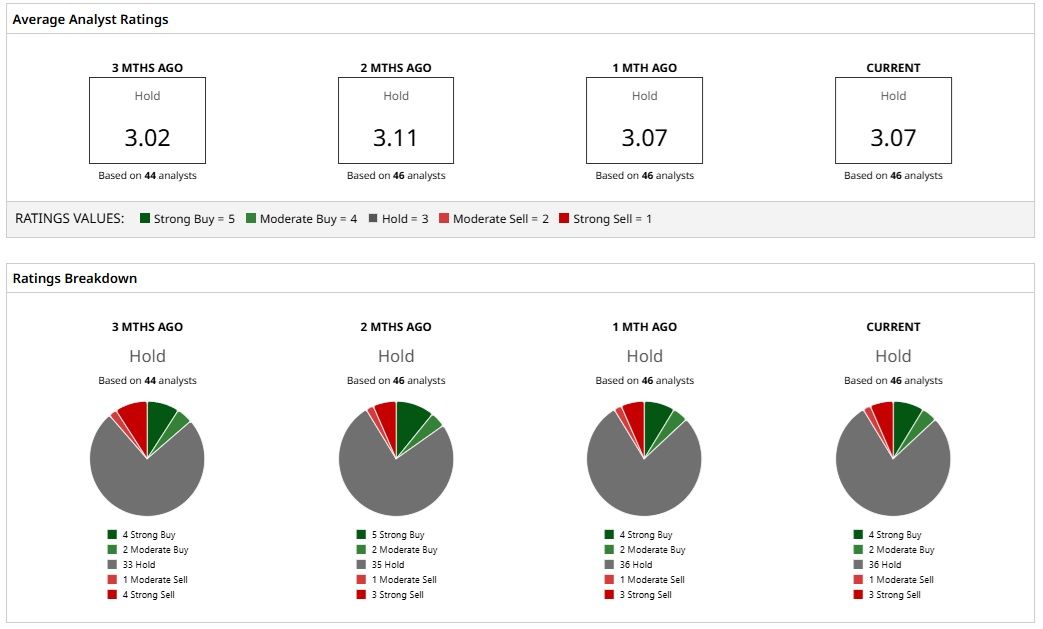
Based on 46 analysts with coverage, PYPL stock has a consensus “Hold” rating. While four analysts have a “Strong Buy” rating for the stock, two have a “Moderate Buy,” 36 have a “Hold,” one has a “Moderate Sell,” and three analysts have a “Strong Sell” rating.
The mean price target of $55.95 represents marginal potential upside of 2% from current levels. However, the most bullish price target of $72 suggests that PYPL stock could climb as much as 31% from here.
 www.barchart.com
On the date of publication, Faisal Humayun Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Qualcomm Just Agreed to Acquire Robotics Software Firm Picknik. How to Approach the Stock Now. PayPal’s Turnaround Plan Depends on Venmo’s Monetization and Operational Efficiencies Analysts Raise Palo Alto Networks Stock Price Targets - What's the Best PANW Play? Wells Fargo and Other Bank Stocks Are Facing a New AI Threat — From Meta