

Minneapolis, Minnesota-based U.S. Bancorp (USB), with a market capitalization of approximately $92.4 billion, is a diversified financial services company and the parent of U.S. Bank. It provides banking, lending, payment processing, wealth management and other financial services to individuals, businesses and institutions across the United States and internationally.
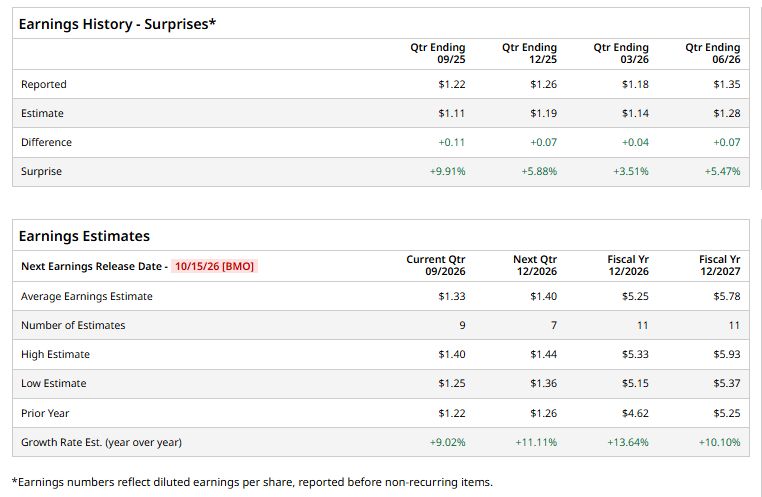
USB is set to report its Q3 earnings on Thursday, October 15, 2026, before the market opens. Ahead of the release, analysts expect the company to report diluted EPS of $1.33, up 9% from $1.22 in the year-ago quarter. Moreover, USB has surpassed Wall Street’s EPS estimates in each of the past four quarters, highlighting its consistent earnings performance.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For fiscal 2026, analysts expect the company to report EPS of $5.25, up 13.6% from $4.62 in fiscal 2025. EPS is projected to increase another 10.1% year over year to $5.78 in fiscal 2027.
 www.barchart.com
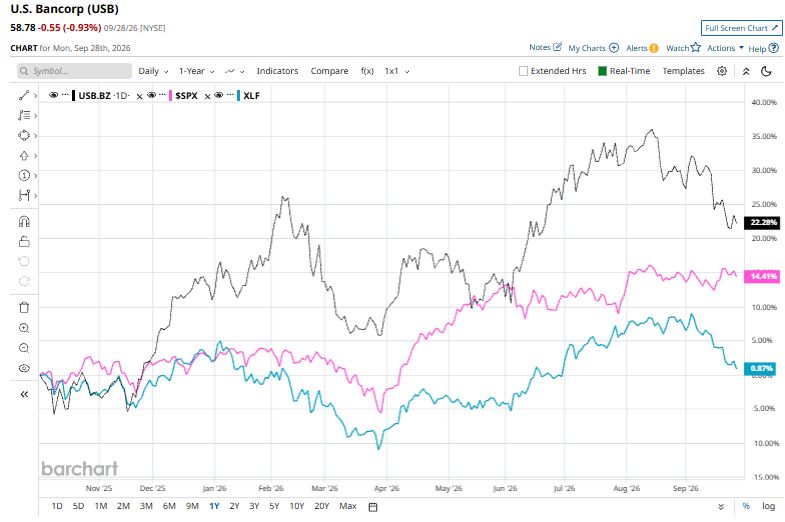
USB stock has climbed 18.9% over the past 52 weeks, slightly outpacing the S&P 500 Index ($SPX), which gained 15.7%. USB has also significantly outperformed the State Street Financial Select Sector SPDR ETF (XLF), which posted only a marginal gain over the same period.
 www.barchart.com
U.S. Bancorp has outpaced the broader market over the past year, with its strong performance supported by robust financial results. In the second quarter, the company reported record net revenue of $7.7 billion, up 10.1% year over year, while EPS increased 22%. Growth in net interest income and fee revenue, along with a 3.9% dividend increase, may have further supported investor sentiment.
More recently, on September 28, U.S. Bank launched two new credit cards for small business owners, expanding its payments and banking offerings. The products are designed to deepen relationships with small-business customers by combining cash-back rewards, spending controls and expense-management tools with qualifying business checking accounts, potentially supporting future growth in the company’s payments business.
Analysts remain moderately bullish on USB, with the stock carrying a consensus “Moderate Buy” rating. Among the 23 analysts covering the stock, 12 recommend a “Strong Buy,” one rates it a “Moderate Buy,” and 10 suggest a “Hold.” Meanwhile, the average price target of $70.26 implies potential upside of 19.5% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Temporary Weakness in Intellia Stock Seems Like a Buying Opportunity The Muse AI Threat to Progressive Stock Is Currently Overstated Nvidia Price Targets Are Higher as Analysts Up Their Forecasts - What's the Best NVDA Play Here? Wall Street Is Giving Up on Nike. How to Play NKE Ahead of Q1 Earnings