

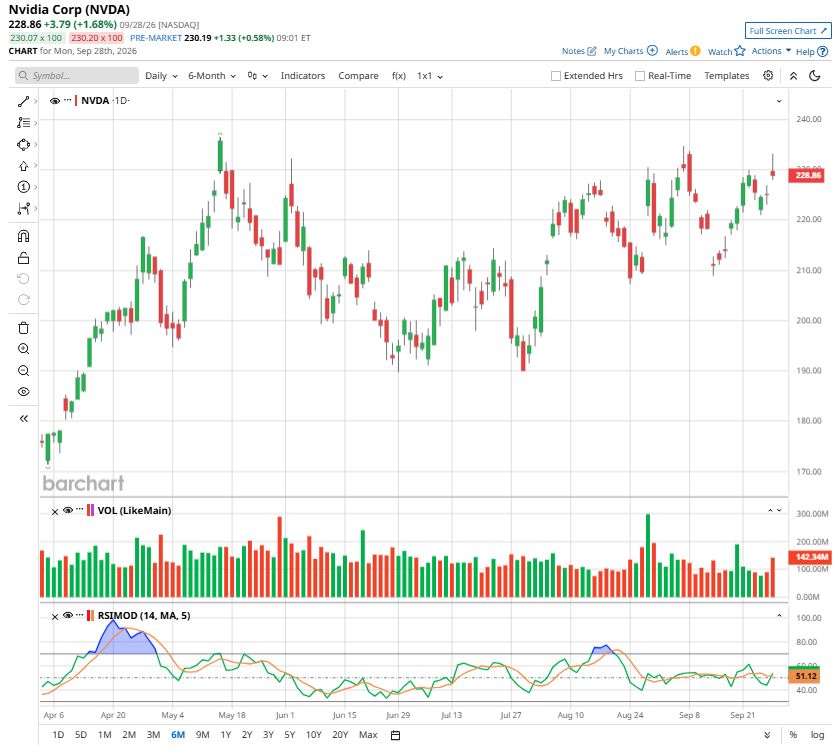
Nvidia's (NVDA) stock performance this year may not look exceptional at first glance, but shares have outperformed the broader market. NVDA stock has gained 24% year-to-date (YTD), compared with a 12% YTD increase for the S&P 500 ($SPX).
Looking ahead, Nvidia is well-positioned to continue beating the broader market. Demand for its GPUs and CPUs powering artificial intelligence (AI) infrastructure remains solid, suggesting earnings will expand rapidly in the medium term. At the same time, Nvidia's valuation still looks compelling.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Nvidia’s strong growth, solid opportunities, and a compelling valuation support the investment case. Let's take a closer look.
The AI Infrastructure Buildout Will Keep Pushing Nvidia Higher
Nvidia continues to benefit from the rapid expansion of AI infrastructure, with its latest results highlighting the scale and durability of demand for accelerated computing.
Nvidia reported quarterly revenue of $96 billion for the second quarter of fiscal 2027, more than twice the level recorded a year earlier. Importantly, the quarter marked the fourth consecutive period of accelerating year-over-year (YOY) revenue growth, suggesting demand for the company's GPUs and CPUs continues to rise.
Nvidia is also benefiting from its broad customer base. The company is seeing solid demand coming from hyperscale cloud providers, AI research organizations, AI-native companies, enterprises, and sovereign customers. This diversification reduces Nvidia’s dependence on any single customer segment while expanding its addressable market.
 www.barchart.com
Nvidia’s data-center business continues to strengthen its investment case. Data-center segment revenue increased 18% sequentially to approximately $89 billion, with both hyperscale and ACIE customers contributing to the expansion. According to the company, hyperscale revenue rose 13% sequentially to $49 billion, reflecting continued demand for the Blackwell platform. Meanwhile, the ACIE division within the data-center segment — which includes neocloud providers, industrial customers, and enterprises — grew even faster with revenue increasing 25% sequentially and 138% YOY to $40 billion.
Nvidia’s next major growth catalyst is the rollout of its Vera Rubin platform. The company has begun shipping the architecture and expects it to achieve the fastest product ramp in Nvidia’s history. Management expects Vera Rubin to account for approximately 20% of data-center revenue in Q3 fiscal 2027.
Networking represents another important component of the broader AI infrastructure opportunity. Nvidia’s networking revenue increased 18% sequentially, while revenue from its Spectrum-X Ethernet platform “grew 2.6x on a year-over-year basis.”
At the same time, the growing adoption of agentic AI is broadening Nvidia’s opportunity in data-center CPUs. Management continues to estimate approximately $20 billion of total server CPU demand for the current fiscal year. Moreover, Nvidia’s preliminary expectation is for CPU revenue to “more than double in fiscal 2028.” While CPUs remain a smaller contributor for Nvidia than GPUs, they present a significant growth opportunity.
Looking ahead, Nvidia expects Q3 revenue of approximately $108 billion, implying roughly 12% sequential growth. Data-center demand is expected to remain the primary growth driver, with continued expansion in ACIE providing additional support.
Management also expects hyperscale growth to accelerate again in Q4 and remain strong into fiscal 2028 as Vera Rubin ramps and supply increases. Most notably, Nvidia’s preliminary outlook calls for approximately 70% YOY revenue growth in fiscal 2028.
Taken together, the continued expansion of AI infrastructure, the Blackwell and Vera Rubin product cycles, accelerating networking demand, and growing opportunities in CPUs provide multiple avenues for Nvidia to sustain solid growth.
The Valuation Supports a ‘Buy’ Rating
Nvidia’s valuation appears attractive relative to its growth prospects and peers. NVDA stock currently trades at 24.7 times forward earnings, which is compelling given its solid revenue growth and ongoing EPS expansion.
Analysts expect earnings to more than double in fiscal 2027, followed by an estimated 66% YOY increase in the subsequent fiscal year. This projected earnings growth indicates that NVDA stock is undervalued, implying that it is a “Buy” at current levels.
Nvidia’s forward price-to-earnings (P/E) multiple is also well below peers. For example, Advanced Micro Devices (AMD) stock trades at 94.5 times forward earnings.
Nvidia Stock Is a Good Buy Now
The ongoing AI infrastructure buildout, strong demand for the Blackwell and Vera Rubin platforms, a growing CPU opportunity, and Nvidia's low valuation make NVDA stock a good buy now.
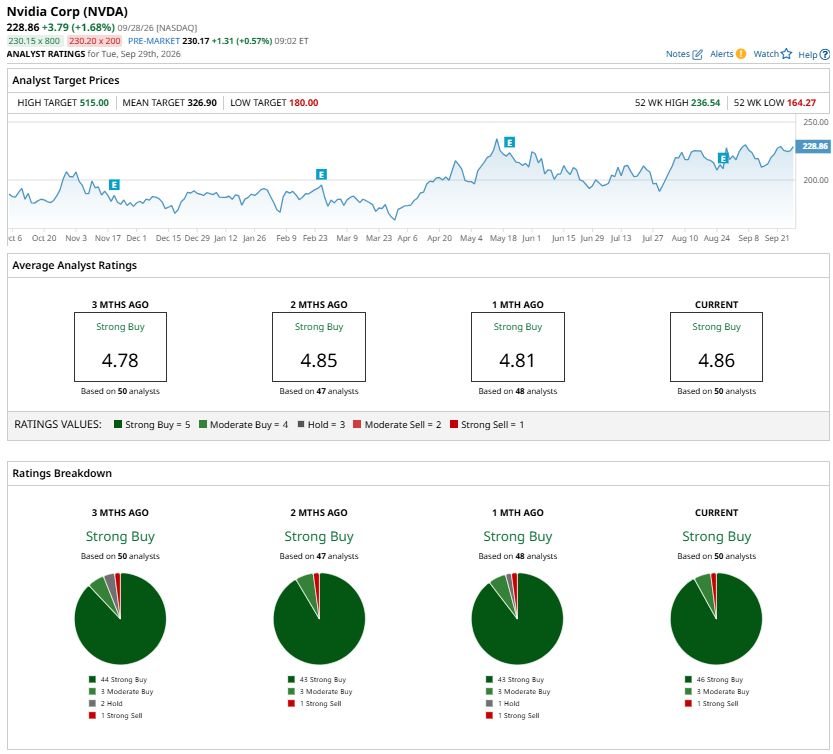
Wall Street also remains bullish. Based on 50 analysts with coverage, NVDA stock has a consensus “Strong Buy” rating. Out of those analysts, 46 have a “Strong Buy” rating, three have a “Moderate Buy” rating, and only one analyst has a “Strong Sell.” The average price target of $326.90 implies potential upside of 42% from current levels.
 www.barchart.com
On the date of publication, Sneha Nahata did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Why Nvidia Stock Is a Good Buy Now Trying to Pick Individual Stocks to Buy Is the Most Pointless Thing Investors Can Do Now Grab's Stock Hit a Three-Year Low After Its $4.5 Billion Deal. Then Insiders Bought $30 Million. ASTS Stock Alert: What to Know as Takeover Speculation Swirls Around AST SpaceMobile