

United Airlines Holdings, Inc. (UAL), headquartered in Chicago, Illinois, operates passenger and cargo air transportation. Through United Airlines and its subsidiaries, the carrier provides passenger flights, freight and mail services, loyalty programs, ground handling, aircraft maintenance, and flight training.
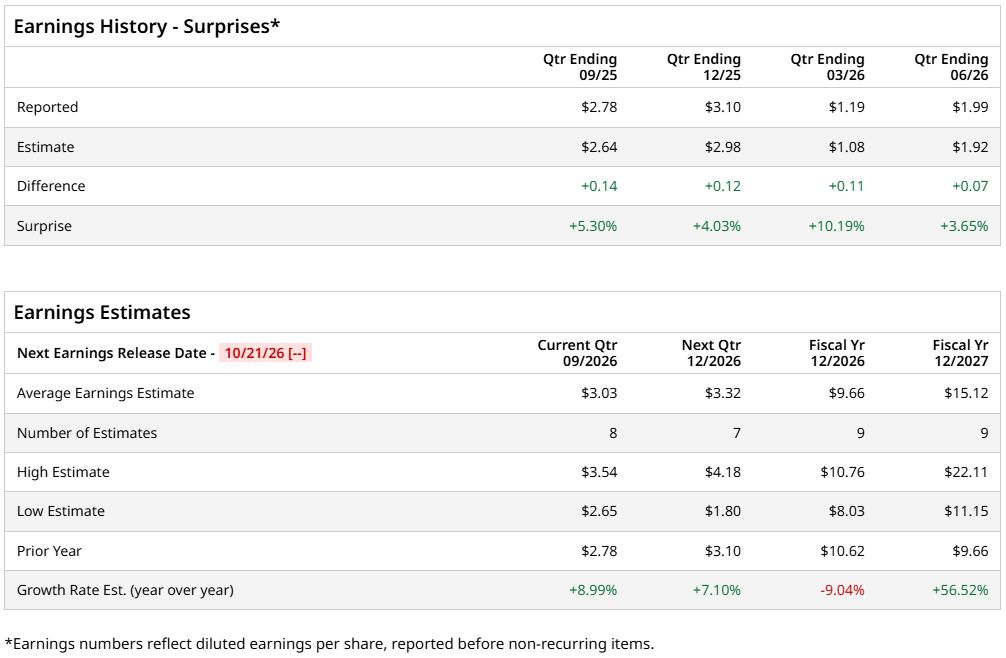
With a market cap of nearly $36.6 billion, the airline is scheduled to report its Q3 FY2026 results after the market closes on Tuesday, Oct. 20. Wall Street expects diluted EPS of $3.03, up 9% from $2.78 in the year-ago quarter. The company has also exceeded EPS estimates in each of the past four quarters, which is noteworthy.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Looking beyond the upcoming quarter, analysts expect diluted EPS of $9.66 in FY2026, representing a 9% year-over-year (YOY) decline. However, FY2027 diluted EPS is projected to grow 56.5% from the prior year to $15.12.
 www.barchart.com
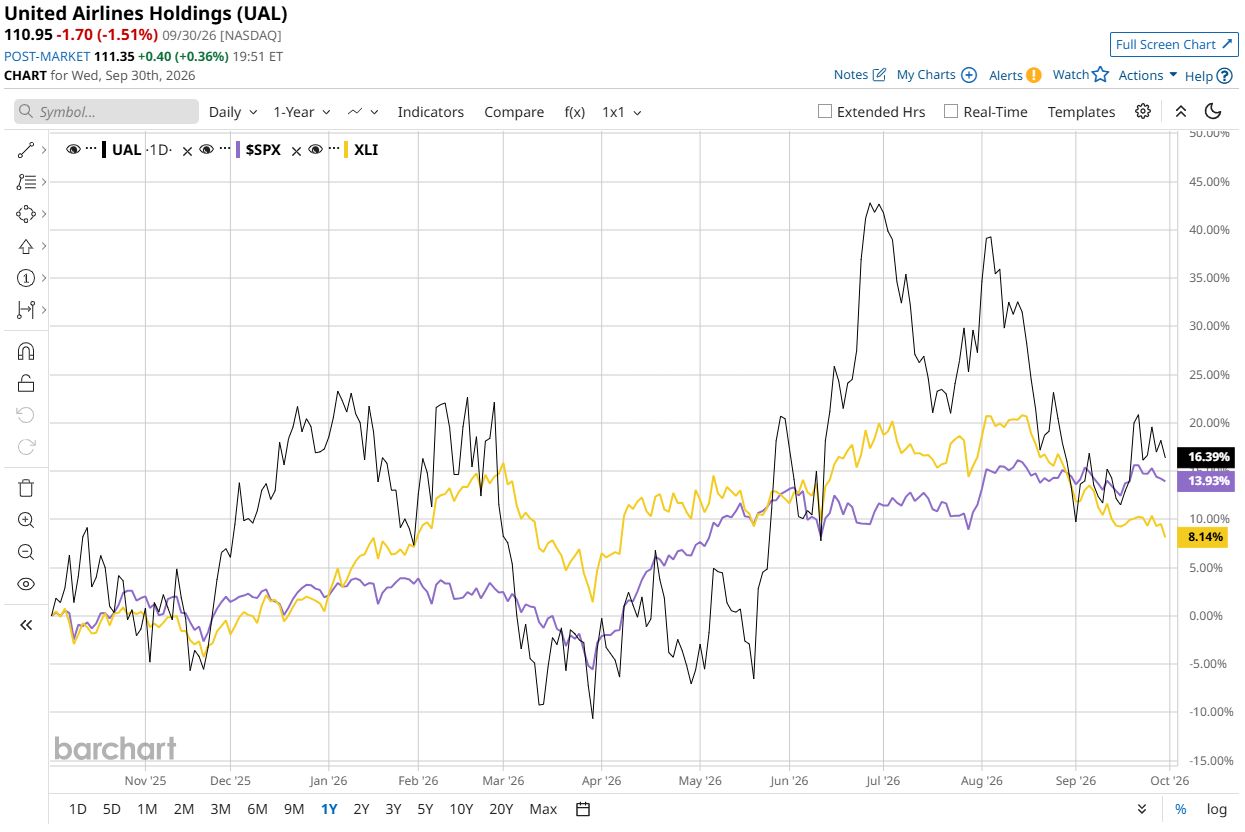
The stock’s performance, however, has been more restrained than those earnings expectations might suggest. UAL stock has gained 15% over the past 52 weeks, slightly ahead of the S&P 500 Index ($SPX), which has advanced 14%. But in 2026, UAL stock is marginally down, while the benchmark has climbed 11.8%.
The sector comparison puts that lag into sharper focus. The State Street Industrial Select Sector SPDR ETF (XLI) has gained 8.3% over the past 52 weeks and is up 7.7% in 2026. That said, while UAL stock has held up reasonably well over the longer 52-week period, its 2026 performance has fallen behind both the broader market and its sector benchmark.
 www.barchart.com
Fuel costs became a major earnings headwind in 2026 as oil prices surged. In its Q2 earnings release, the carrier said it expected nearly $6 billion in additional full-year fuel expense versus its initial 2026 estimate. Q2 fuel expense itself jumped 84% YOY to $2.3 billion, intensifying pressure on margins.
Even with that cost shock, the revenue picture remained resilient. The airline reported Q2 total revenue per available seat mile (TRASM) growth of 12.1% YOY and has now raised its full-year 2026 adjusted EPS guidance to $9–$11. Management also noted that it expects to recover 80% to 90% of the fuel-price increase in Q3 and 100% by Q4 through pricing, provided demand and pricing trends hold.
Against that backdrop, Wall Street’s view of the shares remains bullish. UAL stock carries an overall “Strong Buy” rating among 25 analysts covering the stock. Of those analysts, 21 recommend “Strong Buy,” two recommend “Moderate Buy,” one suggests “Hold,” while one has flagged a “Strong Sell.”
Analyst targets also show how much upside the Street sees relative to the current share price. UAL stock has an average analyst price target of $155, representing potential upside of 39.7%, while the Street-High target of $203 implies a gain of 83% from current levels.
On the date of publication, Aanchal Sugandh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
This Healthcare Stock Just Raised Its Dividend by Nearly 15%. Eli Lilly vs. Novo: The Hidden Battle Behind the Weight-Loss Platform Reshaping Industries Micron Just Reported Earnings in the Middle of a Memory Shortage. Here Are the Numbers You Need to Know. This Analyst Just Downgraded Moderna Stock. Here's Why.