

PepsiCo (PEP) is a recognizable global food and beverage giant, but its investment story today goes well beyond the Pepsi name. Its portfolio now includes snacks, soft drinks, sports drinks, and other everyday consumer products, such as Frito-Lay, Gatorade, Doritos, Lay’s, Quaker, and Mountain Dew. The company is all set to report its fiscal third-quarter earnings report on Oct. 8. It enters its third-quarter report with international growth running strongly, U.S. food volumes finally moving in the right direction, and management spending heavily to improve affordability.
But there are still some hiccups. Investors would want to see that the fixes PepsiCo has been putting in place are beginning to work where the business has been struggling the most.
More Yield, Less Trap: Sign up free to get Barchart’s daily Dividend Investor newsletter straight to your inbox.
 www.barchart.com
What is Going Right for PepsiCo?
PepsiCo’s first-half performance showed investors' volume momentum, something it had been missing for a while. During the Q2 earnings call, CEO Ramon Laguarta said global food volumes had increased 3% and beverage volumes 2% in the first half, representing the company's fastest overall volume growth since 2022. Total revenue for the first half increased roughly 7%, while reported EPS increased 6%. Laguarta attributed the improvement to the company's efforts around affordability, innovation, and portfolio changes.
Notably, international operations were doing much of the heavy lifting, while the U.S. foods business was beginning to recover after a period of volume weakness. This is important as volume growth gives the company a healthier foundation than simply pushing prices higher.
PepsiCo has been spending money to make its products more accessible while simultaneously changing what it sells. The Q3 report should reveal whether that combination is generating sustained volume rather than a temporary lift.
What Investors Need to Watch
The biggest question remains its U.S. consumer segment. While PepsiCo's North American foods business improved, management acknowledged that the recovery was not as strong as expected.
PepsiCo needs to make its products more attractive to consumers without relying so heavily on promotions and discounts that profitability suffers. While volume growth is an important number to watch in Q3, investors should also look at whether PepsiCo can achieve that improvement without giving away too much margin.
PepsiCo already expects greater commodity pressure in the second half while continuing to use productivity savings to offset some of those costs. So instead of looking at EPS growth alone, investors need to understand how much is coming from actual operating improvement versus productivity, tariff-related benefits, and other factors.
For the full year 2026, management expects organic revenue growth of 2% to 4% and core constant-currency EPS growth of 4% to 6%. Importantly, PepsiCo said it was not planning to cut back on growth investments simply to protect earnings.
The Dividend Gives Investors Another Reason to Stay Patient
PepsiCo is not a high-growth stock, but its dividend status gives it an edge, especially with income-focused investors. The company maintained its “Dividend King” status by increasing its annualized dividend by 4% in 2026 to $5.92 per share, which marked its 54th consecutive year of dividend hikes.
PepsiCo also offers an appealing forward dividend yield of 4.7%, much higher than the consumer staples and market average. Despite its recovery efforts, it maintains a forward payout ratio of 68%.
Management had even reiterated in the first quarter that the company plans to pay roughly $7.9 billion in dividends and another $1 billion in share repurchases in 2026. It shows that returning cash to shareholders is not an afterthought for PepsiCo but a central part of its business strategy. If the U.S. food recovery gains traction and international growth remains healthy, investors could potentially collect a growing dividend while waiting for the stock's earnings growth to improve.
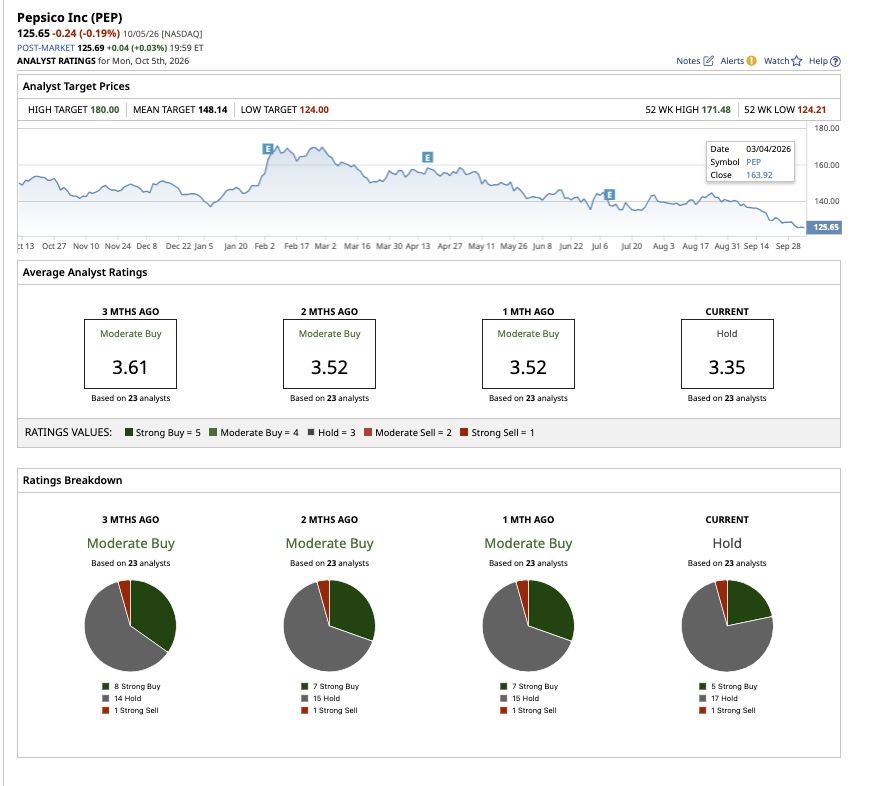
On Wall Street, PepsiCo has a consensus “Hold” rating. Out of the 23 analysts covering PEP stock, five have a "Strong Buy" rating, 17 suggest a "Hold," and one rates it as a "Strong Sell." The mean target price of $148.14 implies a potential upside of 18% from current levels. The Street-high price estimate for PEP stock is $180, implying a potential upside of 43.2% over the next 12 months.
 www.barchart.com
On the date of publication, Sushree Mohanty did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.