

PepsiCo (PEP) reports fiscal Q3 earnings on Thursday, Oct. 8. Analysts expect adjusted EPS of $2.30, barely above last year’s $2.29. PepsiCo has beaten earnings estimates in its last four quarterly reports.
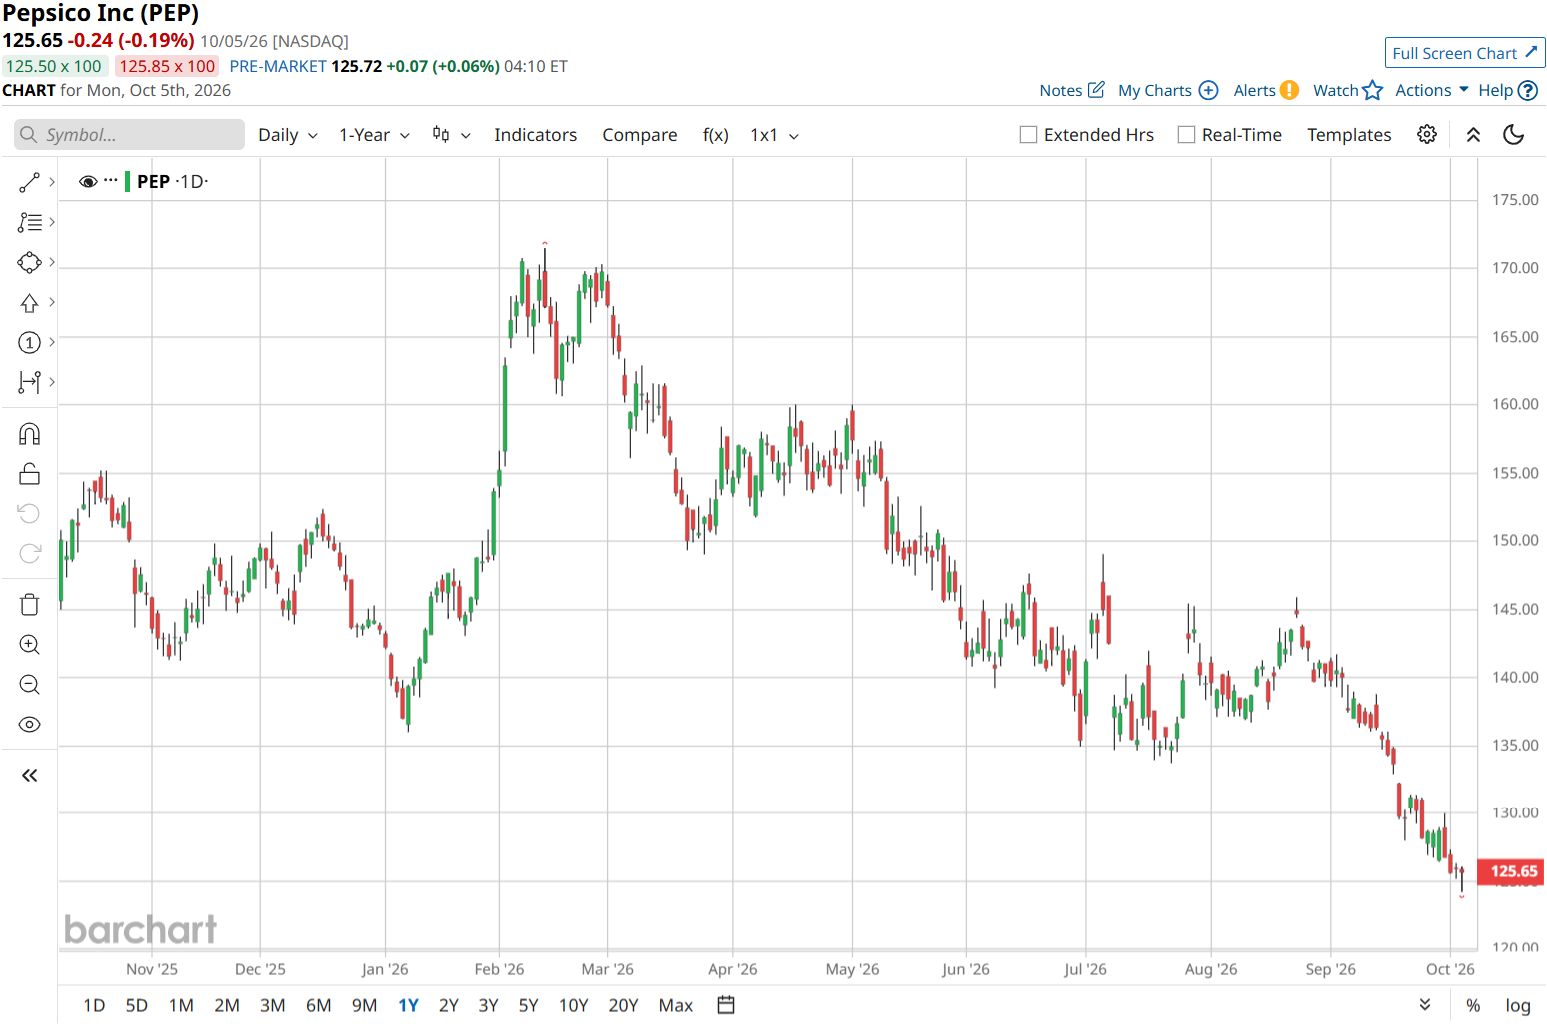
But shareholders have had a tough year. PepsiCo shares have fallen 11.50% over the past 52 weeks, while the S&P 500 ($SPX) gained 15.76% and the broader consumer staples sector rose 5.5%.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Higher prices and fuel costs are squeezing household budgets, especially for lower- and middle-income shoppers. Unit sales have fallen over the past two years, and projected sales growth of 3.3% over the next 12 months suggests a slow recovery.
The July report gave investors more reasons to worry. PEP shares fell 3.3% after North American food sales dropped 2% and adjusted EPS of $2.20 missed the $2.23 estimate.
Can PepsiCo show that its pricing changes, product cuts, and cheaper options are getting growth back on track? Let’s take a closer look.
The Numbers Behind PepsiCo’s Next Report
PepsiCo sells drinks and packaged foods worldwide through its brands and distribution network. Its shares have fallen 11.50% over the past 52 weeks and 12.45% year to date.
 www.barchart.com
Even after that decline, the stock trades at 14.67x forward earnings, slightly above the sector’s 14.38x.
The dividend gives shareholders some income while they wait. The quoted figures show a $5.81 annual dividend, a 4.61% yield versus the consumer staples average of 1.89%, and a 68.54% forward payout ratio. The current quarterly payment is $1.48, which works out to $5.92 annually. The latest payment was Sept. 30, with a Sept. 4 record date. PepsiCo has raised its dividend for 54 consecutive years through 2026, cementing its Dividend King status.
The July 9 second-quarter report showed revenue growing 6.4% to $24.181 billion from $22.726 billion, with organic growth of 2.4%. GAAP EPS rose 137% to $2.18 from $0.92. Core EPS grew just 4% to $2.20 from $2.12, or 1% excluding currency effects.
Operating profit increased 125% to $4.023 billion from $1.789 billion. Reported operating margin rose 875 basis points to 16.6% from 7.9%. But core operating profit grew only 4% to $4.067 billion from $3.911 billion, while core margin fell 40 basis points to 16.8% from 17.2%. The adjusted figures show a much smaller improvement, with margins still under pressure.
PepsiCo kept its 2026 targets unchanged: 2%-4% organic revenue growth, 4%-6% core EPS growth excluding currency effects, and a roughly 22% core tax rate. It also expects capital spending below 5% of revenue and a free cash flow conversion of at least 80%. Planned shareholder payments total $8.9 billion, including $7.9 billion in dividends and $1 billion in buybacks.
What Could Get Growth Moving Again?
PepsiCo is getting a sales boost from Poppi and its Alani Nu distribution deal. Acquisitions, after accounting for divestitures, added seven percentage points to PepsiCo Beverages North America’s Q1 2026 revenue growth, largely from those two additions.
Alani Nu gained market share by both volume and sales value after joining PepsiCo’s direct-store-delivery network. In Q2, CEO Ramon Laguarta said Poppi’s distribution problems were “pretty much solved,” and the brand was growing again. The Oct. 8 report will give investors another look at that progress.
PepsiCo is also expanding its $2 billion-plus “permissible” food portfolio. SunChips, Siete, and Quaker rice cakes gained volume share in Q1. New products include Doritos Protein, Good Warrior beef sticks, Smartfood FiberPop, and SunChips Fiber, with wider distribution planned throughout 2026. These give shoppers more protein- and fiber-focused choices.
To improve production, PepsiCo began a collaboration with Siemens (SIEGY) and NVIDIA (NVDA) in January. The technology uses AI and virtual copies of factories and warehouses to test changes before making them. Initial use increased throughput by 20%, achieved nearly 100% design validation, and cut capital spending by 10%–15%. It also identified up to 90% of potential problems before physical changes were made. U.S. pilots are underway, with plans to expand globally.
What Wall Street Expects From PepsiCo
PepsiCo reports earnings on Oct. 8 before the market opens. Analysts expect September-quarter EPS of $2.29, unchanged from last year. For full-year 2026, they forecast $8.56 per share, up 5.16% from $8.14.
But some analysts have grown more cautious. JPMorgan Chase (JPM) analyst Andrea Teixeira downgraded the stock from Overweight to Neutral and cut her price target by 19%, from $170 to $132. She also lowered her 2027 EPS estimate by $0.19 to $8.86, below the $8.93 consensus, citing concerns about PepsiCo’s North American recovery.
Citigroup (C) also stepped back after PepsiCo’s mixed second-quarter results. Continued weakness in North America led the firm to downgrade the stock from Buy to Neutral and lower its target from $170 to $145. Both firms want to see more progress in North America.
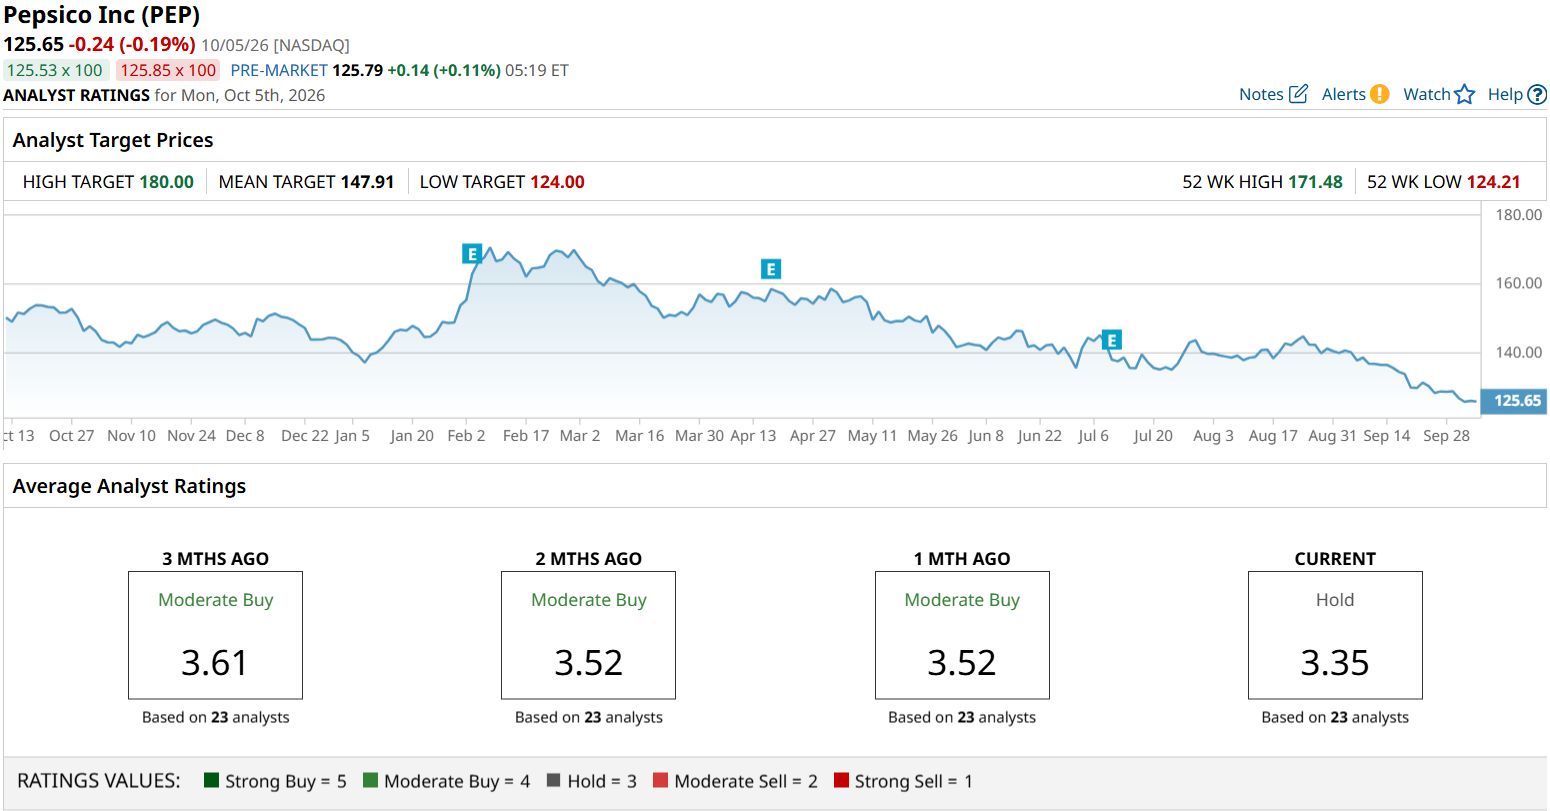
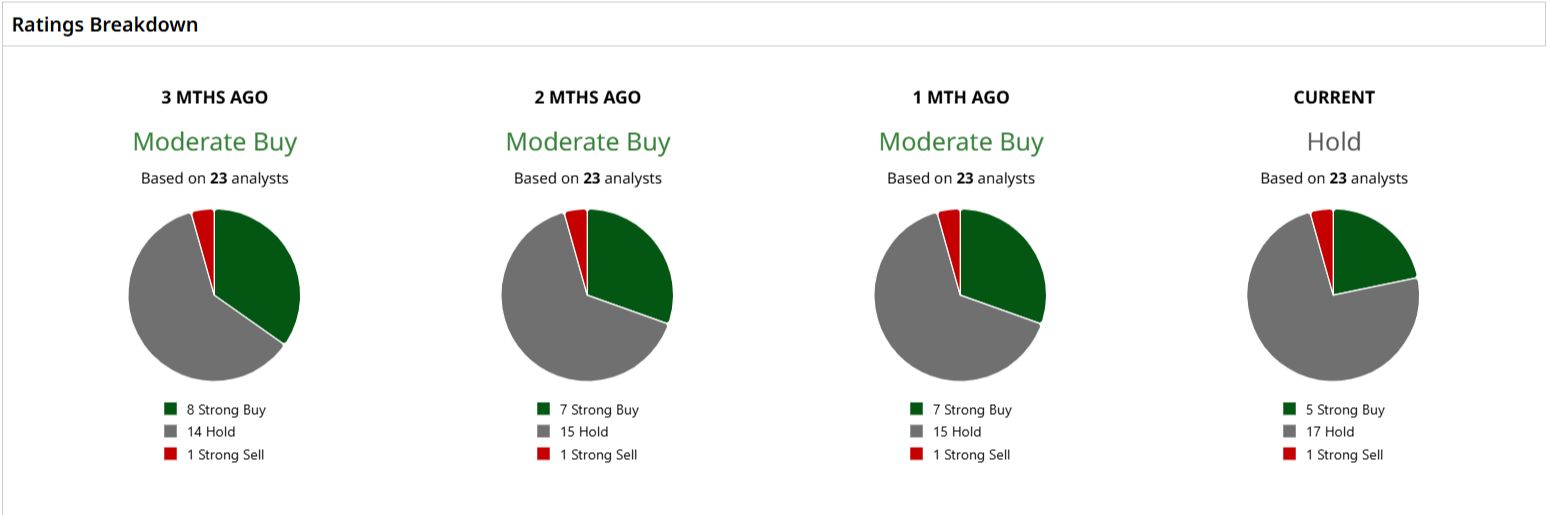
Among the 23 analysts surveyed, PepsiCo has a consensus “Hold” rating. The average price target of $147.91 suggests 17.72% upside from current price levels.
 www.barchart.com
Conclusion
PepsiCo has a path back to stronger growth, but Oct. 8 needs to show that its affordability efforts and newer brands are translating into better demand. The dividend gives shareholders a reason to stay patient, though it cannot substitute for a North American recovery. I think shares are more likely to remain under pressure than stage a lasting rally unless volumes improve and management supports its outlook. A modest earnings beat alone may not be enough. Investors need evidence that PepsiCo can grow sales without sacrificing more of its margins.
On the date of publication, Ebube Jones did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Michael Burry Sees a Government-Backed AI Boom. A Memory-Style Rally Could Be Around the Corner. Nasdaq Futures Slip as Rising Bond Yields Weigh on Chip Stocks, FOMC Minutes on Tap A Juicy Dividend Means Investors Should Stay Patient with Pepsi Stock Before October 8 CRWD Stock Pops as CrowdStrike Launches Fourth Startup Accelerator