

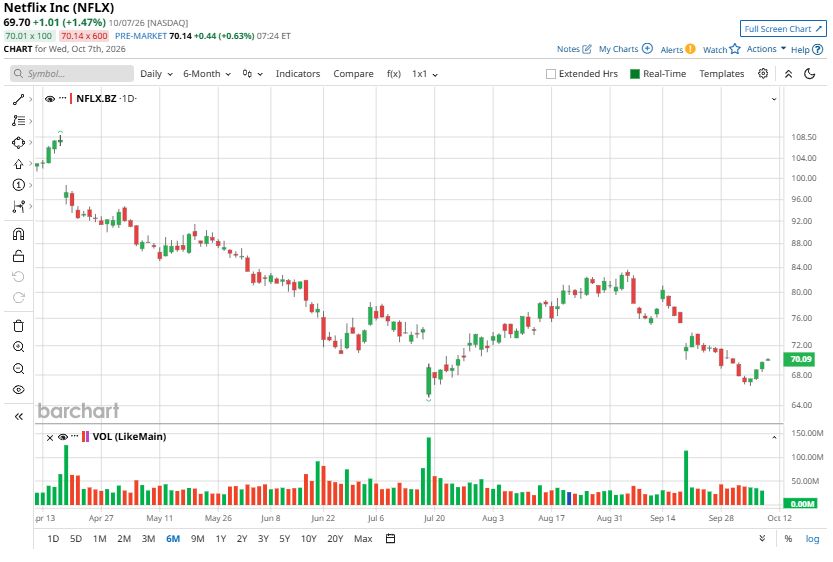
Netflix (NFLX) will release its third-quarter financial results on Tuesday, Oct. 20. Ahead of the announcement, NFLX shares have been under considerable pressure, with the stock down about 26% so far this year and trading more than 44% below its 52-week high.
The recent decline reflects growing concerns about Netflix’s growth prospects and the increasingly competitive streaming market. The company’s third-quarter outlook came in weaker than analysts expected, raising questions about whether revenue and earnings growth could slow in the coming quarters.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Another issue weighing on sentiment is Netflix’s decision to provide engagement data less frequently. Starting in 2027, the company plans to report these metrics once a year instead of twice annually.
Netflix is also facing a tougher growth environment in the second half of the year. The company is going up against strong results from the same period last year, making the year-over-year comparisons more difficult.
 www.barchart.com
Netflix Q3: Here’s What to Expect
Netflix’s third-quarter performance is likely to show a moderation in growth as the company faces challenging year-over-year comparisons and intensifying competition in the streaming market. Even so, Netflix will likely sustain double-digit top-line growth, supported by rising subscription revenue, continued membership growth, and the rapid expansion of its advertising business.
For Q3, Netflix projects revenue of $12.9 billion, an 11.7% increase from the same period last year. The key revenue drivers are expected to remain broadly consistent with those seen in Q2. Subscription revenue should benefit from a larger member base and recent pricing increases, while advertising revenue is expected to provide an additional boost. Netflix continues to report solid trends in subscriber acquisition and retention, and management has indicated that recent price increases are progressing well. Although higher prices should contribute to revenue and profitability, overall revenue growth is expected to slow compared with the previous quarter.
For full-year 2026, Netflix anticipates revenue of roughly $51 billion to $51.4 billion, representing growth of approximately 13%–14%. Subscriber growth and pricing are expected to remain the primary contributors, while advertising is becoming an increasingly meaningful source of monetization. Management is targeting advertising revenue of around $3 billion in 2026, reflecting the company’s efforts to diversify its revenue base beyond subscriptions.
Advertising has become an important component of Netflix’s longer-term growth strategy. The introduction of its ad-supported plan has allowed the company to reach more price-sensitive consumers while adding another revenue stream.
Profitability is also expected to improve. Netflix projects a third-quarter operating margin of 33.2%, up from 28.2% a year ago. At the same time, the company expects content expenses to increase by about 10% in 2026, below its anticipated revenue growth. If this trend continues, the resulting operating leverage could help drive further expansion in margins and earnings.
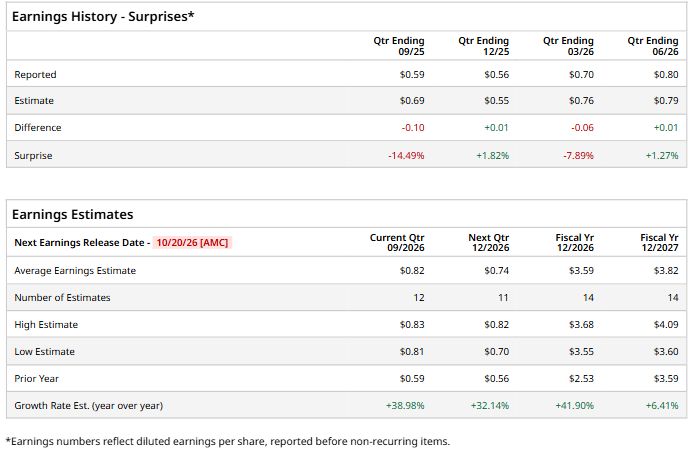
At the earnings level, management is forecasting third-quarter EPS of $0.82, up 39% from the prior-year period. This estimate aligns with Wall Street’s expectations. However, investors should note that Netflix has exceeded analysts’ EPS estimates only twice over the past four quarters, making the company’s ability to meet or surpass expectations an important factor for investors to watch.
 www.barchart.com
The Key Takeaway
Overall, Netflix’s third-quarter results will test whether the company can sustain growth amid tougher comparisons and intensifying competition. While moderating revenue growth could weigh on investor sentiment, continued subscriber growth, the ability to raise prices, strong retention, expanding advertising revenue, and improving operating margins provide a solid foundation for earnings growth.
With the stock already down sharply from its 52-week high, a strong Q3 and an upbeat outlook could boost Netflix stock. Analysts are cautiously optimistic and maintain a “Moderate Buy” consensus rating on NFLX stock ahead of the Q3 earnings release.
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Dear Netflix Stock Fans, Mark Your Calendars for October 20 Shaq Says Seeing 50 People in Elvis Shirts Made Him Ask, ‘How the Hell Is He Still Making Money?’ Then He Invested in the Company That Owns Elvis Dear Wells Fargo Stock Fans, Mark Your Calendars for October 13 Dear ASML Stock Fans, Mark Your Calendars for October 14