

Masco Corporation (MAS), headquartered in Livonia, Michigan, provides home improvement and building products. Valued at $14.7 billion by market cap, the company’s products include faucets, kitchen and bath cabinets, architectural coatings, and builders’ hardware products. Masco sells its products through mass merchandisers, home centers, hardware stores, and other wholesale and retail outlets to consumers and contractors. The branded home improvement and building products leader is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Wednesday, Oct. 28.
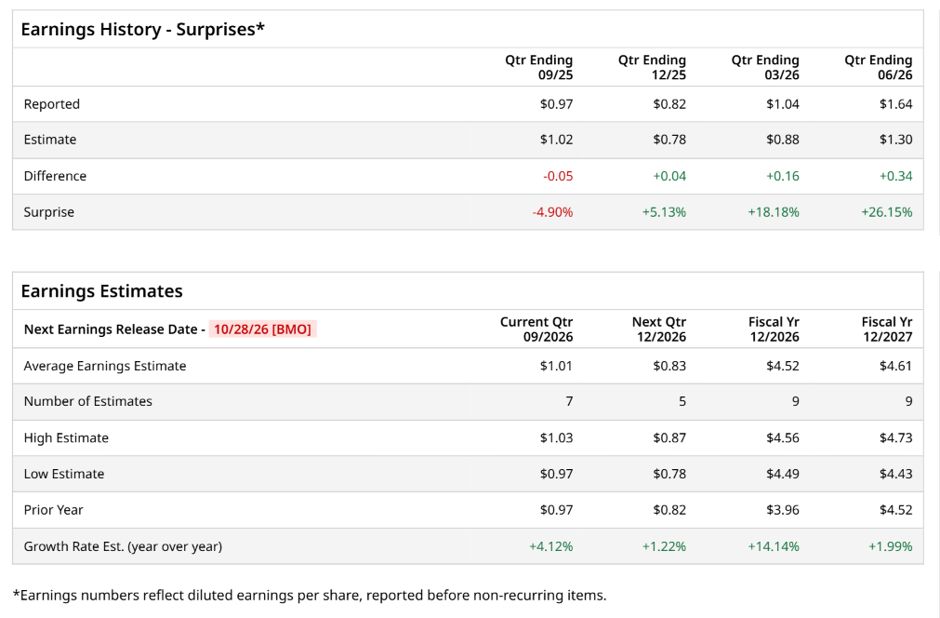
Ahead of the event, analysts expect Masco to report a profit of $1.01 per share on a diluted basis, up 4.1% from $0.97 per share in the year-ago quarter. The company beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For the full year, analysts expect Masco to report EPS of $4.52, up 14.1% from $3.96 in fiscal 2025. Its EPS is expected to rise 2% year over year to $4.61 in fiscal 2027.
 www.barchart.com
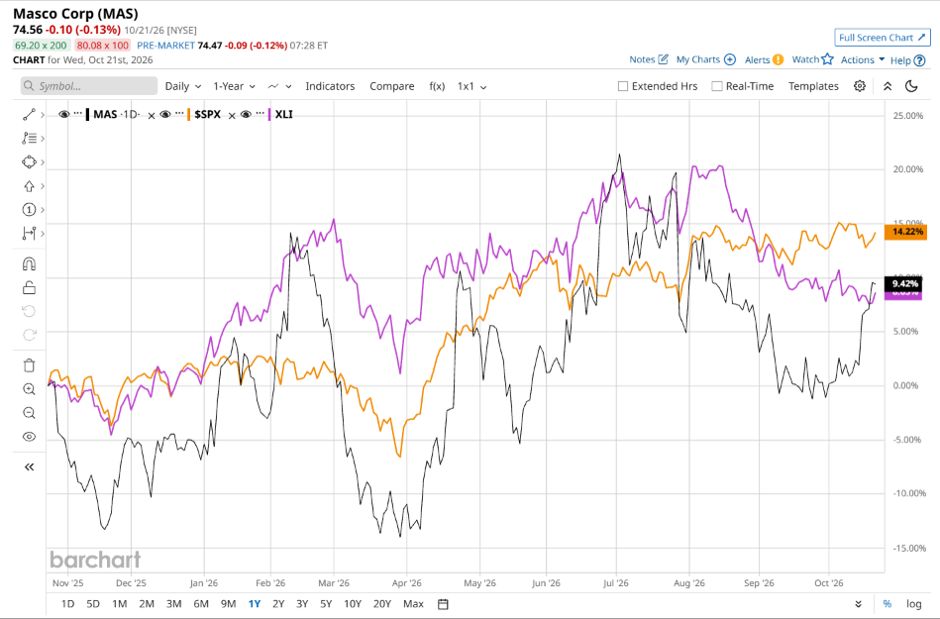
MAS stock has underperformed the S&P 500 Index’s ($SPX) 15.2% gains over the past 52 weeks, with shares up 6.2% during this period. Similarly, it underperformed the State Street Industrial Select Sector SPDR ETF’s (XLI) 8.7% rise over the same time frame.
 www.barchart.com
MAS underperformed as sluggish housing pressured DIY paint demand in its Decorative Architectural segment, while tariffs and commodity costs squeezed margins, leaving shares range-bound despite a $95 million Q2 benefit from IEEPA tariff refunds. Management raised full-year adjusted EPS guidance citing an $85 million full-year net benefit from tariff refunds, per CFO Rick Westenberg, alongside cost savings and restructuring that held Decorative margins steady, plus the Bristan Group UK divestiture to focus on core plumbing, while maintaining low single-digit sales growth expectations despite continued demand softness and macro/geopolitical headwinds.
Analysts’ consensus opinion on MAS stock is moderately bullish, with a “Moderate Buy” rating overall. Out of 23 analysts covering the stock, six advise a “Strong Buy” rating, 16 give a “Hold,” and one recommends a “Moderate Sell.” MAS’ average analyst price target is $79.53, indicating a potential upside of 6.7% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
With Robust Growth, Palantir Stock Is Worth Considering at a Premium EBAY Stock Layoffs: What to Know as eBay Plans Job Cuts for Second Time This Year With Attractive Valuations and Robust Growth, Nvidia Stock Is Positioned to Create Value Google Hits Major Quantum Breakthrough. This Could Be a Game-Changer for GOOGL Stock.