

With a market cap of $29.8 billion, The Kraft Heinz Company (KHC) is one of the world’s largest food and beverage companies, with a portfolio of iconic brands including Heinz, Kraft, Philadelphia, Primal Kitchen, and Lunchables, serving consumers in more than 40 countries. The company focuses on delivering high-quality, affordable food while investing in its brands and capabilities to drive innovation and shape the future of the food industry.
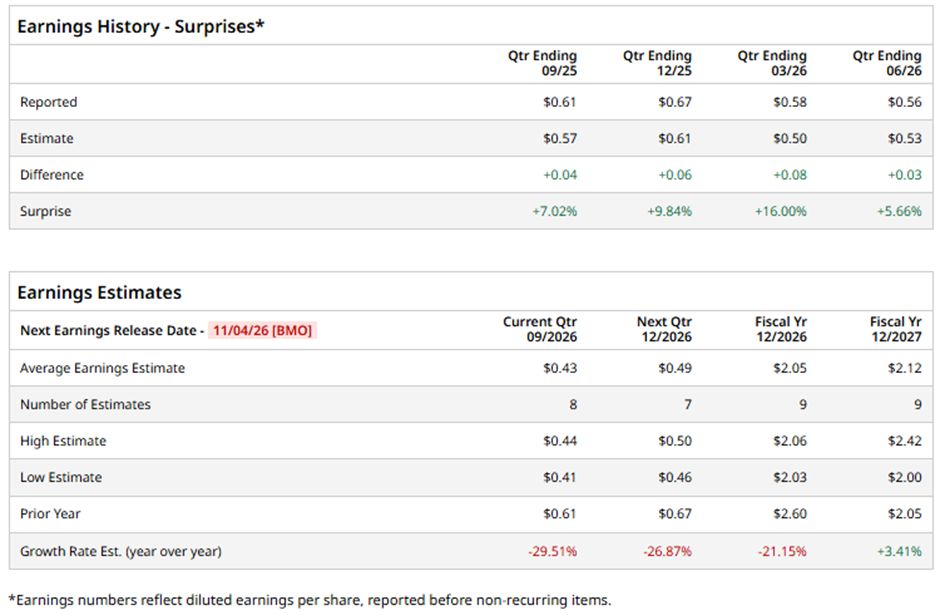
The Pittsburgh, Pennsylvania-based company is expected to release its fiscal Q3 2026 results before the market opens on Wednesday, Nov. 4. Ahead of this event, analysts project the company to report an adjusted EPS of $0.43, a decrease of 29.5% from $0.61 in the year-ago quarter. It has consistently surpassed Wall Street's bottom-line estimates in each of the last four quarterly reports.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For fiscal 2026, analysts forecast the packaged foods giant to post adjusted EPS of $2.05, down 21.2% from $2.60 in fiscal 2025. However, adjusted EPS is anticipated to grow 3.4% year-over-year to $2.12 in fiscal 2027.
 www.barchart.com
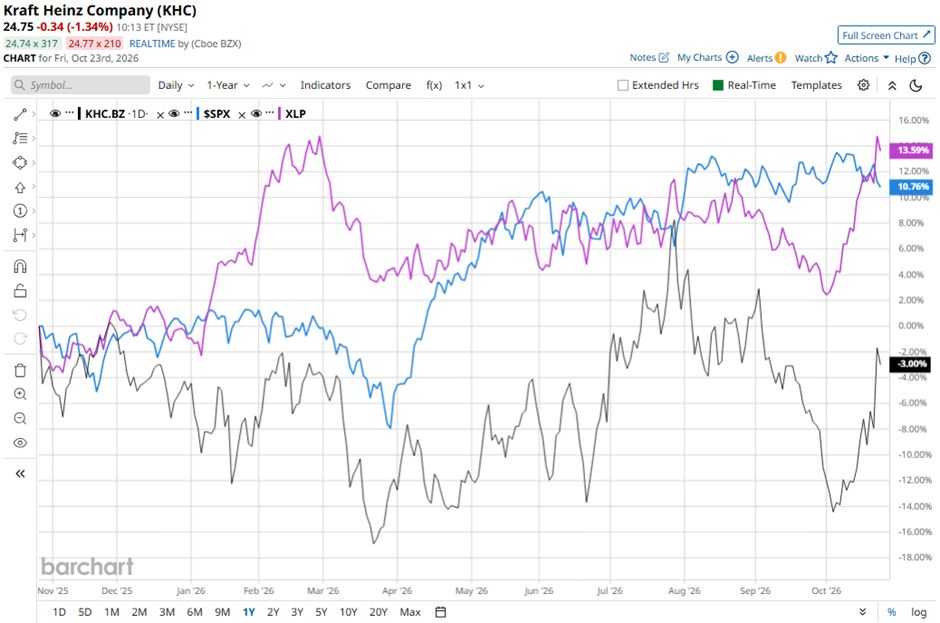
Shares of Kraft Heinz have slipped 1.5% over the past 52 weeks, lagging behind both the S&P 500 Index's ($SPX) 13.3% gain and the State Street Consumer Staples Select Sector SPDR ETF's (XLP) 12.5% return over the same period.
 www.barchart.com
Kraft Heinz shares fell 3.4% on Aug. 5 as Q2 2026 sales declined 1.4% year-over-year to $6.26 billion and volumes remained weak in key markets and North American market share fell in meats and meals. Although the company narrowed its expected organic sales decline to 0.5% - 2% from 1.5% - 3.5% and adjusted EPS guidance to $2.03 - $2.09, it increased 2026 marketing and innovation investments by $100 million to approximately $700 million, putting additional pressure on operating profit guidance, now projected to decline 16%–18%.
Concerns about the turnaround were compounded by expected 4% - 5% inflation in 2027, rising energy and raw-material costs, and a $7.4 billion non-cash impairment charge that contributed to Q2 operating loss.
Analysts' consensus view on KHC stock is cautious, with a "Hold" rating overall. Among 20 analysts covering the stock, one suggests a "Strong Buy," one has a "Moderate Buy," 14 recommend a "Hold," one "Moderate sell," and three "Strong Sells." As of writing, the stock is trading above the average analyst price target of $23.89.
On the date of publication, Sohini Mondal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
How Nvidia Stock Can Make or Break the Anthropic IPO – and the Claude Maker’s Potential $2 Trillion Valuation A $4 Billion Reason to Take Another Look at Supermicro Stock With an IPO Brewing, Anthropic Just Launched Its Answer to Meta’s Uber-Popular Muse Ahead of Verizon Earnings, Here's What Barchart Data Says Comes Next for VZ Stock