

Artificial intelligence (AI) is creating an enormous appetite for electricity, shifting the biggest constraint on expansion from chips to power. The public grid was not designed for demand on this scale, and upgrading it quickly enough is proving difficult. Fermi (FRMI) aims to address this gap with dedicated energy infrastructure built for advanced computing.
The ambition now comes with a sharper focus on financing. On Wednesday, Oct. 21, in a letter to shareholders, CEO Lee McIntire outlined a three-part capital strategy for Project Matador, Fermi’s large-scale power and infrastructure development and AI facility in Texas. The plan centers on funding growth without leaning too heavily on equity.
Don’t Miss a Day: From crude oil to coffee, sign up free for Barchart’s best-in-class commodity analysis.
Fermi’s immediate objective is to “responsibly manage” the equity required for every megawatt of capacity delivered. To do so, the company will prioritize powered land deals for its remaining 2027 capacity and planned 2028 development. It also intends to secure customer funding earlier through development contributions, mobilization payments, and infrastructure funding arrangements.
Alongside these measures, Fermi is pursuing project-level debt and strategic investment partners to help finance development. Over the medium term, McIntire wants to build relationships with institutional infrastructure investors for construction financing and project equity. Eventually, the company hopes to use cash flows from completed projects to fund future development through a self-sustaining infrastructure platform.
Thus, let us take a closer look at the company’s fundamentals to see whether the revised strategy can strengthen its financial position and improve the outlook for FRMI stock.
About Fermi Stock
Fermi develops next-generation private electric grids designed to deliver reliable, gigawatt-scale power for AI and advanced computing. Based in Amarillo, Texas, the company is developing Project Matador, a 17 GW energy campus combining natural gas, nuclear, utility grid power, solar, and battery storage to meet the demanding needs of hyperscale computing.
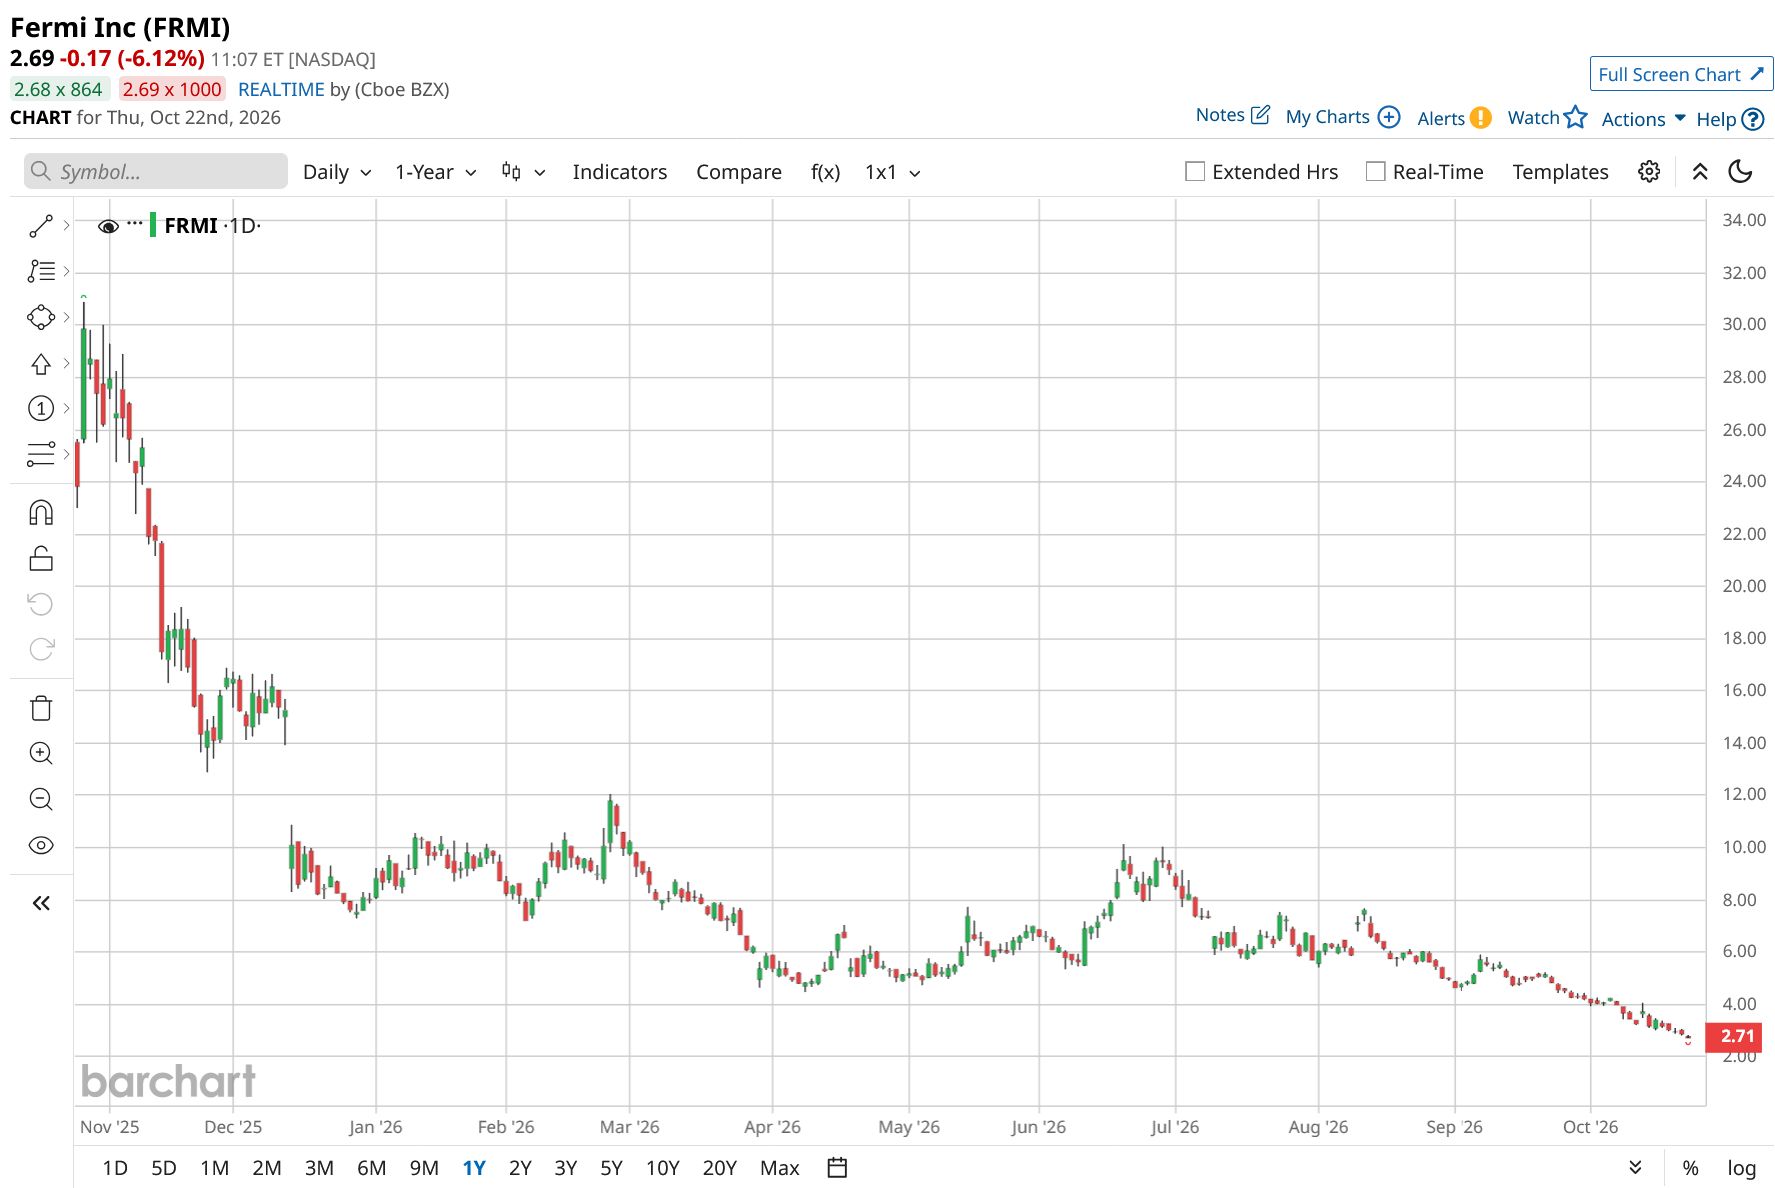
Despite the scale of that ambition, Fermi’s stock-market debut has been followed by a steep slide. The company commands a market cap of approximately $1.8 billion, yet its shares have fallen 86% over the past 52 weeks. FRMI stock has also declined 66% year-to-date (YTD), including a 46% plunge over the past month alone.
Yet, the decline has not made the stock inexpensive by any measure. FRMI stock is currently trading at 42.79 times sales, a premium to the industry average.
 www.barchart.com
A Closer Look at Q2 Earnings
On Aug. 13, Fermi reported its Q2 FY2026 financial results, bringing Project Matador closer to commercial execution even as the company’s results reflected its pre-revenue status. Net loss widened 310.3% year-over-year (YoY) to $25.8 million. Meanwhile, loss per share was $0.04, up 100% YoY, mainly due to $26.8 million in general and administrative expenses.
The quarter’s standout development was Fermi’s agreement with TensorWave, its first anchor customer, under a binding 15-year lease. The initial commitment covers 222 MW and represents approximately $6.5 billion in potential contract revenue over the lease term.
Fermi also made tangible progress on the infrastructure needed to support those commitments. The company received three Siemens (SIEGY) F-class turbines, bringing its landed power assets to 1.5 GW. Partnerships with Hillcore, Primoris Services Corporation (PRIM), and TSK are intended to accelerate generation capacity while limiting direct capital requirements for Hillcore’s proposed 2.6 GW facility.
The financial statements reveal why funding remains central to that progress. Fermi invested $185 million in property, plant, and equipment during the quarter, taking the gross balance to approximately $1.55 billion. Cash and restricted cash stood at $91.7 million against $520.1 million in outstanding debt, highlighting the substantial capital needed to advance the project.
A subsequent $431 million convertible-note offering provided additional liquidity, giving Fermi more resources to pursue its development plans. In the quarter, management also established ambitious operational milestones, targeting approximately 200 MW of initial commercial power within six months and 1.5 GW within 18–24 months.
Analyst forecasts suggest the earnings outlook could improve over time, although the near-term picture remains uneven. Q3 FY2026 EPS is expected to grow significantly YoY. For full FY2026, however, the loss per share is forecasted to widen 100% from the previous year to $0.33, while for FY2027, EPS is projected to grow 193.9% to $0.31.
What Do Analysts Expect for FRMI Stock?
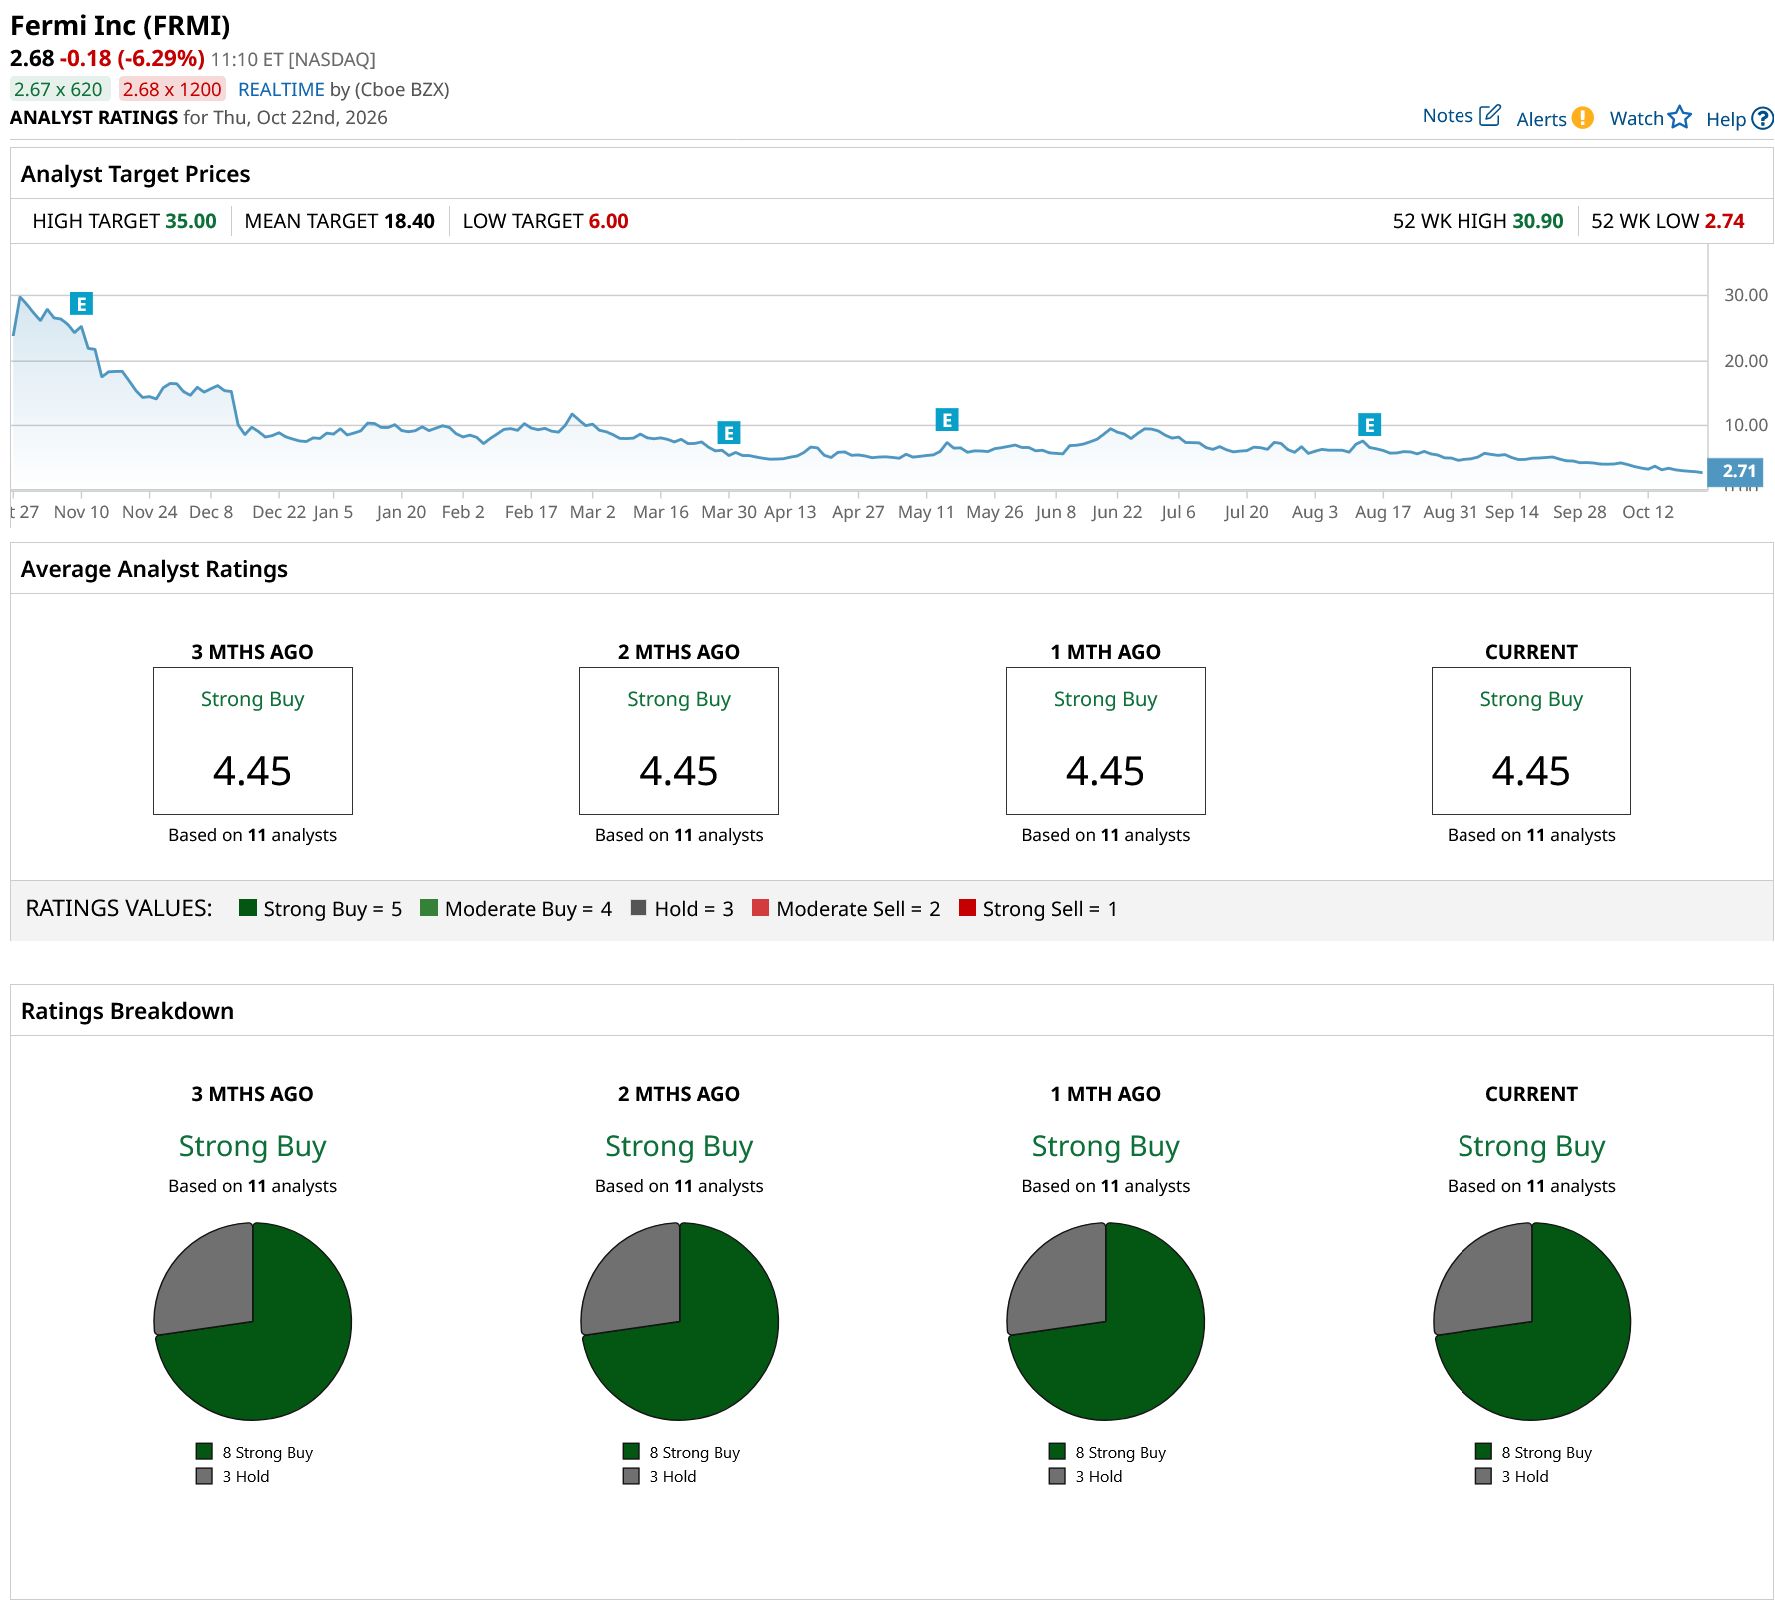
Despite the sharp losses in Fermi’s shares, Wall Street remains optimistic about the company’s prospects. Analysts covering FRMI stock have assigned it an overall “Strong Buy” rating, with eight of the 11 analysts recommending a “Strong Buy” and the remaining three opting for a “Hold.”
To that end, the average price target is $18.40, representing potential upside of 586%. At the upper end, the Street-high target of $35 suggests a gain of 1,206% from current levels.
 www.barchart.com
On the date of publication, Aanchal Sugandh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Fermi Has a New Plan for Growing Its Data Center Business. What That Means for FRMI Stock. ‘I Don’t Want You to Contribute to a Trump Account for a Child. Period’: Suze Orman Says Take the Free $1,000 and Your Employer’s $2,500, Then Stop. Microsoft May Be the Only Hyperscaler to Stay Cash-Flow Positive. What It Means for MSFT Stock Nvidia vs. Broadcom: One Grew AI Revenue 221% Last Quarter. The Other Grew 117%.