

Columbus, Indiana-based Cummins Inc. (CMI) designs, manufactures, distributes, and services diesel and natural gas engines, electric and hybrid powertrains, and related components worldwide. Valued at $71.2 billion by market cap, the company offers products to original equipment manufacturers (OEMs), distributors, and dealers through a network of company-owned and independent distributor facilities. The global power solutions leader is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Thursday, Nov. 5.
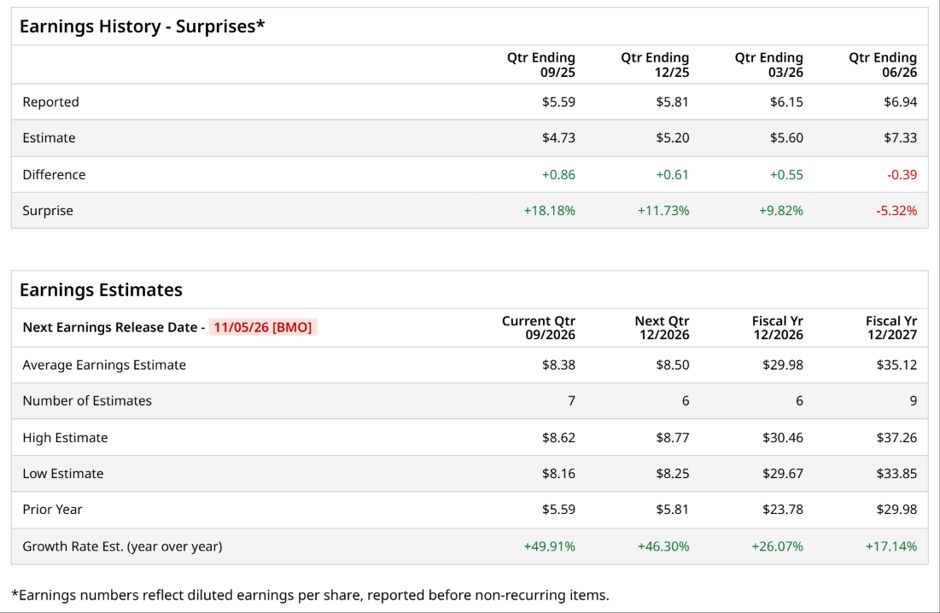
Ahead of the event, analysts expect Cummins to report a profit of $8.38 per share on a diluted basis, up 49.9% from $5.59 per share in the year-ago quarter. The company beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For the full year, analysts expect Cummins to report EPS of $29.98, up 26.1% from $23.78 in fiscal 2025. Its EPS is expected to rise 17.1% year over year to $35.12 in fiscal 2027.
 www.barchart.com
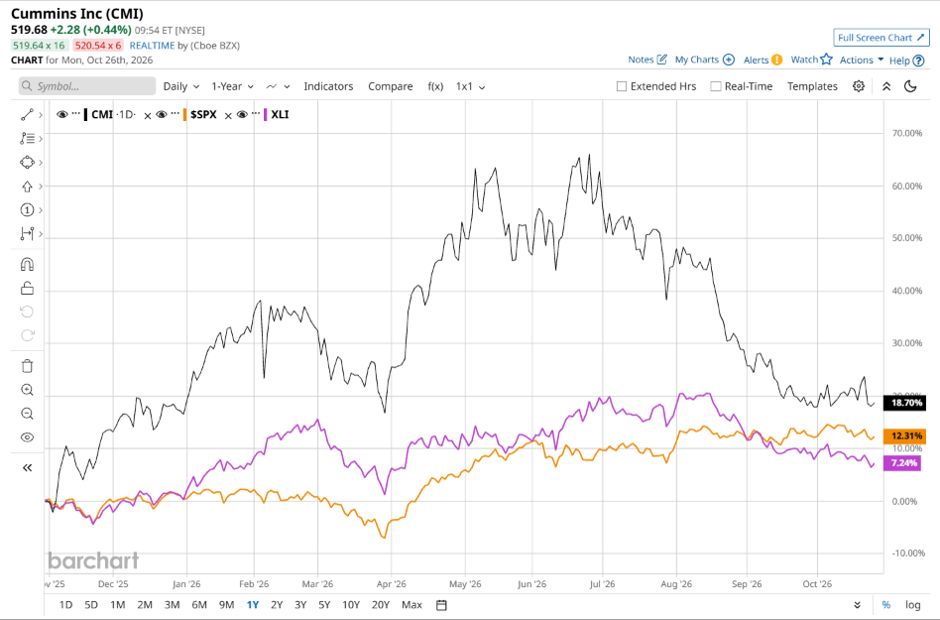
CMI stock has outperformed the S&P 500 Index’s ($SPX) 13.1% gains over the past 52 weeks, with shares up 23.8% during this period. Similarly, it outperformed the State Street Industrial Select Sector SPDR ETF’s (XLI) 6.4% gains over the same time frame.
 www.barchart.com
Cummins delivered strong outperformance, driven by surging demand for power-generation equipment from global data centers, international construction, and recovering on- and off-highway markets in China. CEO Jennifer Rumsey highlighted a major multiyear supply agreement with a hyperscaler and expanded plant capacity, prompting an upgraded full-year revenue growth outlook of 10% to 13% for 2026. Additionally, clarity on upcoming EPA emissions regulations will allow a smoother, staggered engine rollout through 2027. While profitability was partially tempered by tariffs and higher variable compensation from record earnings projections, management's strategic investments in power systems and new platforms position the company for continued growth.
Analysts’ consensus opinion on CMI stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 19 analysts covering the stock, 10 advise a “Strong Buy” rating, one suggests a “Moderate Buy,” and eight give a “Hold.” CMI’s average analyst price target is $704, indicating a notable potential upside of 36.1% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.