

Cerebras Systems (CBRS), the company behind some of the world's fastest artificial intelligence (AI) infrastructure, has found itself navigating a particularly turbulent stretch. Its stock has taken several hits in recent months, with the first major setback arriving as the post-IPO lockup period approached its end.
Adding to the pressure, on Wednesday, Oct. 28, Culper Research disclosed a short position in Cerebras, questioning the durability of its wafer-scale chips and claiming they last just 1.5 to 2.5 years in real-world operating conditions. That estimate falls short of the 3-to-5-year lifespan Cerebras projected in its April S-1 filing, which itself marked an increase from earlier estimates of 1.5 to 3 years.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Yet, the recent setbacks have not come without a few encouraging developments. Cerebras announced a partnership with Oracle Corporation (ORCL) on Tuesday, Oct. 27, although the news did little to halt the stock's downward slide. Under the agreement, the two companies plan to bring Cerebras' AI inference technology to Oracle Cloud Infrastructure (OCI).
The company has also offered investors a more encouraging revenue outlook. Cerebras recently raised its 2026 core revenue forecast to $880 million to $890 million, compared with its earlier projection of $855 million to $865 million. The upward revision provides a positive counterpoint to the concerns weighing on its shares.
Against this backdrop, Thursday, Nov. 12, is shaping up to be an important date for Cerebras. The company is scheduled to release its Q3 FY2026 financial results after the market closes, giving shareholders a fresh opportunity to assess its operating performance, financial health, and the road ahead for the stock.
About Cerebras Stock
Headquartered in Sunnyvale, California, Cerebras Systems operates in the fast-growing AI infrastructure space, designing and manufacturing advanced computing systems and software for data centers and supercomputers. Its proprietary wafer-scale technology powers high-performance computing across several applications, including AI inference, generative AI, and other demanding workloads.
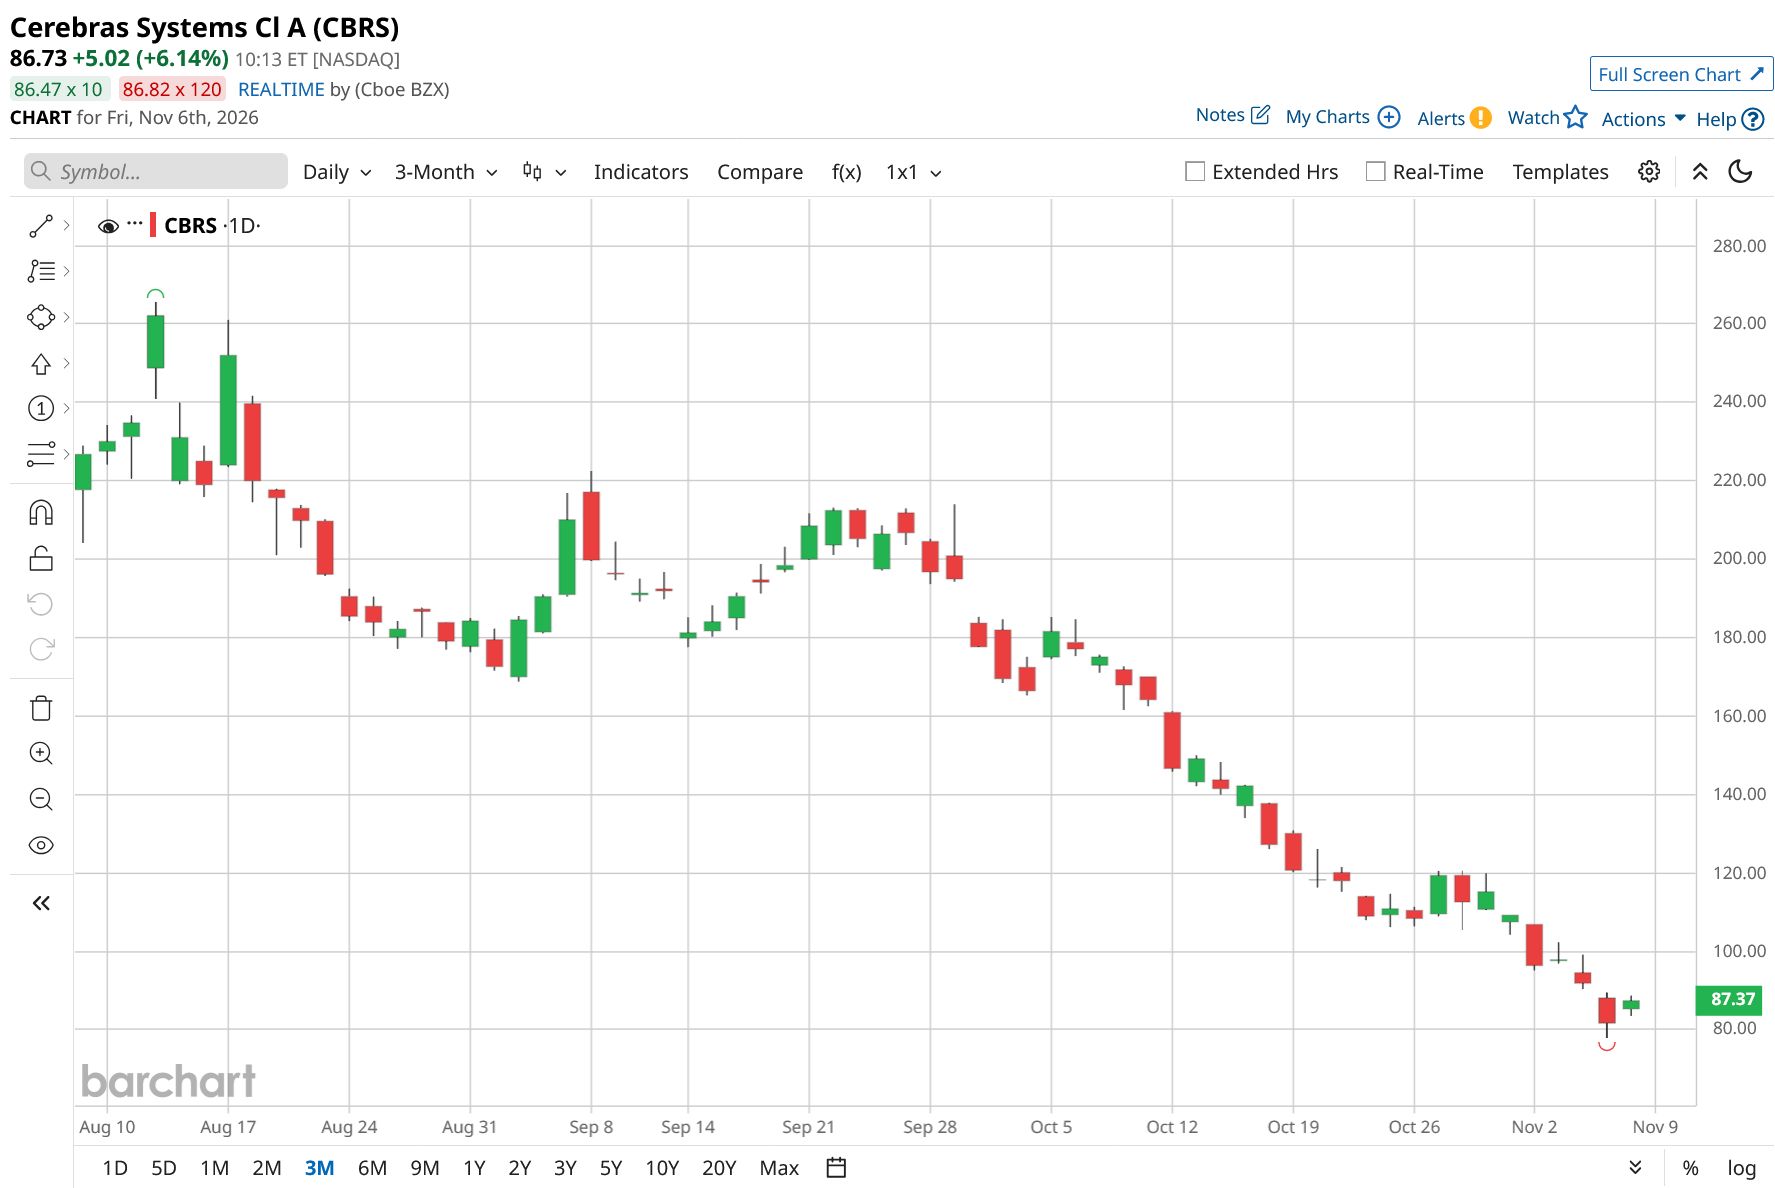
The company serves global enterprises, hyperscalers, and AI research organizations, supporting a market cap of nearly $21.8 billion. However, that sizeable valuation has offered little protection against the recent selloff. Cerebras’ shares have fallen 58% over the past three months, with losses reaching 19% in just the past five days. Despite the losses, Friday morning's trading has, for now, helped stem some of that bleeding on the price chart.
 www.barchart.com
The stock's valuation adds another dimension to the investment debate. CBRS stock is currently trading at 24.59 times sales, a multiple that exceeds the industry average. The premium indicates investors are placing considerable value on Cerebras' growth potential, even as recent market activity has raised questions about its near-term prospects.
A Closer Look at Q2 Earnings
On Aug. 12, CBRS stock climbed 11.6% as the company released its Q2 FY2026 results. Revenue rose 74.3% year-over-year (YoY) to $180.1 million, beating Street estimates and highlighting strong demand across its expanding AI infrastructure business.
Much of that growth came from stronger customer consumption, additional dedicated cloud capacity, and rising demand for AI inference services. Cloud and other services emerged as the standout contributor, with revenue jumping 281.5% YoY to $126 million and accounting for 70% of the company's total quarterly revenue.
Hardware, meanwhile, delivered a less encouraging result, with revenue down 23% YoY, primarily due to $28 million in non-cash customer warrant amortization. Higher sales under existing arrangements helped cushion the hardware segment's decline but did not fully offset the pressure.
Even so, Cerebras' underlying profitability metrics offered a constructive picture. Non-GAAP core gross profit surged 163.9% YoY to $85.2 million, while core operating loss narrowed 23.4% YoY to $33.6 million. Core net loss also improved 83% YoY to $6.9 million.
Meanwhile, loss per share came in at $2.98, compared with an EPS of $1.91 in the corresponding period last year. It also topped analyst expectations. Looking ahead, the earnings outlook remains mixed. For Q3 FY2026, analysts expect loss per share to widen 100% YoY to $0.13. The projected loss per share for full-year FY2026 is also expected to widen 100.1% from the previous year to $0.52.
The longer-term forecast, however, offers a more optimistic counterpoint. For FY2027, analysts expect EPS to grow 338.5% YoY to $1.24, suggesting a stronger earnings trajectory remains in the picture despite the near-term profitability challenges.
What Do Analysts Expect for CBRS Stock?
Despite the sharp correction in Cerebras’ shares, analyst opinion has not turned overwhelmingly bearish. UBS recently lowered its price target to $250 from $330 while retaining its “Buy” rating, indicating a more cautious approach to valuation rather than a fundamental loss of confidence in the company's business prospects.
Barclays has also maintained a constructive stance. Analyst Thomas O'Malley reiterated his “Buy” rating and $280 price target. His outlook suggests that the company's technological capabilities remain an important part of its longer-term investment appeal.
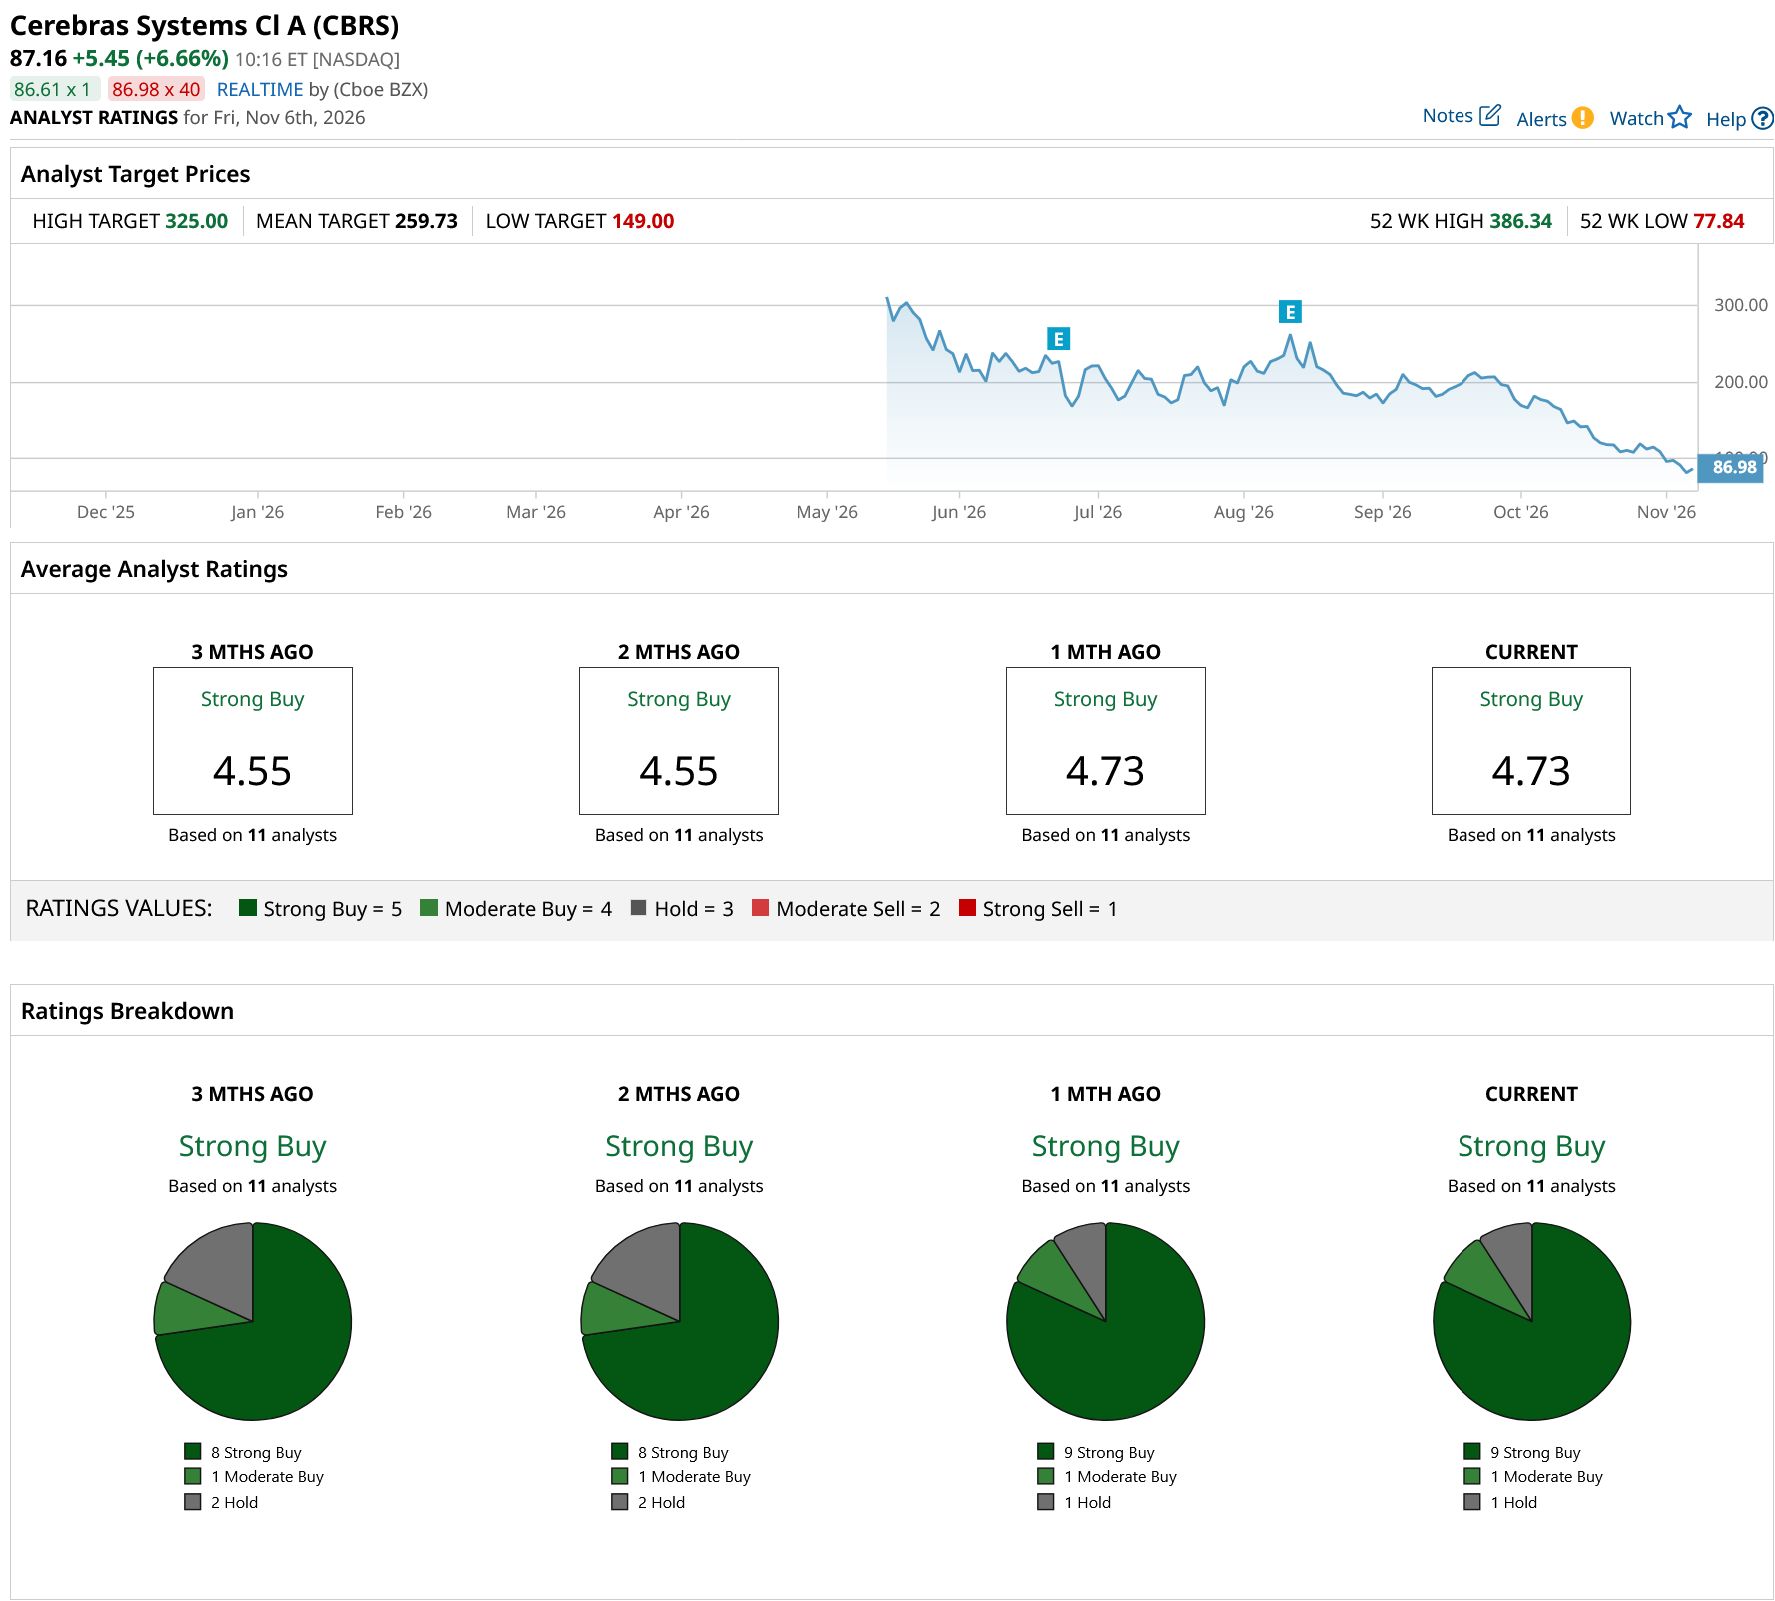
Wall Street's broader verdict on CBRS stock is a “Strong Buy.” Among 11 analysts currently tracking the shares, nine recommend a “Strong Buy,” one has assigned a “Moderate Buy” rating, and one advises investors to “Hold.”
To that end, the average price target of $259.73 represents a potential upside of 199%. Meanwhile, the Street-high target of $325 points to a possible gain of 274% from current levels.
 www.barchart.com
On the date of publication, Aanchal Sugandh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Why You Shouldn’t Buy the Dip in Tesla Stock Dear Cerebras Stock Fans, Mark Your Calendars for November 12 Dear Cerebras Stock Fans, Mark Your Calendars for November 9 Ahead of Skydance Earnings, Here's What Barchart Data Says Comes Next for SKYD Stock