

Valued at $89.1 billion by market cap, Howmet Aerospace Inc. (HWM) is a leading manufacturer of advanced engineered metal products for the aerospace, defense, and commercial transportation industries. Headquartered in Pittsburgh, Pennsylvania, the company specializes in producing high-performance components made from nickel, titanium, aluminum, and other specialty materials. Its products include jet engine components, aerospace fastening systems, titanium and aluminum structural parts, and forged aluminum wheels for heavy-duty trucks.
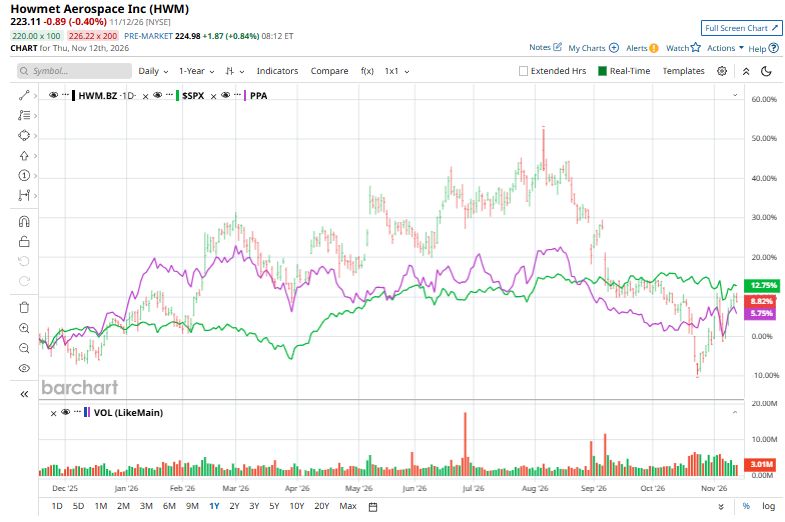
Shares of this engineered metal products leader have outperformed the broader market over the past year. HWM has gained 8.8% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10.8%. Over the past six months, the stock has declined 17.3%, trailing the SPX’s 2.6% rise.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Zooming in further, HWM has outpaced the Invesco Aerospace & Defense ETF (PPA), which has gained 3.5% over the past year.
 www.barchart.com
On Oct. 29, Howmet shares popped 5.5% after the company delivered a strong Q3 2026 performance, supported by accelerating commercial aerospace production, robust gas turbine demand, and expanding profitability. Revenue surged 29.4% year-over-year to $2.70 billion, while adjusted EPS climbed 53.7% to $1.46, beating the benefits of higher production volumes, favorable pricing, and a stronger product mix.
Adjusted EBITDA rose 33.1% to $879 million, with margins expanding to 32.5%. Engine Products led segment growth, with revenue increasing 33% to $1.45 billion. Looking ahead, management raised its full-year 2026 guidance and projected approximately 12% revenue growth in 2027, reflecting sustained demand across commercial aerospace, defense, and industrial gas turbine markets.
For the current fiscal year, ending in December, analysts expect HWM’s EPS to grow 45.6% to $5.49 on a diluted basis. The company’s earnings surprise history is solid. It beat the consensus estimate in each of the last four quarters.
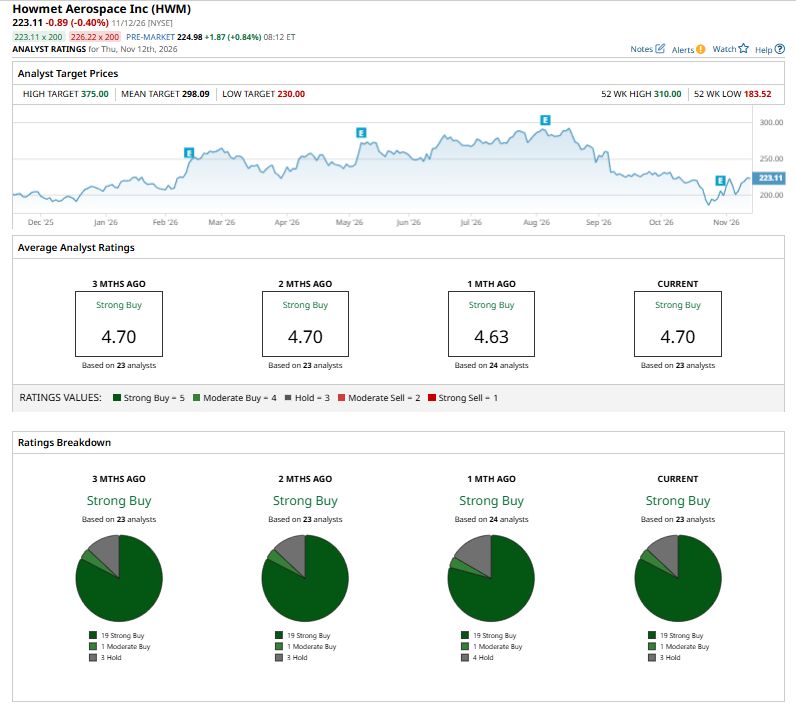
Among the 23 analysts covering HWM stock, the consensus is a “Strong Buy.” That’s based on 19 “Strong Buy” ratings, one “Moderate Buy,” and three “Holds.”
 www.barchart.com
The configuration has been consistent over the past three months.
On Nov. 3, BTIG lowered its price target on Howmet Aerospace to $280 from $340 while maintaining a “Buy” rating. The firm remains optimistic about the company's growth prospects, citing strong demand across commercial aerospace, defense, and industrial gas turbine markets. Howmet expects industrial gas turbine sales to reach approximately $2 billion by 2028 and $2.5 billion by 2030. Management also projected approximately 12% revenue growth in 2027, supported by rising aircraft production, defense demand, and sold-out capacity as new production comes online.
The mean price target of $298.09 represents a 33.6% premium to HWM’s current price levels. The Street-high price target of $375 suggests an upside potential of 68.1%.
On the date of publication, Kritika Sarmah did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
How to Play AMD Stock as Google Picks EPYC for Its Next-Gen TPUs ‘SaaSpocalypse’ Fears Hit Microsoft Stock Again. Don’t Rush to Buy the Dip. S&P 500 Futures Gain With Focus on U.S. PPI Data and Fed Speak Dear Costco Stock Fans, Mark Your Calendars for December 4