

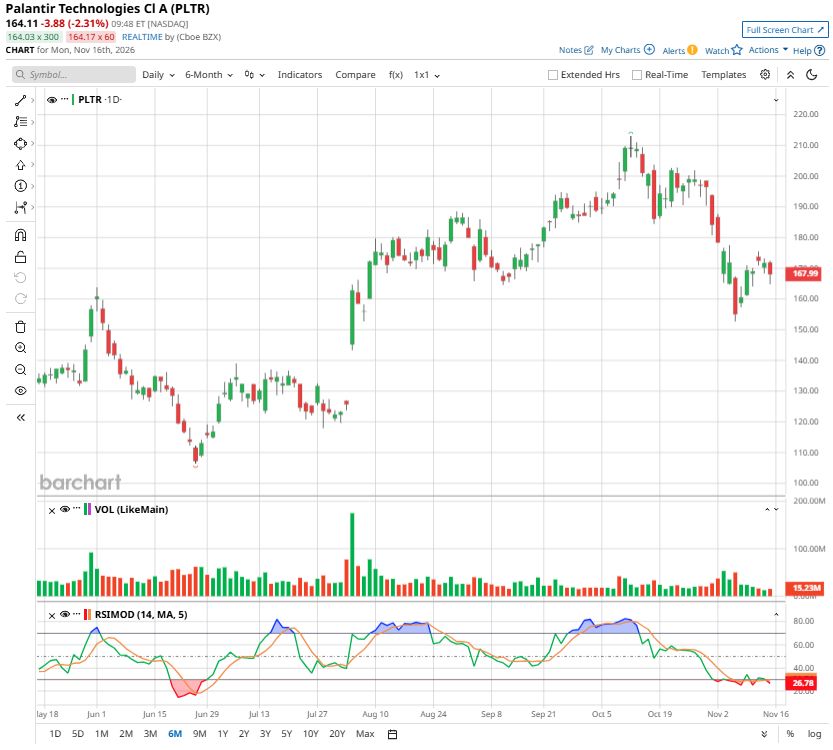
Palantir Technologies (PLTR) stock has declined more than 19% over the past month and is trading approximately 21% below its 52-week high. While the pullback reflects near-term valuation concerns and weak market sentiment toward AI-related stocks, it offers a buying opportunity for long-term investors, as PLTR’s growth trajectory remains solid.
Palantir's outlook remains solid, led by strong demand across its U.S. commercial and government businesses. The acceleration in the adoption of its Artificial Intelligence Platform (AIP) is strengthening its competitive positioning, driving enterprise customer engagement, and creating opportunities for sustained revenue expansion. Additionally, growing demand for Sovereign AI solutions could unlock a significant new growth avenue as governments and institutions increasingly prioritize secure, domestically controlled AI infrastructure.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Taken together, these growth drivers position Palantir to deliver solid revenue and earnings growth in the long term.
 www.barchart.com
Palantir’s Accelerating AIP Adoption Sets Stage for Solid Growth
Palantir’s accelerating AIP adoption sets the stage for solid growth ahead. Its latest quarterly financial numbers suggest that this momentum could continue. Palantir reported a 96% year-over-year increase in revenue, with its U.S. business once again recording solid growth.
PLTR’s domestic business revenue grew 119% year over year to $1.94 billion, highlighting strong demand in its largest market. Moreover, the acceleration in commercial activity suggests solid growth ahead.
U.S. commercial revenue stands out as the strongest growth driver. It surged 148% year over year to $984 million. U.S. commercial revenue led government revenue for the first time, supporting a more balanced revenue mix.
Customer growth and contract activity also support continued expansion. Palantir's U.S. commercial customer base increased 29% year over year to 686, indicating that adoption is spreading across a wider range of businesses. Meanwhile, commercial revenue grew 113% to $1.17 billion. Palantir secured $1.65 billion in commercial total contract value (TCV) bookings during the quarter, while U.S. commercial bookings reached $1.46 billion.
Another important growth opportunity lies in the emerging sovereign AI market. During the quarter, Palantir secured multiple eight-figure contracts as organizations accelerated their adoption of initial Sovereign AI capabilities. Although these agreements were shorter than the company’s typical contracts, management expects their size and duration to increase as customers expand deployments and realize additional value from the technology. This creates an opportunity for Palantir to deepen existing relationships and generate larger, longer-term contracts as sovereign AI adoption matures.
In addition, the upward revision in financial outlook reflects that the current momentum will carry forward. Palantir now expects full-year 2026 U.S. commercial revenue to exceed $3.56 billion, implying growth of at least 143%. Earlier, Palantir projected U.S. commercial revenue growth of at least 134%.
Its full-year revenue guidance midpoint has also increased to $8.53 billion, up from $8.15 billion, representing 91% year-over-year growth. The upward revision suggests that management expects enterprise AI demand to remain strong.
Other indicators also strengthen the growth outlook. Net dollar retention reached 165%, up 800 basis points from the previous quarter, suggesting existing customers are expanding their use of Palantir's products. Total remaining deal value stood at $13.4 billion, up 55% year over year, while remaining performance obligations increased 88% to $4.9 billion.
Overall, Palantir is expected to benefit from strong enterprise AI adoption. The acceleration in U.S. commercial revenue, growing customer numbers, higher contract commitments, and Sovereign AI opportunity suggest solid growth ahead.
Palantir’s Growth Momentum Makes the Pullback Worth Buying
The pullback in Palantir stock offers a compelling opportunity for long-term investors, supported by accelerating AIP adoption, strong U.S. commercial growth, and expanding demand for Sovereign AI solutions.
The upward revision in revenue guidance, rising customer commitments, and robust net dollar retention strengthen its growth outlook.
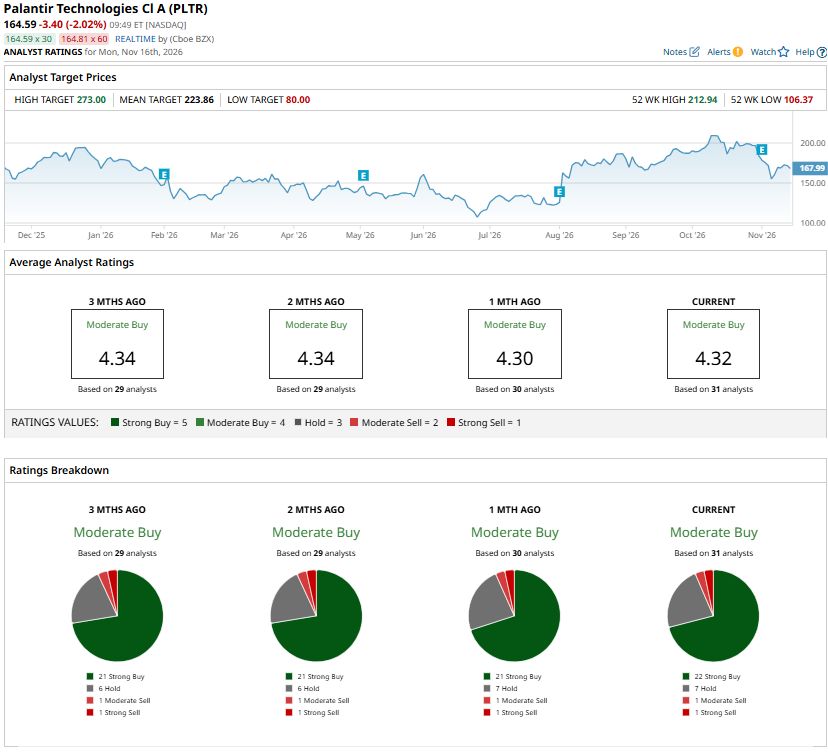
While analysts maintain a “Moderate Buy” consensus rating due to valuation concerns, Palantir’s strong business momentum and expanding AI opportunities support the bullish long-term investment thesis.
 www.barchart.com
On the date of publication, Sneha Nahata did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Shorting ConocoPhillips Puts and Put Credit Spreads Are Attractive Income Plays The $70 Million Reason Cathie Wood Can't Stop Buying Rocket Lab Stock What is the 2027 Outlook for the Grains Sector? Why You Should Buy the Pullback in Palantir Stock Now