

For most of this year, investors have remained worried that artificial intelligence (AI) will make traditional software less necessary. The fear has been so strong that it has even earned a nickname: the "SaaSpocalypse.”
ServiceNow (NOW) and Salesforce (CRM) are two of the biggest business software companies, so both stocks have understandably been hit hard in 2026. Earlier this year, Salesforce CEO Marc Benioff declared that "the software bears are dead wrong." Apart from AI, these two firms also have an interesting battle going on against each other. ServiceNow has been moving into Salesforce's territory since launching its own AI-powered CRM platform, while Salesforce has been moving into ServiceNow's turf with its own IT service product built around Slack.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
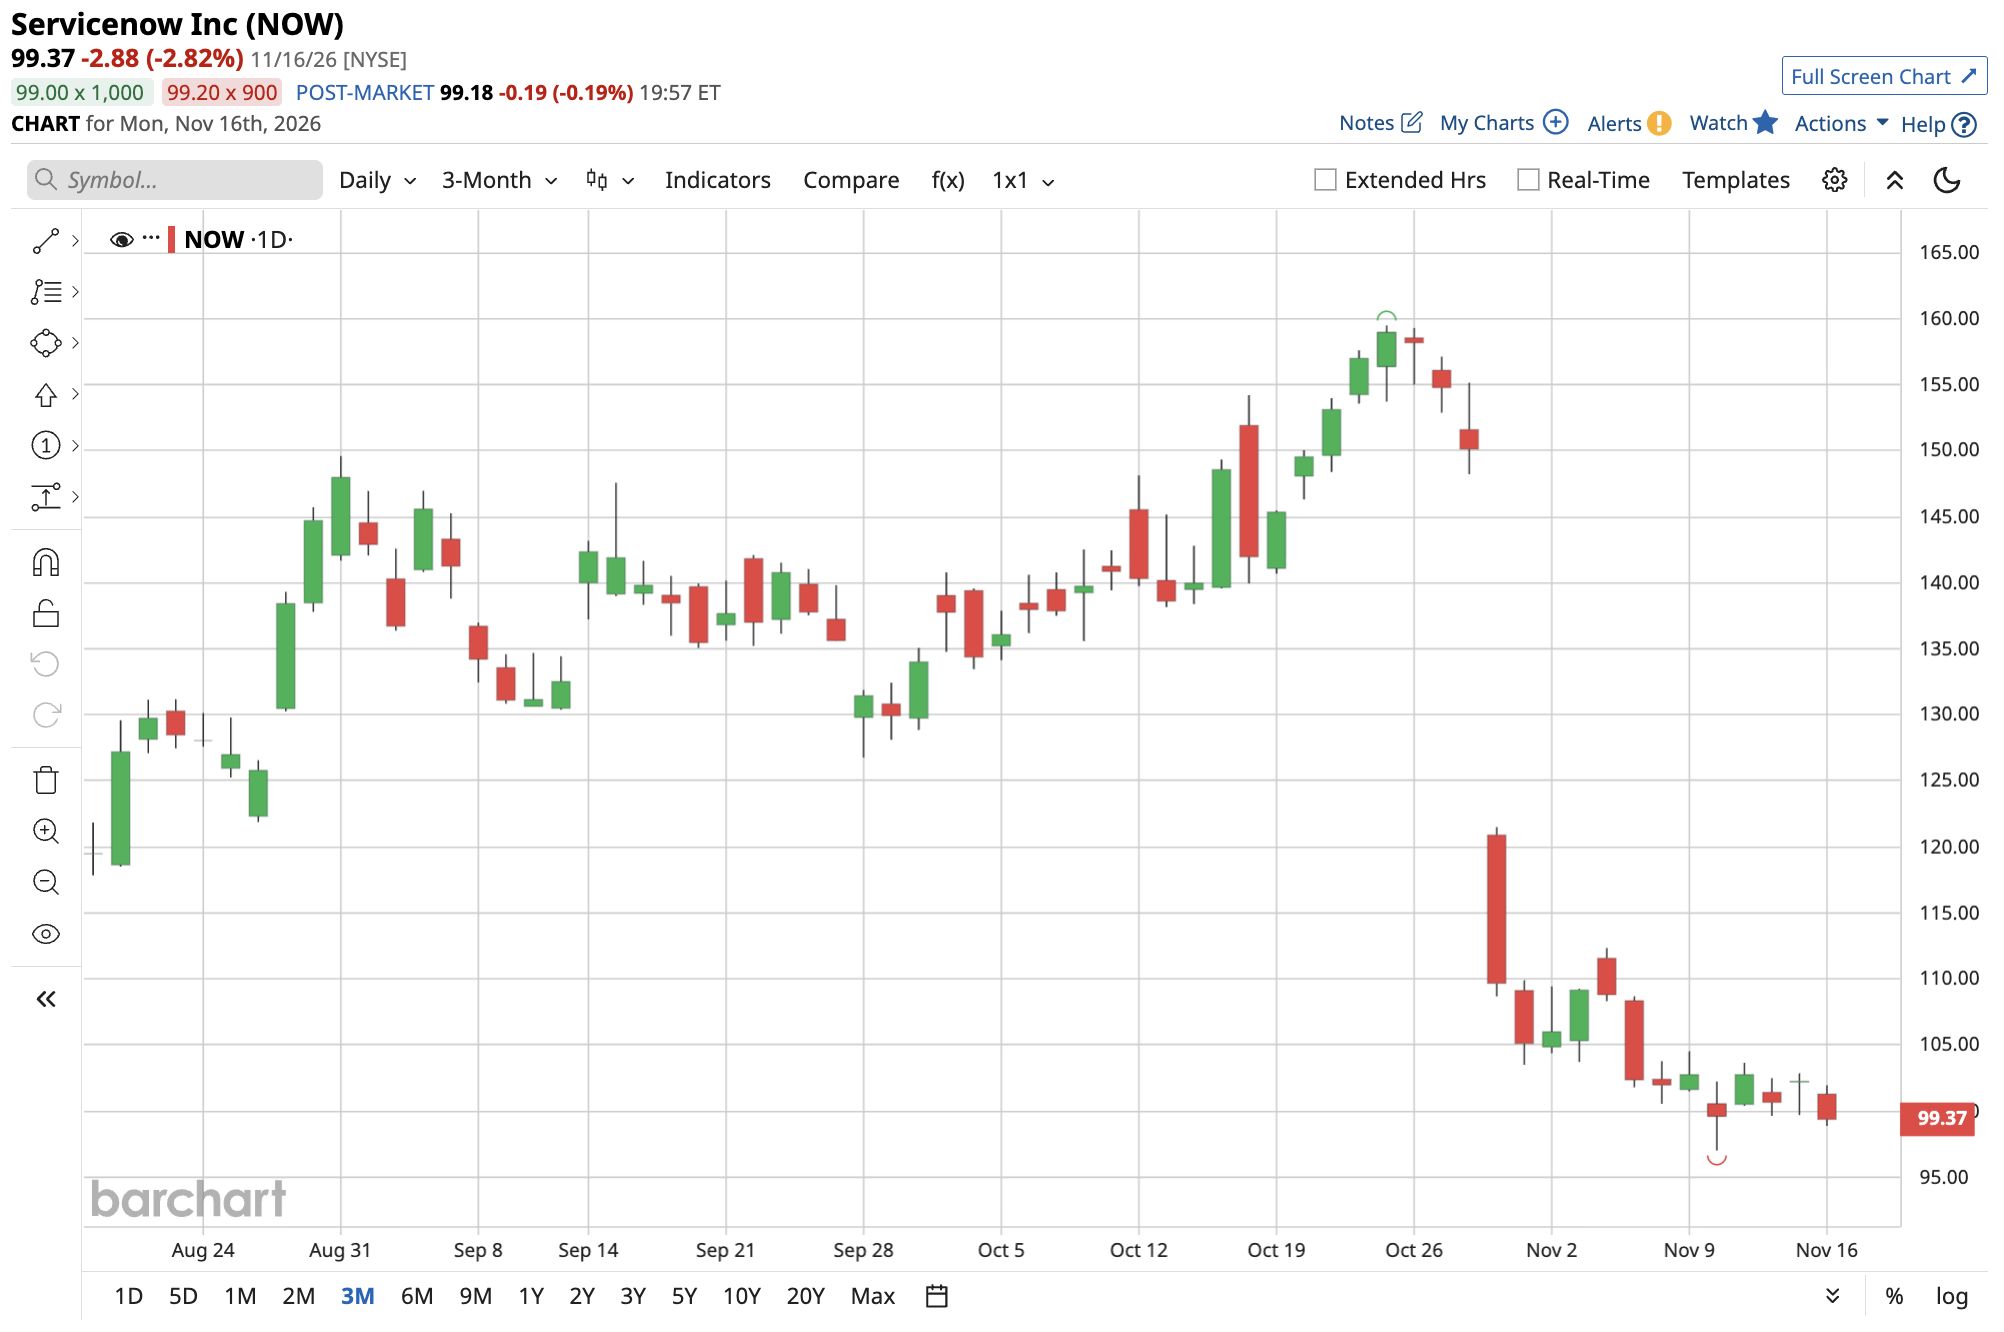
ServiceNow reported third-quarter earnings on Oct. 28, beating revenue expectations. Total revenue grew 20.5% year-over-year (YOY) to $4.11 billion, while cRPO also grew 20.5% to $13.65 billion. CEO Bill McDermott said it wasn't just a normal beat-and-raise quarter, but an inflection point for ServiceNow. Yet NOW stock crashed 27% in the session after earnings, its worst day ever. Investors focused on backlog growth, which management guided to slow to 18.5%. The company also slightly missed adjusted EPS expectations. The selloff even dragged down Salesforce with it.
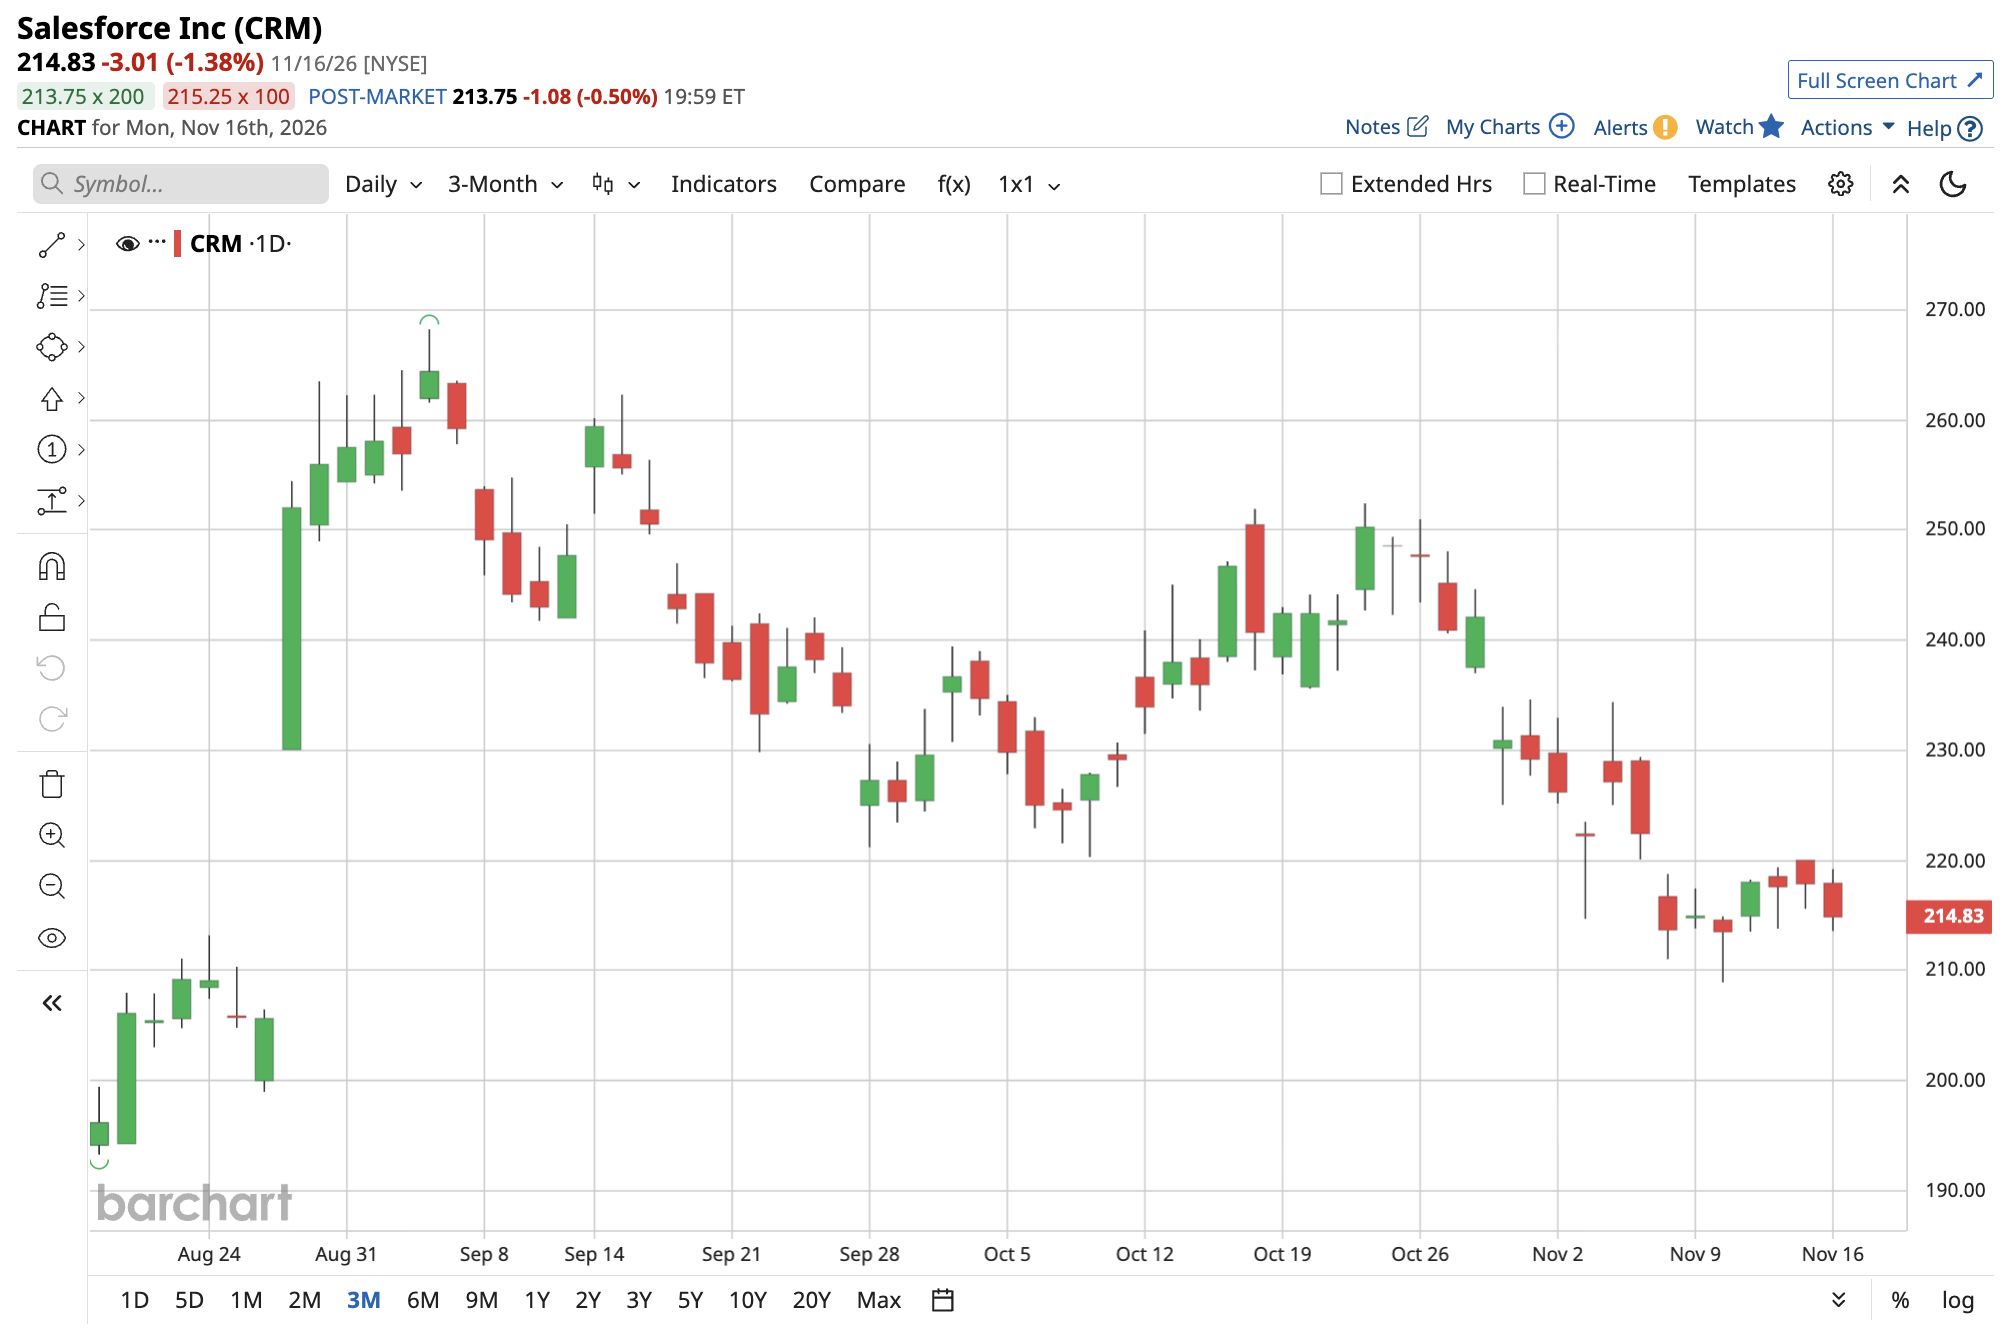
For Salesforce, revenue grew 11% YOY to $11.35 billion in its fiscal second quarter, helped by the Informatica acquisition, while cRPO grew 14%. As I previously covered after the Q2 report, a big reason for the headline profit beat was a $2.6 billion gain tied to the company's Anthropic (ANT) stake, so the core business wasn't as strong as it looked on paper. Meanwhile, one genuine positive for Salesforce has been Agentforce, its AI agent product. Agentforce is the fastest-growing product in Salesforce's history, reaching $1.5 billion in annual recurring revenue (ARR) as of Q2. Still, investors should keep an eye on rising acquisition debt and buybacks, which recently led S&P to cut Salesforce to an “A” credit rating.
Salesforce Is Cheaper, ServiceNow Is Better Value
Both stocks currently trade well below their historical averages. ServiceNow's forward price-to-earnings (P/E) ratio of 46.8 times sits below its five-year average of around 55 times. Similarly, its price-to-sales (P/S) ratio of 7.7 times comes in below its average of roughly 13 times. That is a steep discount on both measures.
Salesforce looks even cheaper, with a forward P/E of 16.7 times, which is well below its average of about 28 times. Its P/S ratio of 4.2 times also comes in below its roughly 6 times average, as well as below ServiceNow's multiple.
The EPS outlook somewhat explains the gap. Analysts expect ServiceNow's earnings to grow about 8% in fiscal 2026 and 28% in fiscal 2027. Salesforce's earnings are expected to jump 32% this fiscal year but dip about 10% next year, partly because this year's numbers have gotten a boost from investment gains. ServiceNow also has the cleaner balance sheet, while Salesforce carries far more debt from acquisitions.
Overall, Salesforce is the cheaper stock. But I think ServiceNow offers the better mix of growth and value right now, especially since NOW stock has dropped roughly 37% in the past month alone.
About ServiceNow and Salesforce
ServiceNow started out helping companies run their IT departments and has grown into a platform that uses AI to automate work across entire businesses, including sales and customer service. Founded in 2004, the company is headquartered in Santa Clara, California, and led by chairman and CEO Bill McDermott.
Salesforce is the world's biggest name in customer relationship management (CRM) software and is pushing deeper into AI with Agentforce. Founded in 1999, it is headquartered in San Francisco, California, and led by co-founder, chairman, and CEO Marc Benioff.
Both stocks have been punished worse than the broader iShares Expanded Tech-Software Sector ETF (IGV), which has dipped 8% this year. On a year-to-date (YTD) basis, ServiceNow is down about 41% as well as down 48% from its 52-week high. Most of that drop came after the Q3 earnings report spooked investors about slowing cRPO. Meanwhile, Salesforce stock has also had a weak year. CRM stock is down 29% YTD, as AI fears have weighed on software stocks all year. The selloff after ServiceNow's results added to the decline, helping push CRM stock down roughly 22% in just the past month.
 www.barchart.com
 www.barchart.com
What Do Analysts Expect for ServiceNow Stock and Salesforce Stock?
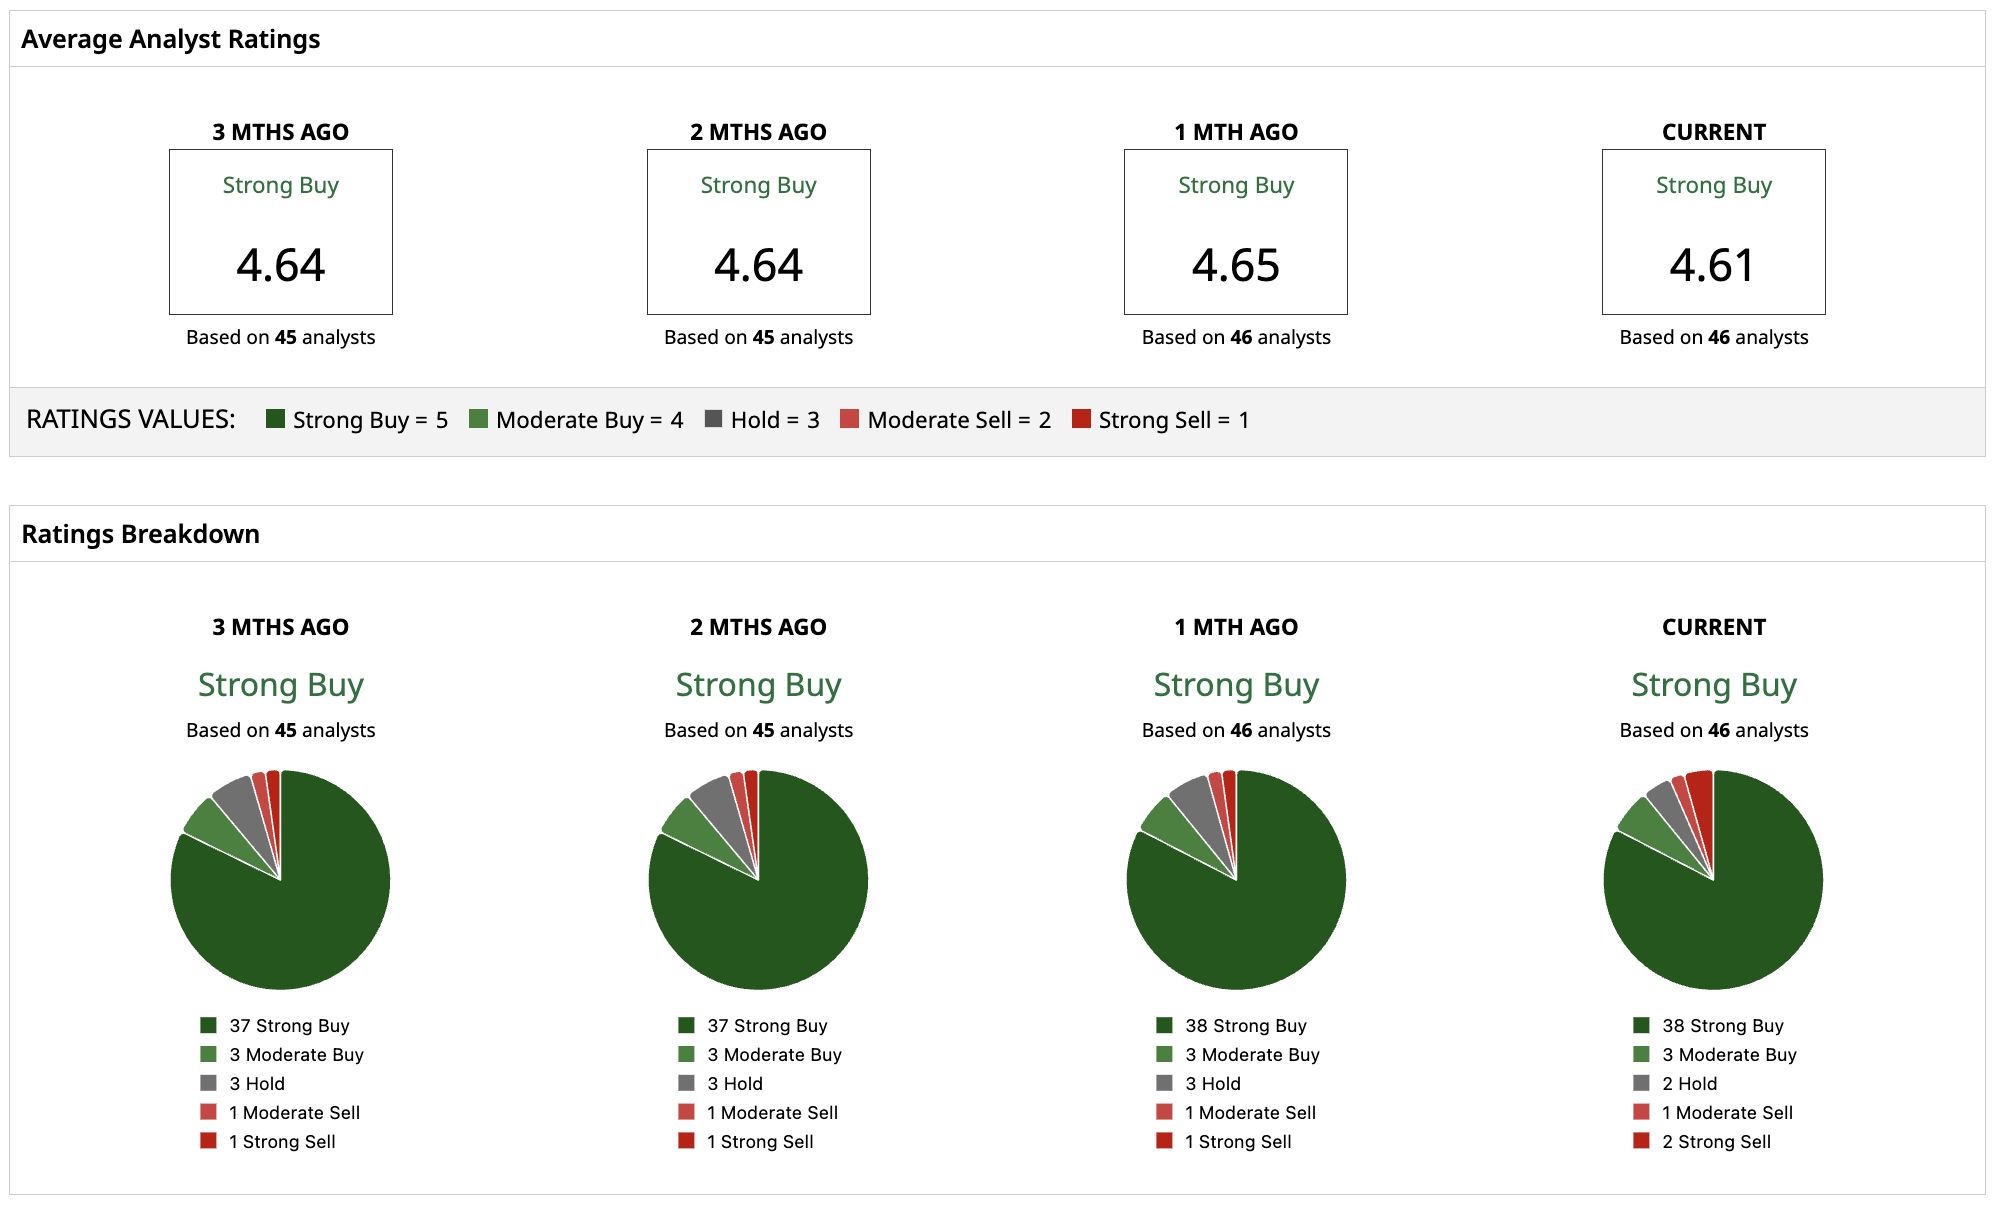
Based on 46 Wall Street analysts with coverage, ServiceNow stock holds a consensus “Strong Buy” rating. The mean price target of $160.15 indicates potential upside of 76% from current levels.
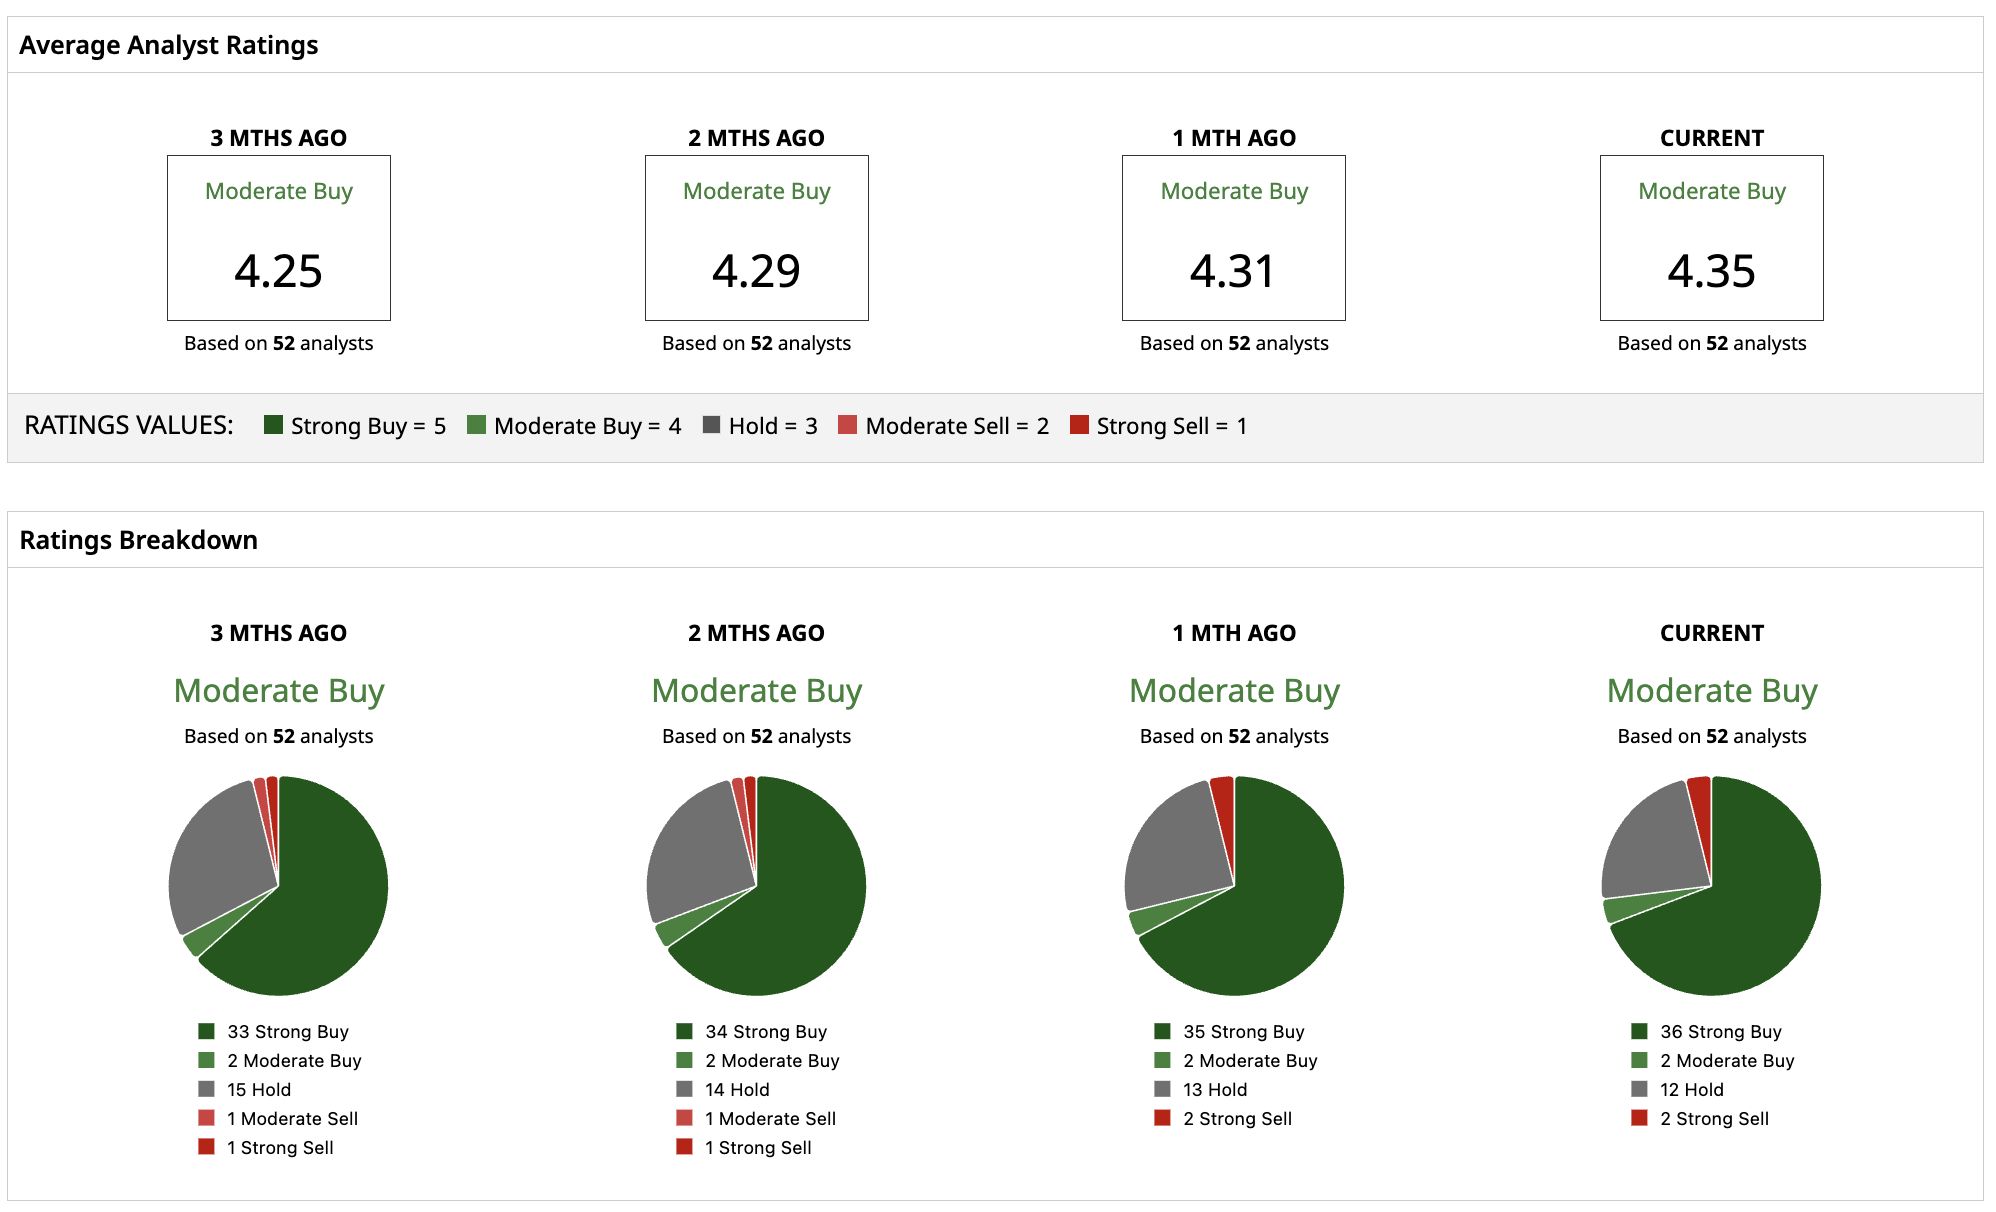
In comparison, Salesforce stock holds a consensus “Moderate Buy” rating based on the 52 analysts with coverage. Its mean price target of $286.88 indicates potential upside of 51% from current share price levels.
 www.barchart.com
 www.barchart.com
On the date of publication, Jabran Kundi did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Palo Alto Networks (PANW) Stock Gains as AI-Driven Cyberattacks Take Center Stage Don't Miss This Generational Investing Opportunity Because You're Too Addicted to Stocks ‘The Software Bears Are Dead Wrong,’ Says Marc Benioff. Why ServiceNow Stock Looks Like the Better Buy Than Salesforce. I Used This Options Strategy to Profit from the Post-IPO Plunge in SpaceX. Now I’ll Use It Again on ANT Stock After Anthropic Starts Trading.