

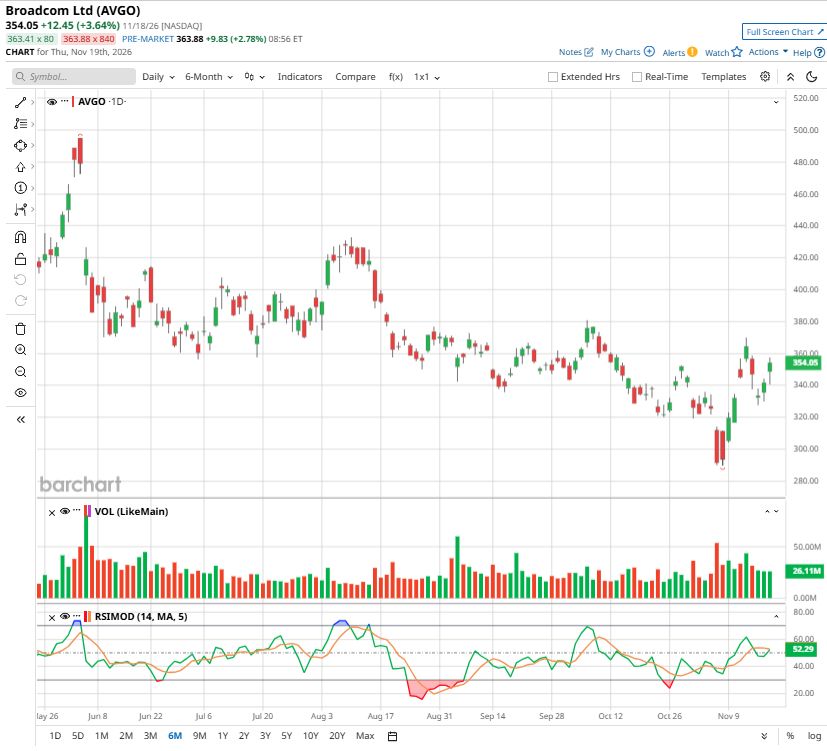
Broadcom (AVGO) shares have pulled back sharply, giving up most of their gains for the year. The decline comes amid a broader selloff in artificial intelligence (AI) stocks, margin pressure, and growing concerns that competition in the custom AI chip market is heating up.
Marvell Technology’s (MRVL) partnership with Alphabet’s (GOOG) (GOOGL) Google to develop custom AI chips has added to these concerns. However, the competitive threat to Broadcom may be getting more attention than it deserves. The bigger picture is that Broadcom is witnessing growing adoption of its custom AI accelerators, or XPUs, among its customers. Moreover, Broadcom is projecting solid growth for XPUs.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
While its gross margins are expected to remain under pressure from the growing share of AI revenue in overall sales, solid operating leverage will continue to drive its earnings.
With its long-term growth outlook still intact, the recent pullback presents a buying opportunity for investors. The lower share price has also made Broadcom’s valuation more appealing, strengthening its investment appeal.
 www.barchart.com
Broadcom’s Growth Trajectory Remains Exceptionally Strong
Broadcom continues to deliver impressive growth, and its momentum is expected to strengthen further in Q4 and beyond. Strong demand for custom AI accelerators, AI networking solutions, and enterprise AI infrastructure is positioning the company for significant growth.
Broadcom reported Q3 revenue of $29.6 billion, up 86% year-over-year (YoY). This represents a sharp acceleration from 29% growth in Q1 and 48% in Q2. The biggest contributor to its accelerating growth is its AI semiconductor business, which grew 221% YoY and 54% sequentially in Q3.
Within AI semiconductors, its custom AI silicon business is growing rapidly. Its six XPU customers are rapidly expanding the deployment of their own AI accelerators, driving a substantial increase in demand.
AI semiconductor revenue exceeded $16.7 billion in Q3, more than tripling from the previous year. XPU shipments increased more than 3.5 times, accounting for approximately 73% of AI semiconductor revenue. Meanwhile, AI networking revenue grew more than 2.5 times, highlighting strong demand across the broader AI infrastructure ecosystem.
The outlook is even stronger. Broadcom expects Q4 AI revenue to reach $21.7 billion, up 236% YoY, driven by higher accelerator shipments for Anthropic (ANT), Google, OpenAI, and Meta (META). Both XPU and AI networking revenue are expected to triple YoY.
As a result, management has raised its FY26 AI revenue expectations to approximately $58 billion, representing 186% growth and exceeding its earlier outlook.
More importantly, management's longer-term projections suggest that Broadcom's AI opportunity is still in its early stages. The company expects AI revenue to double to $115 billion in FY27 and reach $230 billion in FY28. Broadcom has secured the supply needed to support these targets.
Alongside solid top-line growth, Broadcom's profitability is also expanding. In Q3, operating income increased 92% YoY, outpacing revenue growth despite some pressure from changes in business mix. The earnings opportunity is equally significant. Management expects Broadcom to generate more than $30 in EPS by FY28, reflecting significant growth ahead.
Non-AI Businesses Continue to Provide Support
Beyond AI, non-AI semiconductor revenue is expected to support Broadcom’s overall growth, led by demand in broadband and server storage. Its Infrastructure software revenue reached $8.8 billion in Q3, up 29% YoY, while annual recurring revenue (ARR) grew 15%.
VMware is also expanding Broadcom's opportunity in enterprise AI, which will likely support its growth.
Q4 Outlook Points to Further Acceleration
Broadcom expects Q4 FY26 revenue to reach $34.8 billion, up 93% YoY, with an operating margin of approximately 66%.
This guidance suggests growth is not slowing. Instead, accelerating demand for custom AI accelerators and networking solutions is expected to drive another significant step up in revenue.
Broadcom Stock Appears Attractive on Valuation
Broadcom’s current valuation appears compelling relative to its robust earnings growth outlook. AVGO stock trades at 19.3 times forward earnings, which is low considering the company’s strong earnings growth potential.
Analysts project Broadcom’s EPS to increase by 70% in FY27 to $17.31. Furthermore, management’s revenue outlook for FY28 points to EPS exceeding $30, implying roughly 73% YoY growth compared with analyst estimates for FY27.
Overall, AVGO’s strong projected earnings growth and a relatively low forward valuation suggest investors should consider buying the pullback.
AVGO Stock Is a Buy on Pullback
AVGO stock's recent pullback offers an attractive entry point, given its accelerating AI revenue, led by expanding XPU business. It is also expected to deliver solid earnings growth over the next couple of years.
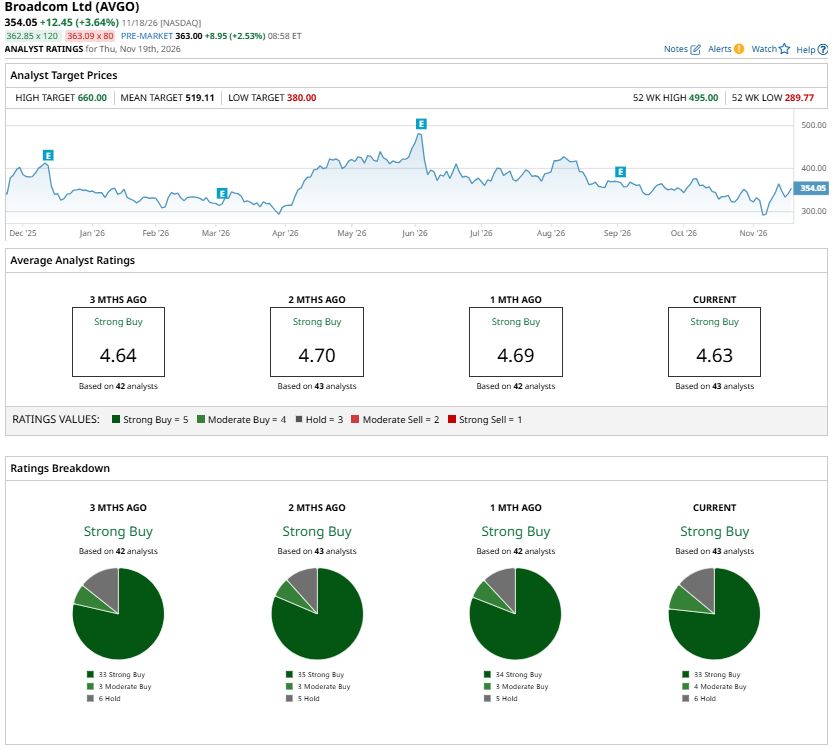
Wall Street is bullish on AVGO's prospects, as reflected in its “Strong Buy” consensus rating and $519.11 average price target.
 www.barchart.com
On the date of publication, Sneha Nahata did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Why It’s Time to Buy the Pullback in Broadcom Stock These Are the Top 10 Largest IPOs Following Anthropic's Historic Market Debut Nvidia Has a New Problem, And It’s Not What You Think A $150 Billion Reason to Buy the Nvidia Stock Dip