

Axcelis Technologies, Inc. ACLS is moving toward renewed growth as memory, power and aftermarket demand improve. Management's outlook points to a stronger revenue trajectory through 2027.
The challenge is valuation. ACLS trades above its industry multiple and historical median while margins remain below prior-year levels, leaving execution central to the investment case.
ACLS Growth Outlook Is Improving
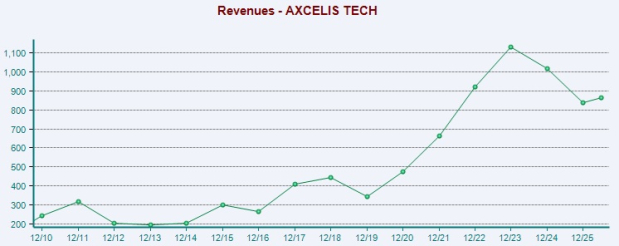
Management expects full-year 2026 revenues to grow at a mid-single-digit rate and anticipates further growth in 2027. The Zacks Consensus Estimate calls for 2027 revenues of $981 million and earnings of $5.29 per share, versus $884 million and $4.12 expected for 2026.
Applied Materials, Inc. AMAT reported fiscal third-quarter 2026 revenues of $9.12 billion, up 25% year over year. Lam Research Corporation LRCX reported record June-quarter revenues of $6.72 billion and cited artificial intelligence-driven demand across the semiconductor industry.
Image Source: Zacks Investment Research
Axcelis Aftermarket Revenue Adds Stability
Customer Solutions & Innovation revenues increased 35.1% year over year to $82.8 million in the second quarter of 2026. They also rose 14% sequentially from $72.6 million, adding another source of growth while systems demand recovers.
The business benefits from a larger installed base, higher equipment utilization and upgrades that add capacity within existing fab footprints. Management expects Customer Solutions & Innovation to build a larger base of revenues and profitability as utilization and the installed base expand.
ACLS Valuation Leaves Less Room for Error
ACLS trades at 21.2X forward 12-month earnings, above the Zacks industry multiple of 20.0X and its five-year median of 18.6X. Its PEG ratio is 6.19 and the stock carries a Value Score of F.
That valuation leaves less room for a slower recovery. Broader growth and firmer margins would provide more support for the multiple, but the current price already reflects a meaningful portion of the anticipated improvement.
Axcelis Margin Recovery Is Still Incomplete
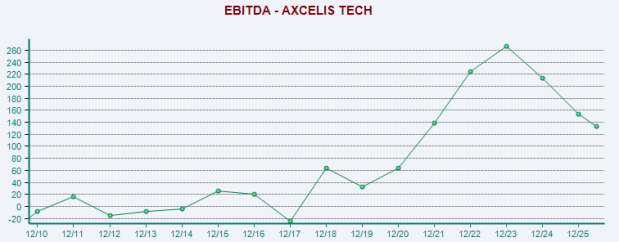
Second-quarter non-GAAP gross margin was 42.7%, down from 45.2% a year earlier. Non-GAAP operating margin also fell to 14.7% from 17.7%, even as revenues increased 10.6% year over year.
Management expects third-quarter non-GAAP gross margin of about 43% and only a slight sequential improvement in the fourth quarter. Memory mix, Customer Solutions & Innovation mix, service costs and a higher operating-expense base can limit earnings conversion while sales recover.
Image Source: Zacks Investment Research
ACLS Merger Upside Comes With Execution Risk
The pending all-stock combination with Veeco Instruments Inc. VECO could add laser annealing, ion beam deposition, metal-organic chemical vapor deposition, wet processing, lithography and advanced packaging capabilities. It could also expand exposure to advanced logic, gallium nitride and optical communications.
Axcelis shareholders approved the related share issuance in February 2026, but closing still depends on regulatory approval from China's State Administration for Market Regulation. Second-quarter free cash flow included about $6 million of cash transaction expenses associated with the pending merger.
ACLS Signals Point to a Mixed Near-Term Setup
Growth is returning, but premium valuation and incomplete margin recovery keep the near-term setup balanced. Better revenue momentum can improve the earnings picture, while slower order conversion or persistent margin pressure would make the current multiple harder to support.
ACLS currently carries a Zacks Rank #3 (Hold). Its Momentum Score of B is comparatively favorable, while the Value Score of F, Growth Score of F and VGM Score of F indicate weaker characteristics in those styles. The Style Scores complement the Zacks Rank rather than replace it.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Axcelis Technologies, Inc. (ACLS): Free Stock Analysis Report
Lam Research Corporation (LRCX): Free Stock Analysis Report
Applied Materials, Inc. (AMAT): Free Stock Analysis Report
Veeco Instruments Inc. (VECO): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).