

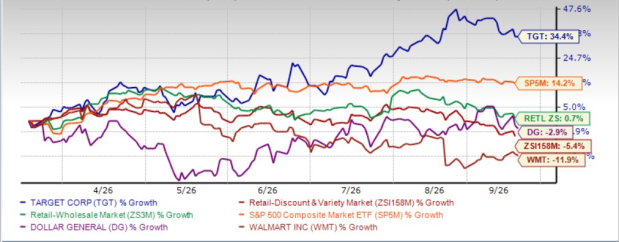
Target Corporation TGT has experienced a remarkable surge in its share price over the past six months. The stock has rallied 34.4% against the Zacks Retail-Discount Stores industry’s 5.4% decline. Target has also comfortably outperformed the broader Retail and Wholesale sector and the S&P 500 Index, which posted respective gains of 0.7% and 14.2%.
TGT has outpaced key retail peers, Walmart Inc. WMT and Dollar General Corporation DG. Shares of Walmart and Dollar General have declined 11.9% and 2.9%, respectively, over the same period.
Target’s impressive rally has been supported by improving business trends. The company has benefited from stronger consumer engagement, strength across key merchandise categories, solid digital performance and continued momentum in its high-margin non-merchandise businesses. These factors have helped bolster investor sentiment.
TGT Six-Month Stock Performance
Image Source: Zacks Investment Research
The key question now is whether Target still offers meaningful upside or much of the improvement is already priced in. A closer look at the company’s growth initiatives, operating trends, earnings outlook and valuation should help determine whether investors should stay invested, add to their positions or consider booking profits.
Decoding Potential Tailwinds Behind Target’s Rally
Target’s refreshed strategy is gaining traction, creating a firm base for sustainable sales and earnings growth. The company is sharpening its positioning around the combination of style, design, quality and value while concentrating on merchandising authority, an elevated guest experience, technology and stronger execution. Higher traffic suggests customers are choosing Target more frequently, which management views as one of the healthiest indicators of sustainable growth. Sales momentum has also been broad across channels, merchandise categories, demographics and income groups. Target now expects fiscal 2026 net sales growth in a range around 5%, one percentage point higher than its previous guidance.
Management is directing resources toward categories that are showing high customer response. Beauty, health and wellness, food, baby and kids, women’s style, home, toys and entertainment have become important areas of focus. Target has repositioned nearly half of its center-store grocery assortment, expanded fresh produce and devoted additional space to growing areas such as snacks, global foods and functional coffee. Its Fun101 transformation is similarly reallocating space toward LEGO, wearable technology, trading cards, collectibles and broader fandom experiences. Exclusive partnerships with Pokemon and LoveShackFancy strengthen Target’s cultural relevance, while the rollout of Target Beauty Studio and further changes across home and apparel provide additional opportunities to deepen merchandising differentiation.
The company’s integrated physical and digital model adds another durable growth avenue. Target’s stores serve as both shopping destinations and fulfillment hubs, supporting faster and more cost-effective delivery. Same-day services continue to gain traction, while ongoing investments in new stores, remodels and supply-chain capabilities should expand the reach and operational efficiency. At the same time, Target is investing in artificial intelligence and personalization to enhance digital discovery, improve merchandising decisions and engage consumers through emerging shopping platforms. Management has also highlighted encouraging growth in traffic originating from external AI platforms, such as OpenAI and Google.
Target is also strengthening its value proposition. The company has lowered prices on more than 10,000 items over the past year and plans further reductions while continuing to introduce trend-right merchandise, owned brands and exclusive offerings. Management is addressing tariff pressure through changes in country of origin, vendor collaboration and assortment adjustments. Target is developing meaningful higher-margin revenue streams. Roundel advertising, Target+ marketplace and Circle 360 memberships are growing rapidly and diversifying earnings beyond traditional merchandise sales. As these businesses scale, they can deepen customer engagement while providing attractive incremental profit streams that complement Target’s core retail operations.
Target retains significant financial and operational flexibility to fund its transformation while returning capital to shareholders. Profitability improved even after excluding tariff-refund benefits, supported by better merchandising performance, healthier gross margins and growth in higher-margin revenue streams. Management expects the full-year operating margin, excluding tariff refunds, to finish above last year’s adjusted level and raised adjusted earnings per share guidance to $9.90-$10.90. The range includes approximately $1.65 per share of second-quarter tariff refund benefits but excludes any potential future tariff refunds. Excluding the refund benefit, the midpoint of the updated guidance represents a 75-cent increase from the prior guidance range of $7.50-$8.50.
How Consensus Estimates Stack Up for Target
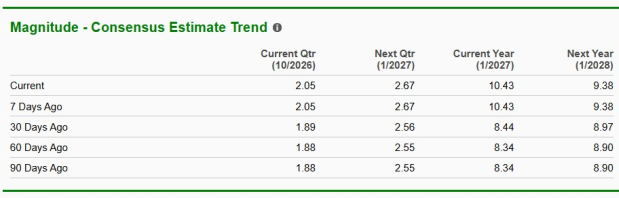
The Zacks Consensus Estimate for Target’s current fiscal-year sales and earnings per share indicates year-over-year growth of 4.8% and 37.8%, respectively. Encouragingly, earnings estimates have also moved higher. Over the past 30 days, the Zacks Consensus Estimate for earnings per share has increased by $1.99 to $10.43 for the current fiscal year and by 41 cents to $9.38 for the next fiscal year.
Image Source: Zacks Investment Research
Does Target Tick the Boxes for Value Investing?
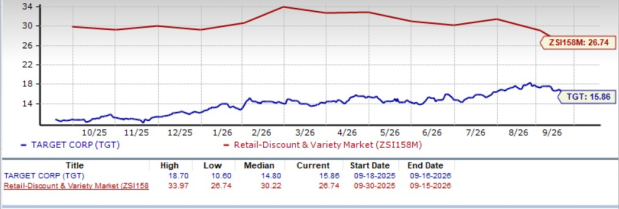
Target is trading at a forward 12-month price-to-earnings (P/E) ratio of 15.86, well below the industry average of 26.74 and the S&P 500’s forward multiple of 19.65. However, the stock currently trades at a premium to its one-year median P/E of 14.80, suggesting that some of the recent improvement in investor sentiment is already reflected in the valuation.
Target is trading at a discount to Walmart (with a forward 12-month P/E ratio of 34.75) but at a premium to Dollar General (15.38).
Image Source: Zacks Investment Research
How to Play Target Stock: Buy, Hold or Take Profits?
Strong customer engagement, merchandising gains, an expanding omnichannel ecosystem and higher-margin businesses are supporting continued earnings improvement. Management’s greater emphasis on value and ongoing investments in stores, digital capabilities and personalization further strengthen the company’s growth prospects. Positive earnings estimate revisions also reinforce confidence in the stock’s trajectory. Although TGT trades above its median value due to recent share price appreciation, it remains reasonable relative to the broader industry. Given this backdrop, existing investors may consider retaining their positions, while prospective investors can gradually build exposure to Target. Target currently carries a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Target Corporation (TGT): Free Stock Analysis Report
Walmart Inc. (WMT): Free Stock Analysis Report
Dollar General Corporation (DG): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).