

GlobalFoundries Inc. GFS is making steady progress in strengthening its profitability. The company delivered stronger-than-expected second-quarter 2026 results, supported by favorable business mix, manufacturing productivity gains and higher utilization. In the second quarter, gross profit increased 24% to $505 million, while IFRS gross margin expanded to 28.3% from 24.2% in the year-ago quarter. Non-IFRS gross margin was even stronger at 29.9%, representing a 470-basis-point year-over-year increase and a 90-basis-point sequential improvement.
Technology services, which includes IP, licensing, software, reticles and nonrecurring engineering activities, accounted for approximately 11% of second-quarter revenue. Solid traction in the Technology services business is expected to be a strong driver of Gross Margin in upcoming quarters.
The company is also benefiting from stronger demand in communications infrastructure and data centers. Revenues from this end market surged 62% year over year in the second quarter, marking the seventh consecutive quarter of double-digit growth. High-margin technologies such as silicon photonics and silicon germanium are also gaining momentum.
Apart from improving revenue mix, margin expansion is also driven by structural manufacturing-cost improvements and greater utilization of existing manufacturing capacity. Despite the favorable momentum, sustaining the improvements will depend on GF’s ability to balance profitability and investments in future growth. GFS needs to continue moving toward higher-value technologies while improving manufacturing productivity to sustain margin growth in the long run.
How Are Competitors Faring?
GlobalFoundries operates in a highly competitive foundry industry. It faces competition from industry giants, such as United Microelectronics UMC and Taiwan Semiconductor TSM. UMC's gross margin increased to 32.5% in the second quarter of 2026 from 29.2% in the first quarter and 28.7% a year earlier. UMC’s growth was driven by higher wafer shipments and better capacity utilization.
In the second quarter of 2026, TSM’s gross margin reached 67.7%, up 150 basis points sequentially and 910 basis points from the year-ago quarter. Management attributed the sequential improvement primarily to cost-improvement initiatives and higher capacity utilization.
GFS’ Price Performance, Valuation and Estimates
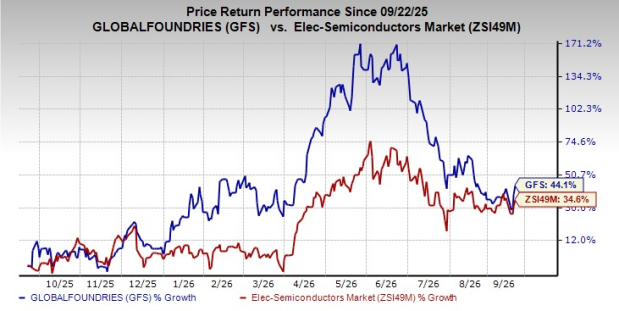
GFS has increased 44.1% over the past year compared with the industry’s growth of 34.6%.
Image Source: Zacks Investment Research
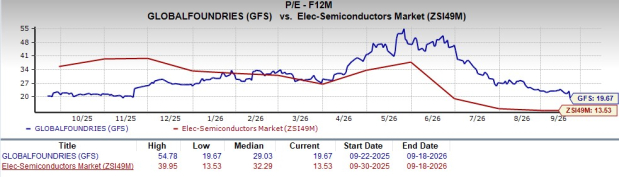
Going by the price/earnings ratio, the company's shares currently trade at 19.67 forward earnings, higher than the industry average of 13.53.
Image Source: Zacks Investment Research
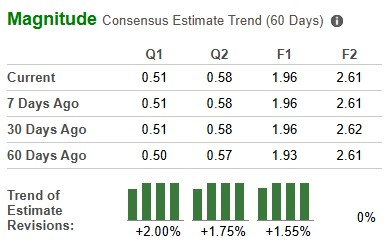
GFS’ earnings estimate for 2026 has improved over the past 60 days.
Image Source: Zacks Investment Research
GlobalFoundries currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
GlobalFoundries Inc. (GFS): Free Stock Analysis Report
Taiwan Semiconductor Manufacturing Company Ltd. (TSM): Free Stock Analysis Report
United Microelectronics Corporation (UMC): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).