

Hess Midstream LP HESM is generating more cash even as its 2026 operating outlook points to limited volume and EBITDA growth. Adjusted free cash flow is guided higher as capital spending falls, giving the partnership more room for distributions, buybacks and debt reduction.
That cash-flow shift is balanced by broadly flat expected oil and gas volumes, modest earnings expansion and a valuation close to its five-year median. The investment case therefore rests more on contracted cash generation and capital returns than on near-term operating acceleration.
Rising Free Cash Flow Strengthens HESM's Capital Returns
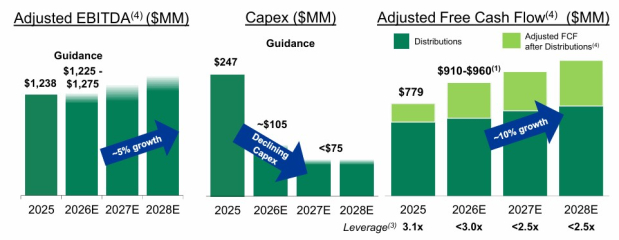
Adjusted free cash flow is projected at $910-$960 million in 2026, up from $779.1 million in 2025. The main driver is a much lighter capital program, with 2026 expenditures expected around $105 million versus $247.5 million last year.
At the midpoint, about $280 million of adjusted free cash flow after targeted distributions is expected to remain available for incremental shareholder returns and debt repayment. Management also targets at least 5% annual distribution-per-share growth through 2028, while leverage is expected to fall below 3.0X in 2026 and toward roughly 2.5X by 2028.
Image Source: Hess Midstream LP
Fee-Based Model Protects Cash Flow Visibility
Cash flow visibility is anchored by long-term commercial agreements with Chevron, alongside third-party services. Contracts are 100% fee-based, most extend through 2033 and roughly 95% of 2026 revenues are protected by minimum volume commitments.
Fixed-fee rates are adjusted annually for inflation up to 3%, while the business generally does not own or trade the commodities it handles. That limits direct commodity-price exposure, though lower commodity prices can still pressure producer activity and future throughput.
Flat 2026 Volumes Keep HESM's Growth Case in Check
HESM's operating outlook is less dynamic. Full-year 2026 guidance calls for oil and gas volumes to remain broadly flat with 2025, while Adjusted EBITDA of $1.225-$1.275 billion is roughly flat at the midpoint versus $1.238 billion in 2025.
Second-quarter trends illustrate the drag. Oil terminaling fell 15% year over year, water gathering declined 12% and gas processing slipped 4%, with lower new-well activity and Tioga Gas Plant maintenance among the causes. Management expects volumes to improve in the second half, but near-term growth remains measured.
HESM's Valuation Sits Near Its Five-Year Median
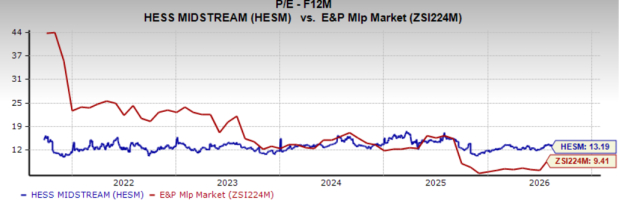
HESM trades at 13.19X forward 12-month earnings, almost in line with its five-year median of 13.23X but above the Zacks sub-industry's 9.41X. The comparison puts more weight on dependable cash generation and distributions than on a clearly discounted entry point.
Image Source: Zacks Investment Research
Enterprise Products Partners L.P. EPD reported record second-quarter 2026 Adjusted EBITDA of $2.8 billion and raised its quarterly distribution 2.8% year over year. Western Midstream Partners, LP WES raised 2026 free cash flow guidance to $1.1-$1.3 billion while maintaining a quarterly distribution of 93 cents, giving investors two midstream benchmarks for cash-return execution.
Mixed Signals Shape HESM's Near-Term Setup
HESM's near-term setup is mixed. Rising free cash flow, contractual protection and a lower capital burden support capital returns, while flat volumes and a near-normal valuation keep the growth case restrained.
The stock currently carries a Zacks Rank #2 (Buy), which points to a favorable short-term setup based on earnings estimate revisions. Yet its Value Score of D, Growth Score of C, Momentum Score of F and VGM Score of D show that valuation, growth and price-momentum characteristics are not equally supportive. Investors considering HESM may therefore weigh the improving cash-return profile against muted operating growth and less favorable Style Scores. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Hess Midstream Partners LP (HESM): Free Stock Analysis Report
Enterprise Products Partners L.P. (EPD): Free Stock Analysis Report
Western Midstream Partners, LP (WES): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).