

China’s electric vehicle (EV) company NIO Inc. NIO delivered 109,178 vehicles in the third quarter of 2026, up 25.4% year over year and within its own guided range of 108,000-111,000 units. Third-quarter deliveries consisted of 62,500 units from the NIO brand, 27728 units from the ONVO brand and 18,950 from Firefly. Cumulative deliveries as of Sept. 30, 2026 totaled 1,297,893 units.
Meanwhile, growth at close peers XPeng XPEV and Li Auto LI was less impressive. XPeng’s third-quarter deliveries came in at 118,390 units, marking a 2% increase from year-ago quarter deliveries. In contrast, Li Auto reported 99,964 deliveries in the September quarter, up 7.2% from the corresponding quarter of 2025.
While NIO’s delivery growth stands out, let’s look beyond the headline numbers to assess whether the stock is truly a buy at current levels.
NIO's Product Lineup Driving Growth
NIO's growth is being buoyed by its newer and upgraded vehicle models, with two flagship SUVs leading the way.
The ES8 reached 150,000 cumulative deliveries on Sept. 20, exactly one year after its launch. During the year, it topped sales among large SUVs and among all vehicles priced above RMB 400,000. The ES9 began deliveries on May 28 and crossed 30,000 units on Sept. 23, 2026. It has also been the best-selling battery electric vehicle priced above RMB 500,000 for three months in a row. These models are strengthening NIO's standing in the premium electric SUV segment.
NIO also reaches a broader range of customers at different price levels through its three brands— NIO, ONVO and Firefly.
NIO’s Profitability Improving
NIO's profitability has strengthened as it sells more vehicles and a larger share of them are higher-end models. Its vehicle margin rose to 18.5% in the second quarter of 2026, up from 10.3% in the same quarter last year. This gain came from selling more high-margin products and from lower costs.
Management plans to hold the vehicle margin close to the second-quarter 2026 level through the third and fourth quarters, even though material costs are expected to rise further. The company also expects both operating cash flow and free cash flow to be positive in each of these two quarters.
NIO's Battery Swapping Network Expands
NIO and Geely Automobile GELHY have agreed to combine their charging and battery-swapping networks, with each company taking a stake in the other. As part of the deal, Geely will launch more electric models that work with shared swapping standards, with NIO providing support.
NIO Power has set a target of running 10,000 battery-swapping stations worldwide by 2030. At that scale, its yearly electricity use is expected to go beyond 10 billion kWh.
The company is already building on a solid base. When it passed 100 million total swaps in February, it had 3,790 swapping stations, and it plans to open another 1,000 this year. Earlier in 2026, it also set a one-day record of 175,976 battery swaps.
NIO's Road Isn't All Smooth
Beneath the strong headline deliveries, investors should note that delivery growth slowed sharply as the third quarter progressed. Year-over-year growth was 71% in July, then fell to 14.5% in August and 7.7% in September.
Additionally, rising input costs could squeeze margins. Management aims to keep the vehicle margin near the second-quarter level, but achieving that will depend on how well the company manages sourcing and its product mix.
NIO's debt also remains high, with long-term debt-to-capitalization at about 82%.
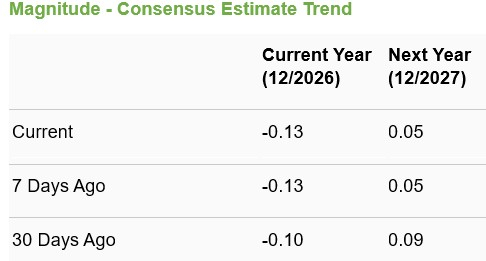
Earnings estimates are moving in the wrong direction as well. Over the past 30 days, the Zacks Consensus Estimate for NIO's 2026 loss per share has widened by 3 cents to 13 cents. The 2027 estimate still points to a return to profit, but the consensus EPS figure has dropped from 9 cents to 5 cents over the same period.
NIO’s Price Performance & Valuation
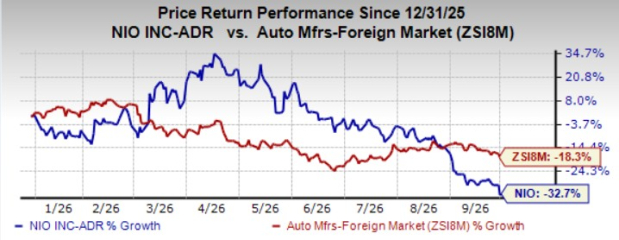
Year to date, shares of NIO have fallen roughly 33%, wider than the industry’s decline of 18%. However, shares of Li Auto and XPeng have also underperformed the industry, sliding 33% and 53%, respectively, during the same time frame.
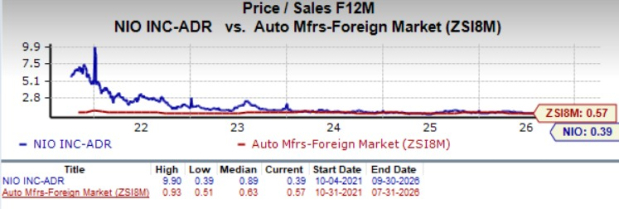
From a valuation perspective, NIO currently trades at a forward price-to-sales ratio of 0.39, below the industry’s 0.57.
Our Take
NIO's third-quarter deliveries, new product momentum, improving margins and expanding swapping network make a strong case. But slowing monthly year-over-year growth over the third quarter, elevated debt, rising costs and falling earnings estimates keep the risks real.
The third-quarter earnings report will be the key test. It should show whether margins held near the second-quarter level. Management's commentary on fourth-quarter deliveries will indicate whether the slowdown seen in August and September is temporary or a sign of weaker demand ahead.
Until then, the risk-reward looks balanced at best. Existing shareholders can stay put, but new investors would be better off waiting for the results and clearer fourth-quarter guidance.
NIO carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
NIO Inc. (NIO): Free Stock Analysis Report
Li Auto Inc. Sponsored ADR (LI): Free Stock Analysis Report
XPeng Inc. Sponsored ADR (XPEV): Free Stock Analysis Report
Geely Automobile Holdings Ltd. (GELHY): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).