

Westinghouse Air Brake Technologies Corporation, operating as Wabtec Corporation WAB, is strengthening its position in the global rail industry, supported by expanding service capabilities and rising opportunities in international markets. Its recent agreement worth more than $700 million with La Compagnie du TransGuinéen (CTG) underscores the company's growing presence in Africa and strengthens its long-term revenue prospects.
The agreement, Wabtec's largest services contract in Africa, covers maintenance, parts management, logistics, workforce training and remote diagnostics for locomotives operating along Guinea's 600-kilometer TransGuinean Railway. Combined with earlier locomotive orders, the deal takes Wabtec's Simandou-related business beyond $1.2 billion.
With the company securing long-duration service contracts and benefiting from rail infrastructure investments, investors may wonder whether WAB's growth prospects justify buying the stock despite its substantial share-price appreciation and premium valuation.
WAB's Strong Price Performance Reflects Investor Confidence
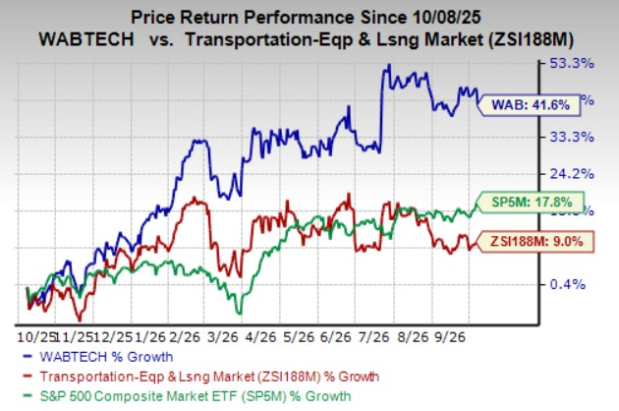
WAB's shares have gained 41.6% over the past year, significantly outperforming the Zacks Transportation - Equipment and Leasing industry's 9% rise and the S&P 500's 17.8% increase. The substantial outperformance reflects investors' confidence in the company's growth potential and its ability to capitalize on sustained demand for rail equipment and services.
Image Source: Zacks Investment Research
WAB's Services Expansion Strengthens Growth Prospects
Wabtec's expanding services portfolio is a key growth driver, supported by rising demand for locomotive modernization, maintenance and advanced rail technologies. The CTG agreement strengthens its long-term lifecycle services business, improving revenue visibility and customer relationships.
In the second quarter of 2026, revenues increased 17.5% year over year to $3.18 billion, while adjusted earnings per share (EPS) rose 21.6% to $2.76. Adjusted operating margin expanded 80 basis points to 21.9%. Wabtec's multi-year backlog rose 41.7% to $30.93 billion, while its 12-month backlog grew 11.3% to $9.14 billion, providing solid revenue visibility and supporting future growth.
Caterpillar CAT, through its Progress Rail business, competes with Wabtec in locomotive manufacturing, maintenance and related services. Caterpillar's emphasis on lifecycle services and predictive maintenance underscores the growing importance of technology-enabled aftermarket solutions. While competition from Caterpillar remains significant, Wabtec's integrated offerings and long-term contracts strengthen its ability to capitalize on rising rail infrastructure investments.
Similarly, Greenbrier Companies GBX provides railcar manufacturing, fleet management and maintenance services, highlighting the industry's focus on extending equipment life and improving operational efficiency. Greenbrier's diversified rail solutions reflect the opportunities arising from sustained infrastructure investments. Wabtec's expanding international presence and growing services portfolio position it to benefit from similar industry trends alongside Greenbrier Companies.
Wabtec's financial flexibility also supports investments and shareholder returns. During the second quarter, operating cash flow reached $441 million compared with $209 million a year earlier. The company repurchased $215 million in shares and distributed $53 million in dividends. Management raised its 2026 revenue guidance to $12.30–$12.60 billion and adjusted EPS outlook to $10.60-10.90, reflecting confidence in its operational momentum.
However, challenges persist. The complexity of servicing locomotives across demanding operating environments, potential project execution delays and competitive pressures could affect profitability. Moreover, integrating acquisitions and maintaining service standards across international markets will require disciplined execution. These factors warrant monitoring despite Wabtec's encouraging fundamentals.
WAB's Premium Valuation Warrants Attention
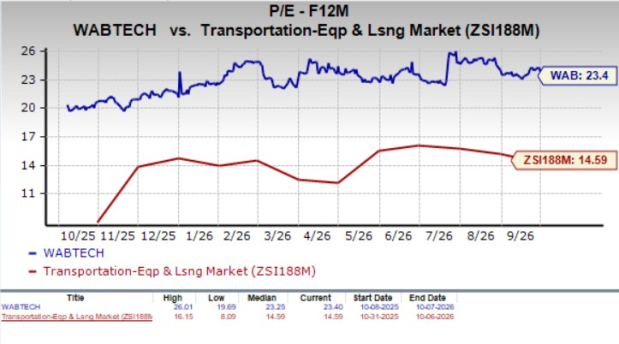
WAB currently trades at 23.4 times forward 12-month earnings, above the industry average of 14.59 times. This substantial premium suggests investors have already priced in considerable growth expectations.
Image Source: Zacks Investment Research
Although Wabtec's strong backlog, earnings momentum and growing services portfolio support a higher valuation, limited room for execution setbacks could heighten downside risks. Sustained earnings growth will be essential to justify the stock's premium.
Positive Earnings Estimate Revisions Reinforce WAB's Outlook
The Zacks Consensus Estimate for 2026 earnings is pegged at $10.89 per share, up 0.09% over the past 60 days. The 2027 consensus estimate has increased 0.32% to $12.43 per share during the same period.
Image Source: Zacks Investment Research
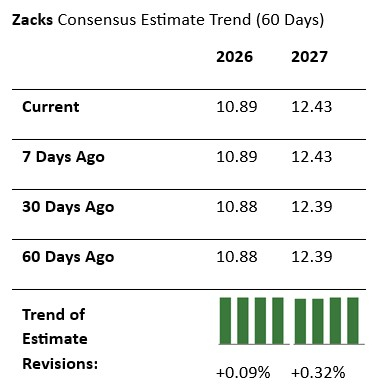
The upward revisions, although modest, signal improving earnings expectations, complementing Wabtec's strengthening order pipeline and favorable operating outlook.
Should Investors Buy WAB Stock Now?
Wabtec's expanding rail services business, highlighted by its landmark CTG agreement, enhances long-term revenue visibility and strengthens its international presence. Robust backlog growth, margin expansion, healthy cash generation and positive earnings estimates further reinforce its investment appeal.
Although the stock's premium valuation and operational challenges warrant caution, its favorable growth prospects and Zacks Rank #2 (Buy) support a positive investment stance. Investors seeking exposure to long-term rail infrastructure investment and recurring aftermarket revenues may consider buying WAB stock, while remaining mindful of valuation-related volatility. You can see the complete list of today’s Zacks #1 (Strong Buy) Rank stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Wabtec (WAB): Free Stock Analysis Report
Caterpillar Inc. (CAT): Free Stock Analysis Report
Greenbrier Companies, Inc. (The) (GBX): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).