

Dolce Vita is building momentum within Steven Madden, Ltd.’s SHOO portfolio as a compelling footwear lineup drives growth across wholesale and direct-to-consumer ("DTC") channels. The brand’s strength in jellies, ballet flats, Mary Janes, mid-heel dress shoes and thongs reflects its ability to tap into consumer preferences. Growing handbag demand and international progress provide additional avenues for expansion beyond its core footwear business.
This performance encouraged management to raise Dolce Vita’s 2026 revenue growth outlook to high single digits to low double digits. The upgrade followed a strong second quarter and signals greater confidence in the brand’s prospects. Growth across wholesale and DTC channels also suggests broad-based demand, giving Dolce Vita multiple routes to reach shoppers.
Beyond the footwear assortment, Dolce Vita continues to gain traction in handbags while expanding its presence in Canada, Mexico and the United Kingdom. These initiatives could expand its addressable market and create more opportunities to engage customers across categories. Sustaining that momentum would help establish a stronger foundation for growth while reducing reliance on any single product trend.
The brand’s progress complements stronger results at Steven Madden. Second-quarter revenues increased 19.1% year over year to $665.9 million or 11.2% excluding Kurt Geiger. Companywide wholesale revenues rose 13%, while DTC sales climbed 30.6%. Excluding Kurt Geiger, these channels grew 11.5% and 11.1%, respectively, highlighting underlying sales momentum across the broader portfolio alongside the acquisition’s contribution.
Following the second quarter, Steven Madden lifted its 2026 revenue growth guidance to 11-13% from 10-12%. Dolce Vita’s stronger outlook fits within that improving portfolio picture. Sustaining footwear demand while developing handbags and international markets could increase its contribution over time. Together, these growth drivers position Dolce Vita to become a more meaningful contributor to Steven Madden’s long-term revenue growth.
SHOO’s Price Performance, Valuation & Estimates
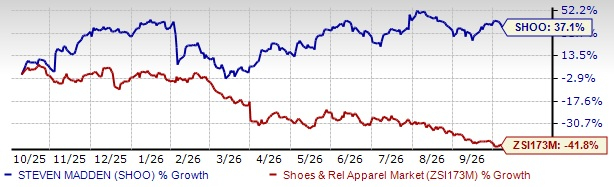
Shares of Steven Madden have risen 37.1% over the past year against the industry’s 41.8% decline.
Image Source: Zacks Investment Research
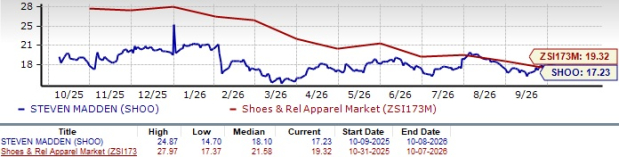
From a valuation standpoint, Steven Madden is trading at a forward 12-month price-to-earnings ratio of 17.23, below the industry average of 19.32. It has a Value Score of A.
Image Source: Zacks Investment Research
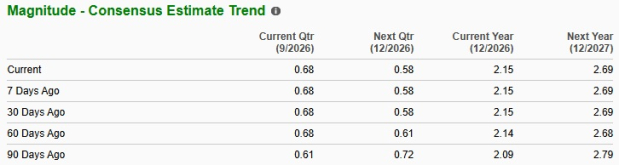
The Zacks Consensus Estimate for Steven Madden’s 2026 earnings implies year-over-year growth of 26.5%, whereas the same for 2027 indicates an uptick of 25%. Estimates for 2026 and 2027 have been revised upward by a penny each over the past 60 days.
Image Source: Zacks Investment Research
SHOO’s Zacks Rank & Other Key Picks
Steven Madden currently carries a Zacks Rank #2 (Buy).
Genesco Inc. GCO is a Nashville-based specialty retailer and branded company. It sells footwear and accessories through retail stores. The company sports a Zacks Rank #1 (Strong Buy) at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Genesco’s current fiscal-year earnings indicates 62.1% growth from the year-ago actual. GCO delivered a trailing four-quarter average earnings surprise of 11.2%.
Designer Brands Inc. DBI designs, produces and retails footwear and accessories. It offers shoes, boots, sandals, sneakers, socks, handbags and accessories. It currently carries a Zacks Rank #2.
The Zacks Consensus Estimate for Designer Brands’ current fiscal-year earnings and sales suggests growth of 225% and 0.6%, respectively, from the year-ago actuals. DBI delivered a trailing four-quarter average earnings surprise of 108.1%.
Urban Outfitters, Inc. URBN is a lifestyle products and services company that sells fashion apparel, accessories, footwear, home goods and related offerings through a portfolio of global consumer brands. The company also holds a Zacks Rank of 2 at present.
The Zacks Consensus Estimate for Urban Outfitters’ current fiscal-year earnings and sales implies growth of 14% and 9.5%, respectively, from the year-ago actuals. URBN delivered a trailing four-quarter average earnings surprise of 9.7%.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Steven Madden, Ltd. (SHOO): Free Stock Analysis Report
Urban Outfitters, Inc. (URBN): Free Stock Analysis Report
Genesco Inc. (GCO): Free Stock Analysis Report
Designer Brands Inc. (DBI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).