

The Bank of New York Mellon Corporation BNY is scheduled to report third-quarter 2026 results on Oct. 15, before market open. The company’s quarterly revenues and earnings are expected to have increased on a year-over-year basis.
In the last reported quarter, BNY’s earnings surpassed the Zacks Consensus Estimate. Results were primarily aided by a rise in fee revenues and net interest income (NII). Growth in the assets under custody and/or administration (AUC/A), and assets under management (AUM) balances further supported the results.
BNY has an impressive earnings surprise history. Its earnings surpassed the Zacks Consensus Estimate in the trailing four quarters, the average beat being 10.61%.
BNY Price and EPS Surprise
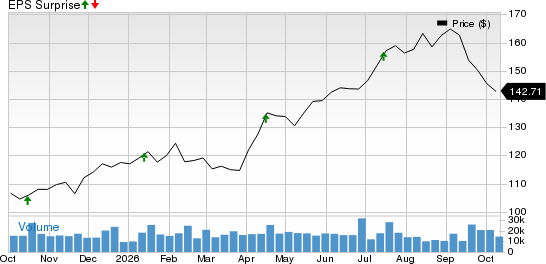
BNY price-eps-surprise | BNY Quote
The consensus estimate for the company’s third-quarter earnings is pegged at $2.26 per share, which has been unchanged over the past seven days. The estimated figure indicates a rise of 18.3% from the year-ago quarter’s reported number.
The consensus estimate for quarterly sales is pegged at $5.56 billion, implying 9.5% year-over-year growth.
Key Factors Impacting BNY’s Q3 Performance
Fee Revenues: BNY’s investment services fees, which account for a substantial portion of its total revenues, are expected to have benefited from favorable global equity market performance during the third quarter of 2026. Higher market valuations are likely to have supported AUC/A balances, thereby driving asset servicing revenues. Sustained client activity, healthy demand for corporate trust services and continued momentum in clearing, collateral management and securities servicing businesses are expected to have offered support. The Zacks Consensus Estimate for third-quarter investment services fees is pegged at $2.85 billion, suggesting a 10.1% rise from the year-ago quarter’s reported figure.
Likewise, BNY’s investment management and performance fees are expected to have benefited from higher average AUM, supported by favorable equity market performance, and continued demand for wealth management solutions and select investment strategies. The Zacks Consensus Estimate for investment management and performance fees is pegged at $819 million, indicating a 4.7% year-over-year increase.
Meanwhile, financing-related fees are expected to have been under pressure, reflecting fluctuations in client financing demand and transaction activity. The consensus estimate for financing-related fees stands at $62 million, indicating a 7.5% year-over-year decline.
Distribution and servicing fees are likely to have benefited modestly from improved average asset balances and continued client activity, although product-mix shifts and fee pressures might have limited growth. The consensus estimate for these fees is pegged at $38.38 million, implying a 3.7% rise from the prior-year quarter’s actual.
BNY’s foreign exchange revenues are expected to have benefited from client trading activity, currency market fluctuations, and demand for foreign exchange execution and hedging services amid shifting interest rate expectations and global macroeconomic uncertainties. The consensus estimate for foreign exchange revenues stands at $204 million, suggesting a 22.9% increase from the year-ago quarter.
Overall, growth in asset servicing, investment management and foreign exchange revenues is expected to have supported BNY’s fee income performance. The Zacks Consensus Estimate for total fees and other revenues is pegged at $4.16 billion, indicating an 8.2% year-over-year rise.
NII: BNY’s NII is expected to have benefited from growth in interest-earning assets and continued balance-sheet optimization during the third quarter. Improved yields on reinvested securities and disciplined deposit pricing are expected to have provided support. Continued client activity across securities servicing, clearing and collateral management businesses is also likely to have supported deposit balances and liquidity deployment, providing an additional boost to NII.
The consensus mark for NII is $1.39 billion, indicating a 12.4% year-over-year rise.
Expenses: Because of higher restructuring charges and buyouts, BNY’s expenses have been elevated over the past few years. In the third quarter, overall costs are expected to have increased, driven by inflationary pressure, technology upgrades and a multi-year transformation plan.
What the Zacks Model Unveils for BNY
According to our quantitative model, the chances of BNY beating the Zacks Consensus Estimate this time are high. This is because it has the right combination of the two key ingredients — a positive Earnings ESP and a Zacks Rank #3 (Hold) or better.
You can uncover the best stocks to buy or sell before they are reported with our Earnings ESP Filter.
Earnings ESP: The Earnings ESP for BNY is +0.18%.
Zacks Rank: The company currently carries a Zacks Rank #3. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Other Bank Stocks That Warrant a Look
Here are a couple of other bank stocks that you may want to consider, as our model shows that these, too, have the right combination of elements to post an earnings beat this time:
The PNC Financial Services Group PNC is scheduled to announce third-quarter 2026 results on Oct. 15. The company has a Zacks Rank #3 and an Earnings ESP of +0.80% at present.
Quarterly earnings estimates for PNC Financial have been revised lower to $4.97 over the past week.
The Earnings ESP for Prosperity Bancshares PB is +0.22% and it carries a Zacks Rank #3 at present. The company is slated to report third-quarter 2026 results on Oct. 28.
Over the past seven days, the Zacks Consensus Estimate for PB’s quarterly earnings has been revised lower to $1.63 per share.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
BNY (BNY): Free Stock Analysis Report
The PNC Financial Services Group, Inc (PNC): Free Stock Analysis Report
Prosperity Bancshares, Inc. (PB): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).