

Fidelity National Information Services, Inc. FIS is well positioned for growth, supported by solid performance in Banking Solutions, AI-driven innovation and strong cash flow generation. Its forward P/E of 5.15X is significantly below the industry average of 17.92X, while its Value Score of A indicates attractive valuation metrics.
FIS, a Jacksonville, FL-based financial technology company with a market capitalization of approximately $17.6 billion, provides technology solutions to financial institutions, businesses and developers globally. Over the past six months, FIS shares have lost 26.7% compared to a 10.6% gain for the industry. FIS currently carries a Zacks Rank #3 (Hold).
Where Do Estimates for FIS Stand?
The Zacks Consensus Estimate for Fidelity National’s 2026 earnings is pegged at $6.20 per share, indicating a 7.8% year-over-year rise. It has remained stable over the past 30 days. The consensus mark for revenues is pegged at $13.67 billion for 2026, implying a 28% year-over-year rise. FIS surpassed earnings estimates in three of the trailing four quarters and missed once, delivering an average surprise of 2.1%.
Fidelity National Information Services, Inc. Price, Consensus and EPS Surprise
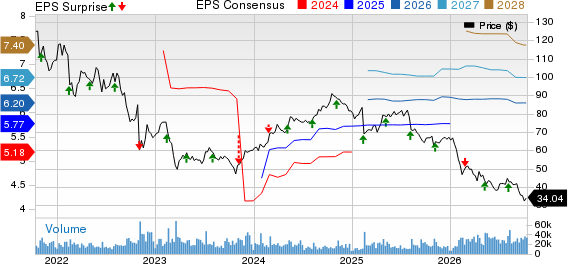
Fidelity National Information Services, Inc. price-consensus-eps-surprise-chart | Fidelity National Information Services, Inc. Quote
FIS’ Growth Drivers
FIS is benefiting from financial institutions’ continued investment in digital banking, payment systems and technology modernization. Its broad product portfolio, global client base and recurring revenue streams provide a foundation for growth across banking and capital markets. First-half recurring revenue growth was 4.9% on a pro forma basis, reflecting continued demand for its core solutions.
FIS has room to generate more revenues from existing clients by expanding the range of solutions they use. According to its investor presentation, 72 of its top 100 clients use solutions across banking, payments and capital markets. Revenues from clients using all three solution categories are nearly double that from those using only one, suggesting that broader adoption could help FIS increase revenue per client.
AI is becoming another potential growth driver as FIS develops AI-enabled products and expands their use across its business. The company reported more than 200 customers using its AI products and over 500 opportunities in its AI pipeline. These initiatives could help financial institutions automate processes and improve efficiency, although their longer-term revenue contribution will depend on customer adoption and successful execution.
Banking Solutions remains a key growth contributor. During the first half of 2026, its adjusted revenues grew 44.0% year over year, while Capital Markets adjusted revenues increased 3.1%. The figures reflect adjusted growth rates, which include the impact of the Total Issuing Solutions acquisition. While the acquisition strengthens FIS’ scale and earnings base, underlying pro forma revenue growth offers a clearer view of the business’s organic operating momentum.
Cost savings, business mix and the Total Issuing Solutions acquisition supported an adjusted EBITDA margin of 40.7% in the first half of 2026, up 184 basis points year over year. Free cash flow rose 157% to $999 million, prompting FIS to raise its 2026 target to $2.15-$2.25 billion. FIS also aims to generate more than $3 billion in free cash flow by 2028. However, temporarily curtailing share repurchases to prioritize debt reduction following the acquisition shows that deleveraging remains an important capital-allocation priority, even as quarterly dividends continue.
FIS’ Key Risks
There are some factors, however, that investors should keep an eye on.
FIS faces pressure from slower growth in its Capital Markets business. The company lowered its full-year 2026 pro forma revenue growth outlook to 4.5-5.0% from 5.1-5.7%. Slower sales and delayed conversion of its pipeline could weigh on revenue growth, making it harder for FIS to sustain stronger operating momentum.
The acquisition has also increased FIS’ debt and interest burden, limiting financial flexibility. As of June 30, 2026, long-term debt, excluding the current portion, totaled $15.4 billion, up from $9.1 billion at the end of 2025. Net interest expense rose 109% year over year to $397 million in the first half of 2026, primarily reflecting additional borrowings used to finance the acquisition. FIS’ ability to reduce debt while sustaining investment and growth will remain an important factor for investors to monitor.
Better-Ranked Players
Some better-ranked stocks in the business services space are Sezzle Inc. SEZL, CBIZ, Inc. CBZ and PayPal Holdings, Inc. PYPL, each carrying a Zacks Rank #2 (Buy) at present. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The Zacks Consensus Estimate for Sezzle’s 2026 earnings is pinned at $5.24 per share, which has remained stable over the past 30 days. Sezzle beat earnings estimates in each of the trailing four quarters, with the average surprise being 17.4%. The consensus estimate for 2026 revenues is pegged at $609.23 million, implying 35.3% year-over-year growth.
The Zacks Consensus Estimate for CBIZ’s 2026 earnings is pinned at $4.17 per share, which has witnessed one upward revision in the past 30 days against no movement in the opposite direction. CBIZ beat earnings estimates in three of the trailing four quarters and missed once, with the average surprise being 8.9%. The consensus estimate for 2026 revenues is pegged at $2.84 billion, implying 2.8% year-over-year growth.
The Zacks Consensus Estimate for PayPal’s 2026 earnings is pinned at $5.38 per share, which indicates a 1.3% year-over-year improvement. PYPL beat earnings estimates in three of the trailing four quarters and missed once, with the average surprise being 5.3%. The consensus estimate for 2026 revenues is pegged at $34.66 billion, implying 4.5% year-over-year growth.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Fidelity National Information Services, Inc. (FIS): Free Stock Analysis Report
CBIZ, Inc. (CBZ): Free Stock Analysis Report
PayPal Holdings, Inc. (PYPL): Free Stock Analysis Report
Sezzle Inc. (SEZL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).