

Delta Air Lines DAL has lowered its full-year 2026 earnings guidance following disappointing third-quarter results released on Oct. 9, as surging fuel expenses and rising operating costs continue to pressure profitability. The airline now expects adjusted earnings of $5.10-$5.60 per share, down from its earlier projection of $6.50-$7.50.
In the third quarter of 2026, adjusted earnings of $1.72 per share missed the Zacks Consensus Estimate by 4.44%. Despite a 16% increase in adjusted revenues to $17.59 billion, escalating expenses weighed on margins. The combination of disappointing earnings and reduced guidance raises concerns about DAL's near-term prospects.
DAL's Share Price Outperformance
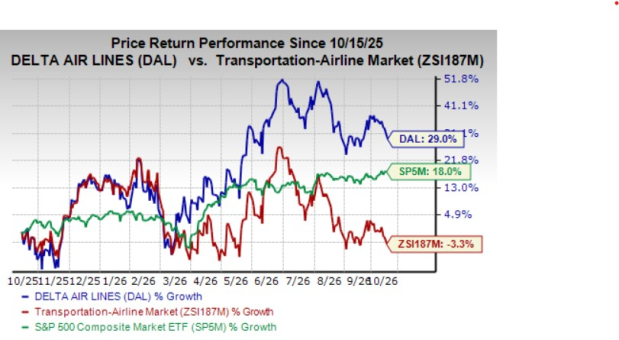
DAL's shares have gained 29% over the past year, outperforming the Zacks Transportation - Airline industry's 3.3% decline and the S&P 500's 18% growth. However, mounting cost pressures and weakening earnings expectations could challenge this momentum.
Image Source: Zacks Investment Research
Factors Weighing on DAL's Investment Appeal
Surging Fuel Costs Pressure Margins: Delta's adjusted fuel expenses surged 62% year over year to $4.14 billion in the third quarter, as average fuel prices increased 60% to $3.61 per gallon. Consequently, adjusted operating income declined 2% to $1.66 billion, while adjusted operating margin contracted 170 basis points to 9.4%. Non-fuel expenses also increased 8%, reflecting higher crew and revenue-related costs.
The challenging fuel environment poses risks across the airline industry. United Airlines UAL and American Airlines AAL also operate in a fuel-sensitive industry, where higher energy prices can constrain profitability. Like DAL, both UAL and AAL face the broader challenge of balancing revenue growth with escalating operating expenses. We expect high fuel costs to hurt the third-quarter results of both United Airlines (scheduled to be released on Oct. 20) and American Airlines (scheduled to be released on Oct. 22).
Weakening Cash Flow and Financial Obligations: Delta generated $463 million in free cash flow during the September quarter, down from $833 million a year earlier. Higher capital expenditures and increased operating costs constrained cash generation. Although adjusted net debt declined $2.24 billion year over year to $13.35 billion, substantial financial obligations continue to limit flexibility.
The company's plan to repay more than $2 billion of debt in 2026 supports balance-sheet improvement. However, persistent cost inflation and weaker free cash flow could constrain its ability to simultaneously fund expansion, reduce debt and reward shareholders.
Strong Demand Offers Limited Relief: Despite these challenges, Delta continues to benefit from healthy travel demand and premium offerings. Passenger revenues increased 15% year over year to $15.53 billion, while premium-ticket revenues climbed 18% to $6.82 billion. Loyalty-related revenues also grew, supported by its American Express partnership.
DAL's premium-focused strategy remains a competitive strength against United Airlines and American Airlines, which also compete for corporate and leisure travelers. However, strong demand alone may not offset rising operating costs, particularly when fuel expenses increase faster than revenues.
Delta expects approximately 20% revenue growth in the fourth quarter but anticipates adjusted operating margins of only 7-9%. Its projected fuel price of $4.25 per gallon suggests continued pressure on profitability.
DAL's Valuation and Earnings Revisions Signal Caution
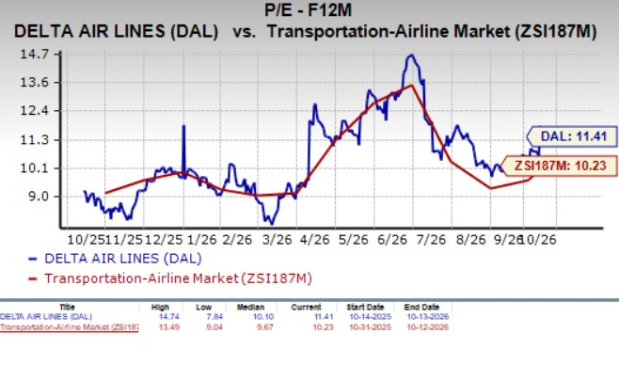
DAL currently trades at 11.41 X forward 12-month earnings, above the industry average of 10.23 X. Although its strong premium-travel franchise supports its valuation, the earnings outlook raises questions about whether this premium is justified.
Image Source: Zacks Investment Research
With profitability under pressure, DAL's valuation offers limited comfort. Industry competition involving United Airlines and American Airlines adds to the challenges, as airlines seek to protect margins while managing elevated expenses. Without stronger earnings visibility, investors may find it difficult to justify paying a premium for DAL.
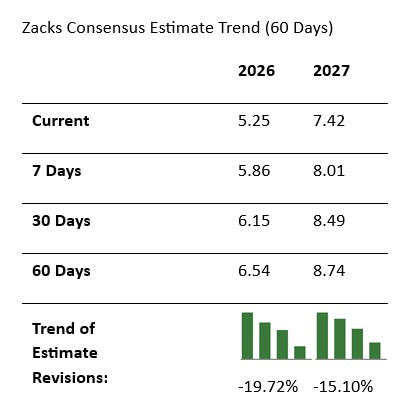
Moreover, analysts have sharply lowered earnings expectations. The Zacks Consensus Estimate for 2026 earnings has declined 19.72% over the past 60 days to $5.25 per share. The 2027 consensus estimate has fallen 15.10% to $7.42 per share over the same period, indicating weakening confidence in the company's earnings trajectory.
Image Source: Zacks Investment Research
Should Investors Sell DAL Stock Now?
Delta's reduced earnings guidance underscores the growing impact of elevated fuel costs and margin pressure despite healthy passenger demand. Weakening cash generation, substantial debt and negative earnings estimate revisions further cloud its investment outlook.
Although premium revenues and improving leverage remain encouraging, DAL's valuation premium and Zacks Rank #5 (Strong Sell) suggest limited near-term investment appeal. Given the mounting profitability challenges and downside risks, investors may consider avoiding fresh exposure or reducing their holdings in DAL stock until earnings visibility improves. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Delta Air Lines, Inc. (DAL): Free Stock Analysis Report
United Airlines Holdings Inc (UAL): Free Stock Analysis Report
American Airlines Group Inc. (AAL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).