

Accenture plc ACN has moved higher recently, shifting attention to whether improving business momentum can sustain the advance. Fiscal 2026 revenue growth, stronger fourth-quarter activity and rising enterprise AI adoption support the case for continued demand.
The counterweight is that acquisitions will supply a meaningful share of fiscal 2027 growth while discretionary spending, pricing and financing costs remain pressure points. That mix argues for a measured view of the rally.
Accenture’s Rally Meets a Stronger Growth Narrative
Fiscal 2026 revenues reached $74.18 billion, increasing 5% in local currency. Growth strengthened in the fourth quarter, when revenues rose 7% in local currency and exceeded the company’s guidance range.
For fiscal 2027, management expects 3%-6% local-currency revenue growth. Acquisitions are expected to contribute 2%-2.5%, leaving organic growth dependent on client spending and execution across consulting and managed services.
ACN’s AI Momentum Adds Fuel to the Growth Case
More than 400 clients initiated advanced AI projects with Accenture in fiscal 2026, including nearly 100 in the fourth quarter. Bookings from eight emerging AI and data partners more than tripled from fiscal 2025, while related revenues more than doubled.
International Business Machines IBM is also expanding enterprise AI through its consulting business, including new services and partnerships aimed at deploying AI across business workflows. Cognizant Technology Solutions CTSH likewise continues to build enterprise AI capabilities, underscoring the competitive intensity around AI-led transformation services.
Managed Services Give Accenture Revenue Visibility
Managed Services generated $37.30 billion in fiscal 2026 revenues, up from $34.57 billion a year earlier and increasing 6% in local currency. The business grew faster than Consulting, which posted 3% local-currency growth for the year.
Fourth-quarter Managed Services bookings reached a record $12.77 billion, producing a 1.4 book-to-bill ratio. Full-year bookings were $43.67 billion, supporting visibility from multiyear and recurring client engagements.
ACN’s Valuation Leaves Room but Risks Remain
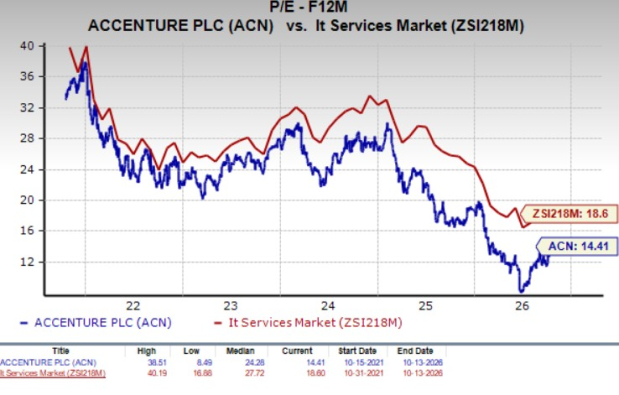
ACN trades at 14.4X forward 12-month earnings, below the Zacks sub-industry’s 18.6X and its own five-year median of 24.3X. That discount leaves room for a rerating if growth and execution improve.
Image Source: Zacks Investment Research
Risks remain. Discretionary demand has not meaningfully changed, pricing remains weak in several areas and fiscal 2027 acquisition spending is expected to total about $8 billion. The July 2026 debt offering is also expected to add roughly $250 million in annual interest expense, while lower average cash balances are expected to reduce interest income by about $100 million.
Accenture’s Signals Support a Measured View
Accenture’s operating trends, AI demand and recurring-services base provide support for the recent advance, but the growth outlook still depends partly on acquisitions and a stable client-spending environment. The stock’s discounted valuation provides another positive offset, though execution and financing risks limit the case for a more aggressive stance.
ACN currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
ACN’s VGM Score of A and Momentum Score of A point to favorable combined style characteristics and price momentum, while its Value Score of B and Growth Score of B are also constructive. Still, Style Scores are designed to complement the Zacks Rank, and a Hold rank suggests a more balanced near-term earnings-revision picture.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Accenture PLC (ACN): Free Stock Analysis Report
International Business Machines Corporation (IBM): Free Stock Analysis Report
Cognizant Technology Solutions Corporation (CTSH): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).