

Capital One COF is slated to report third-quarter 2026 results on Oct. 20, after market close.
In the second quarter of 2026, COF’s earnings beat the Zacks Consensus Estimate, driven by higher revenues, lower provisions, loan growth and net interest margin improvement. However, higher expenses and a sequential decline in deposits were the undermining factors.
The company’s to-be-reported quarter’s performance is expected to have been supported by its credit card business. The Zacks Consensus Estimate for revenues is pegged at $16.11 billion, indicating year-over-year growth of 4.9%.
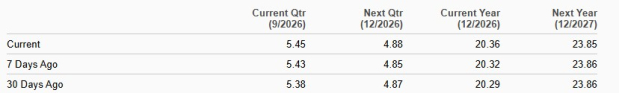
In the past seven days, the consensus estimate for earnings for the to-be-reported quarter has been revised marginally higher to $5.45. Nonetheless, the estimate indicates an 8.4% fall from the prior-year quarter.
Estimate Revision Trend
Image Source: Zacks Investment Research
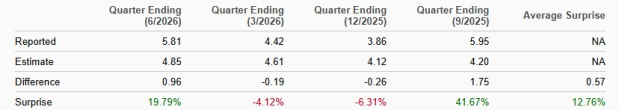
COF does not have an impressive earnings surprise history. The company’s earnings outpaced the Zacks Consensus Estimate in two of the trailing four quarters and lagged in the other two, with the average beat being 12.76%.
Earnings Surprise History
Image Source: Zacks Investment Research
Factors at Play for Capital One’s Q3 Results
Net Interest Income (NII): The Federal Reserve raised interest rates by 25 basis points in September and hinted at a hawkish stance going forward amid persistently higher inflation. Further, weakening consumer sentiment because of geopolitical and macro headwinds continued to dominate the third-quarter narrative.
The overall consumer lending scenario was subdued in the quarter. Per the Fed’s latest data, demand for consumer loans was weak. The Zacks Consensus Estimate for total average earning assets is pegged at $612.5 billion, implying a 3.2% rise from the prior-year quarter.
These developments are likely to have adversely impacted Capital One’s NII growth in the to-be-reported quarter, while continued efforts to strengthen card operations are expected to have provided some support. The consensus estimate for NII of $12.71 billion indicates 2.5% year-over-year growth.
Fee income: Supported by a steady rise in credit card usage and the Discover Financial buyout, Capital One’s interchange fees (constituting more than 60% of fee income) are likely to have increased in the quarter under review. The Zacks Consensus Estimate for interchange fees is $2.23 billion, suggesting a 23.3% year-over-year jump.
The consensus estimate for service charges and other customer-related fees of $855.4 million implies nearly a 1% year-over-year rise. The Zacks Consensus Estimate for other non-interest income is pegged at $383.6 million, indicating a 30.5% surge.
Thus, the consensus estimate for total non-interest income of $3.45 billion indicates growth of 16.9% from the prior-year quarter.
Expenses: Capital One has been witnessing a persistent rise in expenses over the past several quarters due to higher marketing costs and investment in technology upgrades. This, along with the strategic acquisitions and inflation pressure, is expected to have resulted in an increase in operating expenses in the third quarter.
Asset Quality: Capital One is likely to have increased its provisions for credit losses in the third quarter amid elevated borrowing costs and sustained demand for credit card loans. Moreover, persistent inflationary pressures, exacerbated by the Middle East conflict and oil price volatility, may have strained consumers’ financial health and repayment capacity, increasing the risk of delinquencies and credit losses.
What Our Quantitative Model Unveils for COF
According to our quantitative model, the chances of Capital One beating the Zacks Consensus Estimate for earnings this time are low. This is because it does not have the right combination of the two key ingredients — a positive Earnings ESP and a Zacks Rank #3 (Hold) or better.
You can uncover the best stocks to buy or sell before they are reported with our Earnings ESP Filter.
Earnings ESP: The Earnings ESP for Capital One is -0.02%.
Zacks Rank: The company currently carries a Zacks Rank #3. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Capital One’s Price Performance
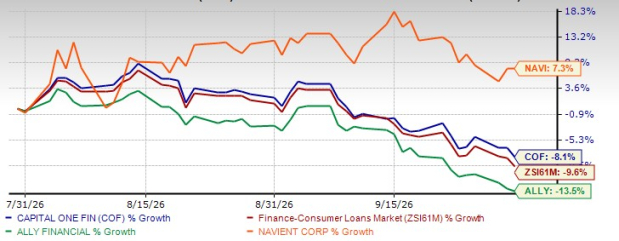
In the third quarter, COF shares declined 8.1% compared with the industry’s fall of 9.6%. Meanwhile, Ally Financial ALLY stock has lost 13.5%, while Navient Corporation NAVI has rallied 7.3%.
3Q26 Price Performance
Image Source: Zacks Investment Research
Ally Financial is scheduled to announce third-quarter 2026 numbers on Oct. 20, whereas Navient is set to report on Nov. 4.
Over the past week, the Zacks Consensus Estimate for Ally Financial’s third-quarter 2026 earnings has been revised lower to $1.32. The consensus estimate for Navient has been revised higher to 16 cents over the past seven days.
At present, ALLY carries a Zacks Rank #5 (Strong Sell), while NAVI sports a Zacks Rank #1.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Capital One Financial Corporation (COF): Free Stock Analysis Report
Ally Financial Inc. (ALLY): Free Stock Analysis Report
Navient Corporation (NAVI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).