

Moody’s MCO has reported third-quarter 2026 adjusted earnings of $4.14 per share, which missed the Zacks Consensus Estimate of $4.25. However, the bottom line increased 6% from the year-ago quarter.
MCO shares lost almost 3% in pre-market trading on a weaker-than-expected quarterly performance. However, a full day’s trading session will depict a clearer picture.
The results were primarily hurt by an increase in operating expenses and lower Moody’s Investors Service revenues. Nevertheless, steady demand for analytics and growth in recurring revenues supported the results. The company’s operating cash flow remained strong in the quarter.
After considering certain non-recurring items, net income attributable to Moody’s was $734 million, or $4.24 per share, up from $646 million, or $3.60 per share, in the prior-year quarter.
MCO’s Revenues Improve, Costs Rise
Quarterly revenues were $2.02 billion, up 1% year over year. However, the top line missed the Zacks Consensus Estimate of $2.06 billion.
Total expenses were $1.12 billion, up 2% year over year.
Adjusted operating income of $1.06 billion was relatively stable year over year. The adjusted operating margin was 52.6%, down from 52.9% a year ago.
Moody’s Quarterly Segment Performance Mixed
Moody’s Investors Service revenues declined 1% year over year to $1.09 billion. The decline was primarily caused by lower Leveraged Finance issuance. Corporate Finance revenues declined 8%, while Structured Finance revenues increased 5%. Financial Institutions revenues rose 2%, while Public, Project and Infrastructure Finance revenues jumped 11%.
Moody’s Analytics revenues rose 3% to $936 million. The increase was driven by 3% growth in Research and Insights and a 7% rise in Data and Information, while Decision Solutions revenues remained relatively stable year over year.
Moody’s Analytics annualized recurring revenues increased 8% year over year to $3.69 billion.
MCO’s Balance Sheet Solid
As of Sept. 30, 2026, Moody’s had total cash, cash equivalents and short-term investments of $1.62 billion, down from $2.45 billion as of Dec. 31, 2025.
The company had $6.34 billion in outstanding long-term debt.
Moody’s Share Repurchase Update
In the first nine months of 2026, MCO repurchased $2.6 billion worth of shares.
MCO’s 2026 Guidance
Moody’s reaffirmed its adjusted earnings guidance of $16.50-$17 per share.
The company projects revenues to increase in the high-single-digit percent range.
Operating expenses are expected to increase in the mid-single-digit percent range.
Our Take on MCO
Moody’s remains well-positioned for growth, driven by steady demand for analytics, recurring revenue growth and strength in diverse operations. Elevated operating expenses, lower leveraged finance issuance, and geopolitical and macroeconomic uncertainties are likely to hurt its financials.
In September, Moody’s announced its plan to acquire a minority stake in PhilRatings to expand its Asia-Pacific presence, strengthen its position in the Philippine debt market and capitalize on growing infrastructure financing demand.
Moody's Corporation Price, Consensus and EPS Surprise
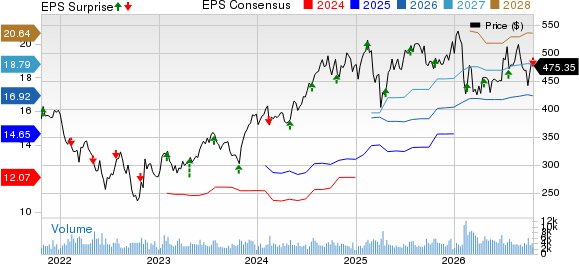
Moody's Corporation price-consensus-eps-surprise-chart | Moody's Corporation Quote
Currently, Moody’s carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Performance & Expectations of MCO’s Peers
Accenture plc. ACN reported fourth-quarter fiscal 2026 results, with earnings and revenues surpassing the Zacks Consensus Estimate.
ACN's earnings of $3.29 per share beat the Zacks Consensus Estimate of $3.19 by 3.1%. Earnings rose 8.6% from adjusted earnings of $3.03 in the year-ago quarter. Revenues of $18.7 billion topped the consensus mark of $18 billion by 3.7% and increased 6.2% year over year in U.S. dollars.
S&P Global Inc. SPGI is scheduled to report third-quarter 2026 results on Oct. 27.
Over the past seven days, the Zacks Consensus Estimate for S&P Global’s quarterly earnings has been revised higher to $4.43. The estimated figure indicates a 6.3% decline from the prior-year quarter.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Moody's Corporation (MCO): Free Stock Analysis Report
Accenture PLC (ACN): Free Stock Analysis Report
S&P Global Inc. (SPGI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).