

Edwards Lifesciences EW sees Transcatheter Mitral and Tricuspid Therapies (“TMTT”) momentum, fueled by PASCAL, EVOQUE and SAPIEN M3, supported by clinical evidence and broader market access. The company’s Transcatheter Aortic Valve Replacement (“TAVR”) business continues to grow, with SAPIEN platform durability and evidence supporting earlier treatment of aortic stenosis. Its strong balance sheet boosts investments and share repurchases. Meanwhile, Edwards faces tariff uncertainty and adverse currency movements that could pressure margins and earnings.
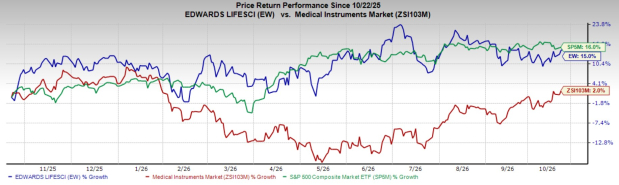
Over the past year, this Zacks Rank #3 (Hold) stock has gained 15% compared with the 2% growth of the industry and the S&P 500 composite’s 16% return.
The renowned global medical device company has a market capitalization of $43.95 billion. EW’s earnings yield of 2.7% favorably compares to the industry’s negative 2.2% yield. In the trailing four quarters, Edwards delivered an average earnings surprise of 5.7%.
Let’s delve deeper.
Upsides for EW Stock
TMTT Portfolio Holds Potential: Edwards’ TMTT portfolio remains a major source of growth as the company scales repair and replacement therapies across mitral and tricuspid disease. Second-quarter 2026 TMTT sales were $195.9 million, up 44.8% on a constant-currency basis, with global mitral and tricuspid procedure growth remaining in the double digits. PASCAL, EVOQUE and SAPIEN M3 all contributed ahead of management’s expectations. PASCAL adoption continues to increase, supported by differentiated design and clinical outcomes. Real-world data showed sustained one-year safety and effectiveness for PASCAL PRECISION in more than 4,600 U.S. degenerative mitral regurgitation patients.
Edwards also received CE Mark for SAPIEN M3 RESILIA and broadened the European indication for SAPIEN M3 and SAPIEN M3 RESILIA to patients with mitral annular calcification. ENCIRCLE registry data also showed low 30-day mortality, near elimination of regurgitation and quality-of-life improvement in this population. The company expects these layered platforms to provide durable growth beyond the current launch phase as access broadens and centers gain experience.
Image Source: Zacks Investment Research
TAVR Looks Promising: Edwards’ TAVR franchise continues to benefit from the clinical and technology investments built around the SAPIEN platform. Second-quarter 2026 TAVR sales were about $1.3 billion and increased 10.5% on a constant-currency basis. Growth rates were similar in the United States and outside the United States, while average selling prices remained stable globally. Edwards also reported modest year-over-year competitive position gains in the United States and Europe.
The evidence base continues to support broader and earlier treatment. A seven-year PARTNER 3 subanalysis reinforced SAPIEN valve performance and durability, while a five-year EARLY TAVR analysis added evidence supporting intervention earlier in the aortic-stenosis disease pathway. Updated European guidelines are also shaping clinical discussion around proactive treatment, and Japan approved the asymptomatic indication in second-quarter 2026.
The next catalyst is the PROGRESS trial, which will evaluate whether certain moderate aortic-stenosis patients may benefit from earlier TAVR treatment. Following second-quarter performance, management raised 2026 TAVR constant-currency sales growth guidance to 8-9% from 7-9%.
Strong Solvency: Edwards ended second-quarter 2026 with about $2.9 billion in cash and cash equivalents, with roughly $600 million of debt, providing flexibility for investment and repurchases. About $1.5 billion remained under its repurchase authorization.
What Ails Edwards?
Macro Concerns Weigh on Margins: Edwards’ global manufacturing and commercial footprint leaves results exposed to trade-policy changes, inflation and cross-border cost shifts. In its second-quarter 2026 filing, the company said increased U.S. tariffs and retaliatory tariffs could affect its business and that it is evaluating supply-chain, exemption and exclusion options to mitigate potential effects. The company cannot predict future tariff rates or whether mitigation will be sufficient. Current results also show sensitivity to external cost factors. Adjusted gross margin was 77.6% in second-quarter 2026, flat year over year, as lower manufacturing expenses offset foreign-exchange effects.
Foreign Exchange Remains a Margin Risk: Currency movements remain an important earnings variable because Edwards generates substantial sales and expenses outside the United States. Foreign exchange increased second-quarter 2026 reported sales by about $15 million but reduced adjusted gross margin by roughly 70 basis points versus the prior year. Management expects foreign exchange to reduce second-half sales by about $35 million if rates remain at current levels and now sees 2026 gross margin near the lower end of its 78%-79% range.
EW Stock Estimate Trend
The Zacks Consensus Estimate for Edwards’ 2026 earnings per share (EPS) has remained constant at $3.00 in the past 60 days.
The Zacks Consensus Estimate for the company’s 2026 revenues is pegged at $6.76 billion, suggesting an 11.4% improvement from the year-ago reported number.
Key Picks
Some better-ranked stocks in the broader medical space are Phibro Animal Health PAHC, IDEXX Laboratories IDXX and Globus Medical GMED.
Phibro Animal Health has an earnings yield of 9.3% compared with the industry’s 2.7%. Shares of the company have dropped 2.3% compared with the industry’s 26.8% decline over the past year. PAHC’s earnings outpaced estimates in each of the trailing four quarters, the average surprise being 18.4%.
PAHC sports a Zacks Rank #1 (Strong Buy) at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
IDEXX Laboratories, carrying a Zacks Rank #2 (Buy), has an earnings yield of 2.7% against the industry’s negative 2.2% yield. Its earnings beat estimates in each of the trailing four quarters, the average surprise being 5.7%. IDXX shares have plunged 12.7% against the industry’s 2% growth over the past year.
Globus Medical, carrying a Zacks Rank #2, has an earnings yield of 6.8% against the industry’s negative 1.7% yield. Its earnings surpassed estimates in each of the trailing four quarters, with the average surprise being 27.9%. GMED shares have rallied 26.1% compared with the industry’s 2% gain over the past year.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Edwards Lifesciences Corporation (EW): Free Stock Analysis Report
IDEXX Laboratories, Inc. (IDXX): Free Stock Analysis Report
Globus Medical, Inc. (GMED): Free Stock Analysis Report
Phibro Animal Health Corporation (PAHC): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).