

Coca-Cola Europacific Partners plc CCEP combines improving operating growth with a valuation that already sits near the top of its historical range. Faster-growing beverage categories, better productivity and healthy cash generation support the business case.
The trade-off is price. Consumer affordability remains a concern, revenue per unit case is advancing only modestly and higher cost inflation is expected in the second half of 2026. That mix favors selectivity rather than chasing growth at any valuation.
CCEP’s Growth Portfolio Strengthens the Bull Case
CCEP is broadening beyond traditional sparkling drinks into zero sugar, energy, sports and hydration. In the first half of 2026, sports volumes rose 12%, energy increased 19% and zero-sugar volumes advanced about 10%. Product launches and new pack formats can widen consumption occasions and help recruit consumers.
Energy remains a particularly active category. Monster Beverage Corporation MNST, whose brands are distributed by CCEP in several markets, reported a 21.6% increase in second-quarter 2026 net sales for its Monster Energy Drinks segment. That backdrop supports CCEP’s push into faster-growing beverage categories.
CCEP’s Profit Growth Outpaces Revenue
Comparable FX-neutral revenues increased 6.1% in the first half of 2026, while comparable operating profit rose 8.1%. Operating margin reached 13.8%, up about 30 basis points, as productivity, efficiency programs and tighter discretionary spending helped profits grow faster than revenues.
Keurig Dr Pepper Inc. KDP provides another beverage-industry example of growth supported by operating leverage. Its U.S. Refreshment Beverages net sales increased 10% in the second quarter of 2026, driven by 6.5% volume and mix growth and 3.5% net price realization.
Coca-Cola Europacific Partners Price and Consensus
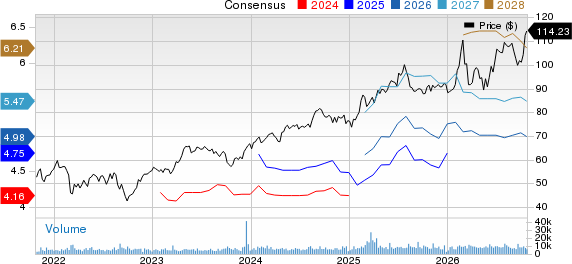
Coca-Cola Europacific Partners price-consensus-chart | Coca-Cola Europacific Partners Quote
CCEP’s Cash Flow Funds Continued Investment
Comparable free cash flow reached €435 million in the first half despite investment in coolers, production lines, technology and the new Manila facility. The company remains on track for at least €1.7 billion of comparable free cash flow for 2026.
That cash generation gives CCEP room to invest in capacity and distribution while maintaining its broader growth program. More than 80,000 coolers were added during the first half, and the Philippines facility remains scheduled to begin production in 2027, supporting future demand.
CCEP’s Premium Multiple Raises the Entry Risk
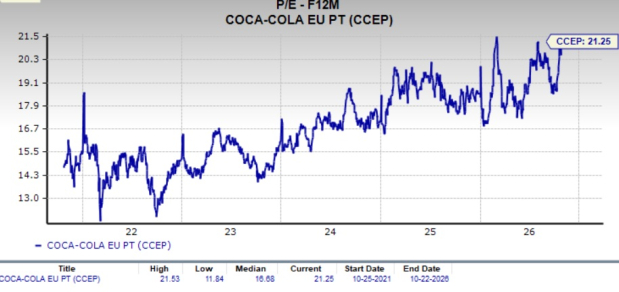
Valuation is the main counterweight to the improving operating picture. CCEP trades at 21.3X forward 12-month earnings, above the soft-drink sub-industry’s 20.1X and well above its own five-year median of 16.7X. The multiple is also close to its five-year high of 21.5X.
That premium leaves less room for execution setbacks. Revenue per unit case rose just 0.4% in the first half, while cost of sales per unit case is expected to increase about 1.5% for 2026. Affordability pressure could also limit CCEP’s ability to rely on pricing and mix to offset inflation.
Image Source: Zacks Investment Research
CCEP’s Ratings Favor Patience Over Chasing Growth
CCEP’s fundamentals are improving, but the combination of a premium valuation and near-term estimate pressure argues against treating the growth story alone as a sufficient reason to buy at current levels. The business has multiple growth levers, yet the present valuation demands continued execution.
The stock currently carries a Zacks Rank #4 (Sell). CCEP has a Growth Score of B, but its Value Score of D, Momentum Score of C and VGM Score of C are less supportive. Because Zacks Style Scores are designed to complement the Zacks Rank, the current mix favors patience over a fresh entry despite the company’s improving operating profile.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Coca-Cola Europacific Partners (CCEP): Free Stock Analysis Report
Monster Beverage Corporation (MNST): Free Stock Analysis Report
Keurig Dr Pepper, Inc (KDP): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).