

NetApp, Inc. NTAP is benefiting from improved pricing amid rising component and commodity costs, supporting its revenue growth despite a challenging cost environment. The company has adjusted product prices to offset higher input costs, which contributed to stronger-than-expected performance in the first quarter of fiscal 2027. On the last earnings call, management highlighted that pricing benefits, accelerated customer purchases and broad-based demand for AI and infrastructure modernization supported the quarter's results.
NetApp reported first-quarter revenues of $2.03 billion, up 30% year over year, including the benefit of an additional week. Excluding this impact, revenues increased 26%. Product revenues surged 51% to $987 million, reflecting robust demand across its portfolio. The company's product gross margin reached 54.6%, declining 150 basis points sequentially due to higher component costs, partially offset by improved pricing. However, product gross margin exceeded management's expectations, demonstrating its ability to capture higher prices despite cost pressures.
On the last earnings call, management stated that its pricing actions are translating into financial benefits faster than in previous cycles. Historically, price increases took two to three quarters to materialize, but greater pricing agility is now allowing NetApp to realize these benefits earlier. The company also noted that customers continue to prioritize spending on critical infrastructure despite higher prices. However, some customers are delaying less essential projects or shifting toward more cost-effective hybrid flash solutions.
NetApp expects its product gross margin performance for the remainder of fiscal 2027 to be slightly better than previously anticipated, reflecting improved confidence in recovering incremental costs. However, management does not expect pricing-related benefits to remain at the exceptional levels witnessed in the first quarter.
Supported by stronger demand and business momentum, NetApp raised its fiscal 2027 revenue guidance to $7.98-$8.23 billion. The midpoint of $8.1 billion implies 17% year-over-year growth and represents a $650 million increase from its previous forecast. For the second quarter, revenues are projected at $2.1 billion, plus or minus $75 million. Continued pricing improvements, alongside sustained AI-driven infrastructure spending, could support revenue growth despite ongoing component cost pressures.
Taking a Look at NTAP’s Competitors
Hewlett Packard Enterprise HPE is benefiting from a broader shift toward AI infrastructure, networking modernization and hybrid cloud, with Juniper expanding its addressable market and integration synergies supporting earnings growth. Record orders and backlog show demand is outpacing shipments, while Private Cloud AI, Alletra and GreenLake deepen HPE’s exposure to software, services and recurring consumption. Management has raised its fiscal 2026 and fiscal 2027 outlooks as profitability, free cash flow and deleveraging advance. For fiscal 2026, HPE raised its revenue growth outlook to 34-37% and non-GAAP earnings per share guidance to $3.75-$3.85. For fiscal 2027, management raised its revenue growth framework to 13-17% and projected non-GAAP earnings per share growth of 16-20%.
Teradata Corporation TDC is benefiting from rising recurring revenue, expanding operating leverage and a strengthened balance sheet that gives the company room to fund AI innovation and shareholder returns. The Autonomous Knowledge Platform broadens its hybrid data and AI proposition, while Teradata Factory and AI Studio target regulated, sovereign and production-scale agentic AI workloads. Customer interest and early wins support the strategic shift and stronger retention over time. For 2026, Teradata guided its non-GAAP earnings outlook to $2.65-$2.73 per share and adjusted free cash flow forecast to $330-$350 million.
NTAP Price Performance, Valuation & Estimates
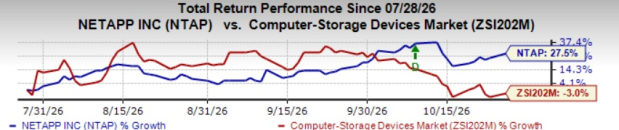
Shares of NetApp have gained 27.5% in the past three months against the Computer-Storage Devices industry’s decline of 3%.
Image Source: Zacks Investment Research
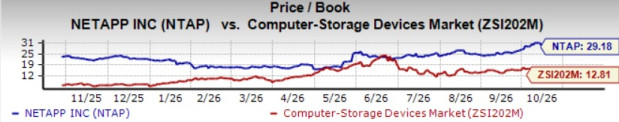
Regarding the price/book ratio, NTAP is trading at 29.18, higher than the industry’s multiple of 12.81.
Image Source: Zacks Investment Research
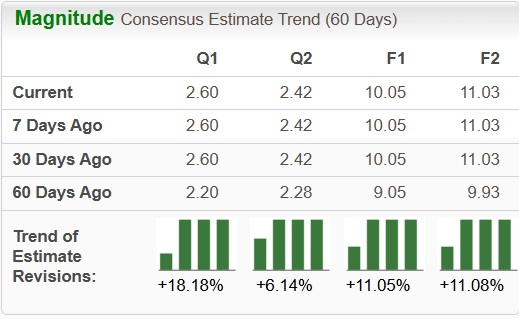
The Zacks Consensus Estimate for NTAP’s earnings for fiscal 2027 has been revised upward over the past 60 days.
Image Source: Zacks Investment Research
NTAP currently sports a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
NetApp, Inc. (NTAP): Free Stock Analysis Report
Teradata Corporation (TDC): Free Stock Analysis Report
Hewlett Packard Enterprise Company (HPE): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).