

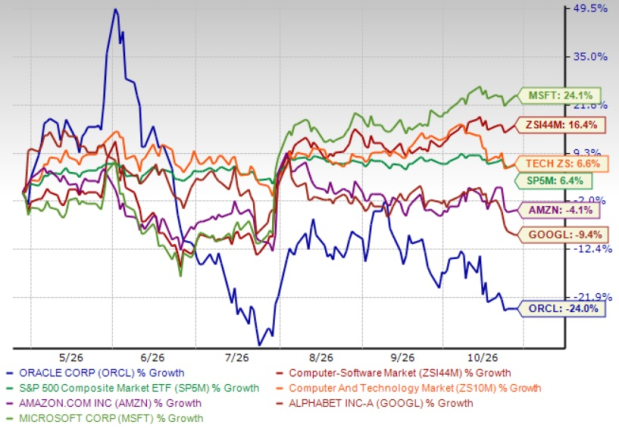
Oracle ORCL shares have plunged 24% over the past six months, as investors weighed the company’s aggressive artificial intelligence (AI) infrastructure spending against its funding needs. The stock has underperformed the Zacks Computer and Technology sector and the Zacks Computer - Software industry’s growth of 6.6% and 16.4%, respectively. The underperformance reflects capex worries and intensifying competition from Amazon AMZN, Microsoft MSFT and Alphabet GOOGL-owned Google.
However, the pullback overlooks a business with strengthening fundamentals. Cloud infrastructure growth is accelerating, contracted backlog has hit a record, and management has raised its fiscal 2027 outlook.
Oracle is also embedding agentic AI across its applications suite, opening a second growth avenue. While negative free cash flow remains a legitimate concern, here are three reasons why investors should consider buying Oracle stock right now.
ORCL’s 6-Month Price Performance
Image Source: Zacks Investment Research
Accelerating OCI Growth Backed by a Record Backlog
Oracle Cloud Infrastructure (“OCI”) is the primary growth engine. In first-quarter fiscal 2027, cloud infrastructure revenues jumped 121% year over year to $7.4 billion, marking the ninth consecutive quarter of acceleration, while total cloud revenues rose 62% to $11.6 billion. Infrastructure (CPU and GPU) revenues alone surged 151% to $6.5 billion. Total revenues climbed 30% to $19.3 billion, non-GAAP operating income rose 31% to $8.2 billion with a 42% margin, and non-GAAP earnings increased 30% to $1.92 per share. Demand visibility is exceptional, with remaining performance obligations (RPO) surging $209 billion year over year to $664 billion.
Oracle added 850 megawatts of data center capacity during the quarter and reported AI infrastructure utilization of 97.9%. GPUs up for renewal commanded an average premium of 20%, signaling strong pricing power. Most of the RPO growth was structured through customer prepayments or bring-your-own-hardware arrangements, easing capital intensity and supporting healthy contractual margins.
AI Applications and Multicloud Broaden the Growth Base
Beyond infrastructure, Oracle is monetizing AI across its database and applications portfolio. Multicloud database revenues soared 353% in the first quarter, while cloud database revenues grew 26% to $0.9 billion. Cloud applications revenues rose 10% to $4.2 billion, led by Fusion back-office applications, up 14%, and industry applications, including Oracle Health, up 12%. NetSuite, which grew just 6%, remains a soft spot, but deeper AI integration across Fusion and industry suites should improve customer retention and cross-selling over time.
Recent announcements strengthen this momentum. In September 2026, Oracle introduced Fusion Claw, a governed execution runtime powering 25 new agentic applications across finance, HR, supply chain and sales, and unveiled AI-driven oncology EHR and revenue cycle management tools for Oracle Health. In October, OCI Enterprise AI added xAI’s Grok 4.6 and Grok 4.7 models along with a Smart Model Router, while OCI Generative AI introduced sandboxes and support for importing NVIDIA’s Nemotron 3 Ultra model. At Oracle AI World, the company launched Console AI for OCI customers, enhanced its Autonomous AI Lakehouse and committed $1 billion over four years to its partner ecosystem, alongside new industry-focused NetSuite AI agents.
Raised Guidance Points to Sustained Momentum
Oracle now expects fiscal 2027 total revenues of at least $90 billion, implying 34% year-over-year growth, and non-GAAP earnings of $8.10 per share. For the second quarter, revenues are projected to grow 30-34%, with cloud revenues expected to rise 64-70% at constant currency and non-GAAP earnings per share anticipated between $1.83 and $1.91. Excluding the prior-year Ampere investment gain, second-quarter non-GAAP earnings are expected to rise 19-23% at constant currency. Management expects infrastructure revenue acceleration to continue through fiscal 2027. Spending remains the key risk, and management expects gross margins to decline as new data centers ramp. First-quarter capital expenditures reached $28 billion, pushing free cash flow to negative $5 billion despite record operating cash flow of $23 billion, up 184%.
Oracle expects fiscal 2027 capex of $90-$95 billion, with net cash capex capped at $70 billion, and sold $20 billion of common stock during the quarter, diluting shareholders. Still, Oracle closed more than $30 billion of additional AI contracts in the quarter without changing its capital-raising plans.
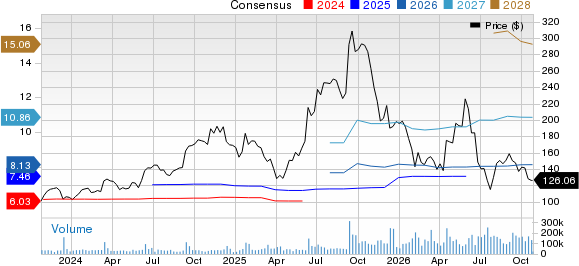
The Zacks Consensus Estimate for ORCL’s fiscal 2027 earnings is currently pegged at $8.13 per share. The estimate implies 6.55% year-over-year earnings growth. Excluding one-time fiscal 2026 investment gains, management expects 18% growth.
Oracle Corporation Price and Consensus
Oracle Corporation price-consensus-chart | Oracle Corporation Quote
ORCL’s Valuation and Competitive Landscape
Amazon, Microsoft and Google lead the cloud market and are also scaling AI capacity aggressively worldwide. Amazon Web Services recently launched Bedrock Managed Agents powered by OpenAI in preview, letting enterprises run agents within existing cloud governance controls, and added several new frontier models to Amazon Bedrock. Microsoft unveiled its Maia 300 custom inference chip in October 2026, promising about 40% more tokens per megawatt, and plans multi-gigawatt Azure Maia deployments from 2027, strengthening Microsoft’s AI cost position. Google introduced its Gemini agent at Gemini at Work 2026, alongside TPU 8i chips claiming 80% better price-performance, while Google Cloud says about 80% of its customers use its AI products. Still, Oracle’s growing multicloud database offerings across these hyperscalers effectively turn rivals into distribution channels.
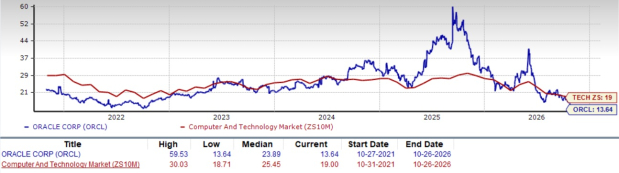
ORCL’s valuation remains relatively attractive, with the stock trading at a forward 12-month P/E ratio of 13.64X, lower than the sector average of 19X. Oracle has a Value Score of B. Accelerating OCI growth and a $664 billion backlog justify buying the stock at current valuation.
ORCL’s Valuation Chart
Image Source: Zacks Investment Research
Conclusion
Oracle’s sharply accelerating OCI growth, record $664 billion backlog, expanding agentic AI portfolio and raised fiscal 2027 guidance make a compelling near-term case despite elevated capex and negative free cash flow. With its Investor Day on Oct. 28 offering a potential catalyst, investors should consider accumulating the stock on this recent dip. ORCL currently carries a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Oracle Corporation (ORCL): Free Stock Analysis Report
Amazon.com, Inc. (AMZN): Free Stock Analysis Report
Microsoft Corporation (MSFT): Free Stock Analysis Report
Alphabet Inc. (GOOGL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).