

PayPal Holdings, Inc. PYPL reported third-quarter 2026 non-GAAP earnings per share (EPS) of $1.45, beating the Zacks Consensus Estimate of $1.31 by 10.7%. The metric increased 8% year over year. Revenues of $8.58 billion missed the consensus mark of $8.70 billion by 1.3% but increased 2% year over year.
The quarter benefited from continued strength in Venmo and Braintree, along with operating expense discipline. Total payment volume (TPV) increased 6% to $487.14 billion, or 7% on a currency-neutral basis.
PYPL's Revenue Growth Reflects Transaction Gains
Transaction revenues increased 3% year over year to $7.71 billion, supported by Braintree, Venmo and favorable foreign exchange movements. Revenues from other value-added services declined 2% to $873 million, primarily due to lower interest earned on customer balances, partially offset by higher credit revenues.
U.S. revenues rose 5% to $5 billion, while international revenues declined 2% to $3.58 billion. On a currency-neutral basis, international revenues fell 4%.
PYPL's Payment Activity Maintains Momentum
The company processed 6.80 billion payment transactions in the third quarter, up 7% year over year. Excluding payment service provider (PSP) transactions, payment transactions also increased 7% to 4.31 billion.
Transactions per active account increased 6% to 60.8 on a trailing 12-month basis. Excluding PSP, the metric rose 6% to 38.4, reflecting continued strength in Venmo engagement and improving transaction activity.
PYPL's Platform Mix Highlights Venmo Strength
Venmo TPV advanced 14% year over year to $96.81 billion and accounted for 20% of total payment volume. The business maintained mid-teens growth, supported by strong debit adoption and increasing engagement with financial services products.
Branded checkout volume increased 1% on a currency-neutral basis, marking a fourth consecutive quarter of stabilization within the 1-2% range. PSP volume grew 8% on a currency-neutral basis, supported by double-digit Braintree growth, while peer-to-peer and other consumer volume advanced 10%.
PYPL's Financial Services Expansion Gains Traction
Buy now, pay later (BNPL) monthly active accounts increased 23% year over year, while TPV grew 25%. U.S. debit monthly active accounts rose 44%, with TPV increasing more than 60%, highlighting growing adoption of financial services offerings.
Management expects financial services to contribute more than 20% of transaction margin dollars (TM$) in 2026 and register double-digit growth. PayPal is also expanding BNPL distribution through merchant partnerships, including Amazon in Germany and Austria, American Eagle, Aerie and Dick's Sporting Goods.
PYPL's Margins Benefit From Expense Discipline
TM$ increased 2% year over year to $3.95 billion. Excluding interest on customer balances, the metric rose 3% to $3.66 billion, supported by Venmo, Braintree and favorable foreign exchange movements.
Non-transaction-related expenses increased 1% to $2.34 billion. Non-GAAP operating income rose 3% to $1.61 billion, while non-GAAP operating margin expanded 16 basis points to 18.8%, reflecting transaction margin growth and operating leverage.
The company remains on track to achieve at least $1.5 billion in gross annualized cost savings over the next two to three years, including more than $700 million by the end of 2026.
PYPL's Account Base Remains Stable
Active accounts reached 440 million at quarter-end, increasing 0.6% year over year. Monthly active accounts totaled 228 million, up 0.4%, with Venmo accounting for much of the growth.
Venmo Debit monthly active accounts rose 55% year over year. Management highlighted financial services as an important contributor to higher customer engagement and average revenue per account.
PYPL's Cash Generation Supports Capital Returns
Net cash provided by operating activities declined 19% year over year to $1.59 billion. Free cash flow decreased 17% to $1.43 billion, while adjusted free cash flow fell 10% to $2.05 billion.
PayPal repurchased approximately 28 million shares for $1.5 billion during the third quarter and paid $118 million in dividends. Cash, cash equivalents and investments totaled $15.1 billion compared to total debt of $13.5 billion as of Sept. 30, 2026.
PYPL Raises Its Full-Year Outlook
For 2026, PayPal now expects non-GAAP earning per share (EPS) of approximately $5.60, up from its previous guidance of $5.38 and compared with $5.31 in 2025. The Zacks Consensus Estimate for the same is pegged at $5.39.
The company raised its TM$ outlook to approximately $15.7 billion and expects adjusted free cash flow of at least $6.5 billion. Management maintained its share repurchase target of $6 billion.
For the fourth quarter, PayPal expects non-GAAP EPS of approximately $1.43 compared with $1.23 in the year-ago period. The Zacks Consensus Estimate for the same is pegged at $1.36.
PYPL’s Zacks Rank
Currently, PayPal carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
PayPal Holdings, Inc. Price, Consensus and EPS Surprise
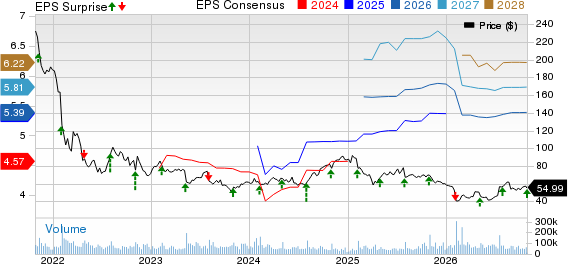
PayPal Holdings, Inc. price-consensus-eps-surprise-chart | PayPal Holdings, Inc. Quote
Upcoming Earnings Releases
We now look forward to the earnings release of other stocks in the Financial Transaction Services industry, Mastercard MA and Sezzle, Inc. SEZL. While Mastercard is scheduled to report on Oct. 29, Sezzle is slated to report on Nov. 4.
The consensus mark for Mastercard’s third-quarter 2026 EPS is pegged at $5.14, implying a 17.4% increase year over year. The Zacks Consensus Estimate for Sezzle’s third-quarter 2026 EPS is pinned at $1.28 cents, indicating an 80.3% increase year over year.
Both MA and SEZL carry a Zacks Rank #2 (Buy).
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
PayPal Holdings, Inc. (PYPL): Free Stock Analysis Report
Mastercard Incorporated (MA): Free Stock Analysis Report
Sezzle Inc. (SEZL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).