

Onto Innovation Inc. ONTO has provided an encouraging revenue outlook for the third quarter of 2026, supported by strong demand across advanced packaging and advanced nodes. The company expects third-quarter revenues between $380 million and $400 million, indicating continued sequential growth from the second quarter. On the last earnings call, management anticipated further revenue improvement for the fourth quarter, reflecting increasing customer demand and stronger business visibility.
The optimistic outlook follows a robust second-quarter performance, during which revenues reached $343 million, increasing 18% sequentially and 35% year over year. Advanced nodes revenues surged 50% sequentially to approximately $120 million, driven by broad-based strength across memory and logic applications. Memory revenues increased roughly 60% sequentially, while logic revenues grew more than 40%.
Advanced packaging also remains a significant growth driver. The company's inspection business, led by its Dragonfly product family, recorded 30% sequential growth, benefiting from strong demand for 2.5D logic and high-bandwidth memory applications. The successful launch of Dragonfly G5 has further strengthened customer demand, prompting management to raise its 2026 advanced packaging growth outlook to approximately 80% from the previously projected 50%.
Encouraged by improving demand conditions, Onto Innovation raised its second-half 2026 revenue growth outlook to at least 25% over the first half from its earlier expectation of 15%. The company's record backlog exceeded $1.1 billion, providing additional visibility into future revenues. Management indicated that 60%-70% of the backlog relates to 2026, while the remaining 30-40% extends into 2027.
Alongside revenue growth, Onto expects further profitability improvements. Gross margin is projected to expand by approximately 50 basis points in each of the third and fourth quarters. Operating margin is expected to reach 32% in the third quarter and at least 33% by year-end. At the midpoint of its third-quarter revenue guidance, the company anticipates earnings of around $2.28 per share.
With accelerating advanced packaging demand, expanding advanced nodes opportunities and improving customer visibility, Onto Innovation’s outlook supports the possibility of third-quarter revenues reaching the $400 million upper end of its guidance.
Taking a Look at ONTO’s Competitors
KLA Corporation KLAC remains positioned to outperform as AI infrastructure spending broadens demand for process control across leading-edge logic, memory and advanced packaging. Rising chip complexity, larger die sizes and tighter defect requirements should increase inspection and metrology intensity. A backlog above $12 billion and improving supply availability provide visibility into 2027, while advanced packaging offers added share gains as front-end tools move into packaging flows. Services add recurring revenue as the installed base expands. KLA’s differentiated portfolio, operating leverage and capital-return framework support long-term earnings growth. For the first quarter of fiscal 2027, KLA expects revenues of $4 billion (plus or minus $200 million).
Applied Materials AMAT benefits from AI-led investment in leading-edge foundry-logic, DRAM and advanced packaging, where rising process complexity supports demand for its equipment. New deposition and inspection technologies, value-based pricing and a growing services base strengthen its margin and cash flow outlook. Longer customer forecasts and expanded manufacturing capacity also provide visibility into future ramps. For the fourth quarter of fiscal 2026, Applied Materials expects total revenues of approximately $10.25 billion (+/-$500 million), implying 51% year-over-year growth at the midpoint.
ONTO Price Performance, Valuation and Estimates
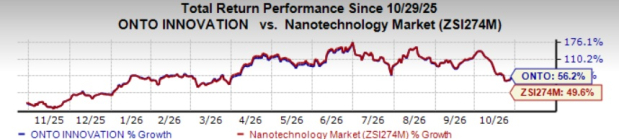
ONTO’s shares have gained 56.2% in the past year, outperforming the Zacks Nanotechnology industry’s growth of 49.6%.
Image Source: Zacks Investment Research
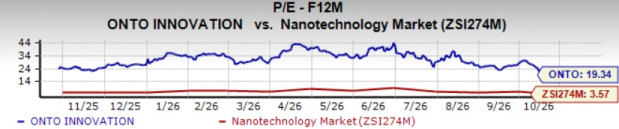
On a forward price-to-earnings basis, ONTO’s shares trade at 19.34X, higher than the industry’s 3.57X.
Image Source: Zacks Investment Research
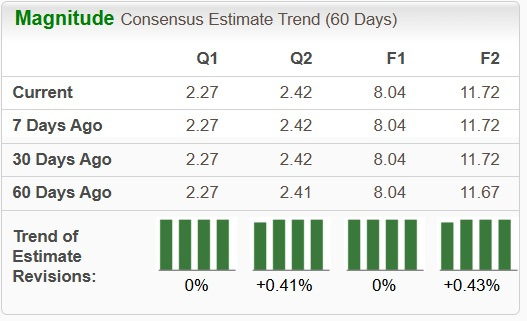
The Zacks Consensus Estimate for ONTO has remained unchanged for 2026 over the past 60 days.
Image Source: Zacks Investment Research
Onto Innovation currently sports a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Onto Innovation Inc. (ONTO): Free Stock Analysis Report
KLA Corporation (KLAC): Free Stock Analysis Report
Applied Materials, Inc. (AMAT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).