

Arm Holdings plc ARM will report its second-quarter fiscal 2027 results on Nov. 4, after the bell.
The Zacks Consensus Estimate for earnings in the to-be-reported quarter stands at 48 cents, indicating a 23% year-over-year increase. The consensus mark for revenues is pegged at $1.37 billion, indicating a 21% year-over-year increase.
The company has a strong history of earnings surprises. Earnings have surpassed the Zacks Consensus Estimate in all the trailing four quarters, with an average earnings surprise of 9.8%.
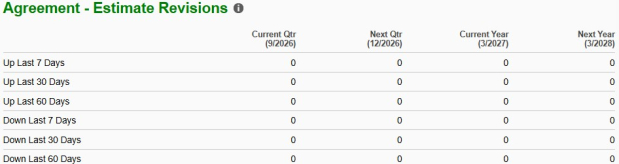
There have been no revisions for the upcoming quarter's earnings estimate in the past 30 days.
Our Model Does Not Predict a Beat
Our proven model doesn’t conclusively predict an earnings beat for ARM this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. But that’s not the case here. You can uncover the best stocks to buy or sell before they're reported with our Earnings ESP Filter.
ARM has an Earnings ESP of 0.00% and a Zacks Rank #3. You can see the complete list of today’s Zacks #1 Rank stocks here.
Royalty and License Should Drive ARM’s Top Line
We expect year-over-year improvement in the company’s top line in the to-be-reported quarter to be driven by an increase in both Royalty and License revenues. The consensus estimate for Royalty revenue is pegged at $712 million, suggesting a 14.8% year-over-year decline. The consensus estimate for License and other revenues is pegged at $661 million, indicating a 28.3% year-over-year decline.
Price Decline Still Elevated Valuation
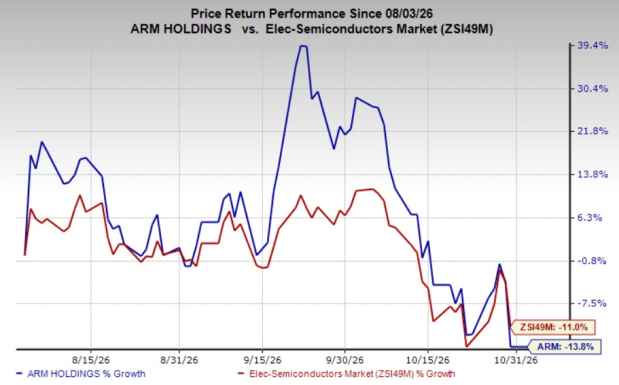
ARM stock has declined 13.8% over the past three months, making valuations high. ARM currently trades at a lofty forward 12-month price-to-earnings multiple of 75.94X, more than seven times the industry average of 10.20, suggesting the stock remains far from inexpensive.
Hold ARM Stock Ahead of Q2 Earnings
Arm Holdings’ strong position in semiconductor architecture, growing adoption of energy-efficient chip designs and increasing exposure to artificial intelligence present attractive long-term growth opportunities. Rising demand for advanced computing solutions and continued momentum in royalty and licensing businesses should support its prospects. However, ARM’s elevated valuation, despite the recent share price decline, remains a concern. Moreover, the absence of a favorable earnings beat prediction limits near-term optimism. Although ARM’s growth potential remains promising, its premium valuation leaves little room for disappointment. Given these mixed factors, existing investors should retain ARM shares, while prospective investors may await a more attractive entry point.
How Do NVIDIA and Intel Compare With ARM?
NVIDIA NVDA represents an important comparison given its leadership in AI accelerators and data-center computing. NVIDIA benefits from demand for GPUs that power AI training and inference, while Arm provides CPU architectures that support complementary computing workloads. NVIDIA's established AI ecosystem highlights the scale of infrastructure opportunities available to semiconductor companies.
Intel INTC offers another useful comparison as Arm expands into higher-performance CPUs. Intel maintains an established presence in processors for personal computers and data centers, making its competitive positioning relevant to Arm's expansion strategy. However, Intel's manufacturing-intensive operations differ substantially from Arm's traditional intellectual property licensing model, creating different profitability and capital requirements.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
ARM Holdings PLC Sponsored ADR (ARM): Free Stock Analysis Report
Intel Corporation (INTC): Free Stock Analysis Report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).