

Cummins Inc. CMI is slated to release third-quarter 2026 results on Thursday, before the opening bell. The Zacks Consensus Estimate for the to-be-reported quarter’s earnings per share and revenues is pegged at $8.38 and $9.9 billion, respectively.
The EPS estimate for the to-be-reported quarter has moved downward by 7 cents over the past 30 days. The bottom line suggests a year-over-year improvement of 50%. The Zacks Consensus Estimate for quarterly revenues suggests 19% growth from the year-ago quarter’s figure.
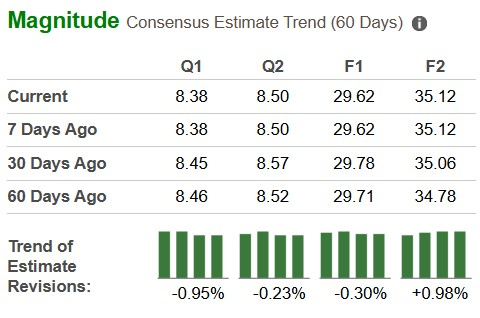
For full-year 2026, the Zacks Consensus Estimate for Cummins’ revenues is pegged at $37.74 billion, suggesting an increase of roughly 12% year over year. The consensus mark for 2026 EPS is $29.62, implying year-over-year growth of 25%. The consensus mark for 2027 EPS points to a 19% increase from the projected 2026 levels.
Notably, Cummins surpassed earnings estimates in three of the last four quarters and missed once, with the average surprise being 8.60%.
Cummins Inc. Price, Consensus and EPS Surprise
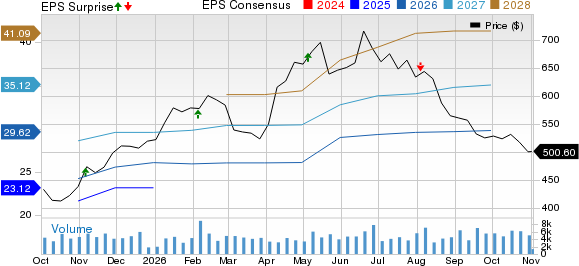
Cummins Inc. price-consensus-eps-surprise-chart | Cummins Inc. Quote
Earnings Whisper for Q3
Our proven model doesn’t conclusively predict an earnings beat for the company this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. That’s not the case here. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Cummins has an Earnings ESP of -0.82% and a Zacks Rank #3.
You can see the complete list of today’s Zacks #1 Rank stocks here.
Factors at Play
Cummins’ third-quarter results are likely to be supported by two main demand drivers. First, rising demand for backup and prime power in data centers continues to benefit the Distribution and Power Systems segments, and remains the company’s strongest tailwind. Second, management raised the midpoint of its 2026 North America truck forecasts, with heavy-duty now at 240,000-250,000 units (from 230,000-250,000) and medium-duty at 130,000-140,000 units (from 125,000-135,000). Demand is expected to stay healthy through the second half, which is likely to have buoyed the Components and Engine segments.
On the other side, Cummins continues to plan elevated capital expenditures for capacity expansion and new product programs. Capex for 2026 is expected to be in the range of $1.35-$1.45 billion, compared with $1.2 billion in 2025, with about 60% of the spending in North America. While these investments support future growth, they keep cash requirements high and may weigh on near-term free cash flow.
Segmental Predictions for Key Metrics
Here's a rundown of third-quarter revenue and EBITDA estimates for Cummins' segments.
The Zacks Consensus Estimate for Cummins' Engine segment's quarterly net sales is pegged at $3,199 million, suggesting an increase from the year-ago quarter's $2,605 million. The consensus mark for EBITDA is $449 million, implying yearly growth of 72%.
For the September-end quarter, the Zacks Consensus Estimate for the Distribution segment's net sales is $3,620 million, indicating an uptick from the year-ago quarter's $3,172 million. The same for the segment's EBITDA is $509.7 million, indicating an increase from the year-ago reported figure of $492 million.
For the quarter under discussion, the Zacks Consensus Estimate for net sales from the Power System segment is $2,314 million, suggesting an uptick from $1,996 million recorded in third-quarter 2025. The consensus mark for the segment's EBITDA is $567 million, calling for an increase from $457 million reported in the corresponding quarter of 2025.
The Zacks Consensus Estimate of $2,878 million for the Components segment's quarterly net sales calls for growth from the year-ago quarter's $2,329 million. The consensus estimate for the segment's EBITDA is $415 million, which indicates growth from $292 million recorded in third-quarter 2025.
For the Accelera Segment, the consensus estimate for EBITDA loss is pegged at $53 million, way narrower than the year-ago reported loss of $336 million. However, the Zacks Consensus Estimate for the segment’s revenues is $70.6 million, calling for a year-over-year decline of 41%.
Cummins’ Price Performance & Valuation
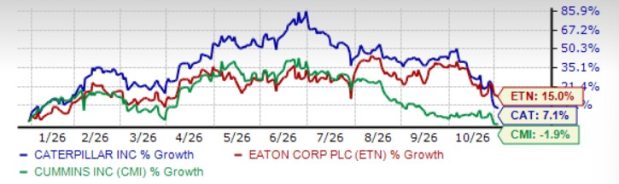
Year to date, shares of CMI have contracted 2%, underperforming peers like Caterpillar CAT and Eaton ETN. In the same timeframe, shares of Caterpillar and Eaton have gained 7% and 15%, respectively.
YTD Price Comparison
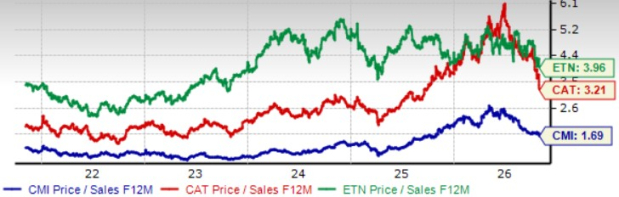
Cummins trades at 1.69 times forward 12-month sales. That is below Caterpillar’s 3.21 times and Eaton’s 3.96 times. Cummins has a Value Score of B.
CMI’s F12M P/S Vs. CAT & ETN
How to Play Cummins Ahead of Earnings
Cummins’ growth story is anchored by data center power demand. Multiyear hyperscaler agreements provide visibility into sustained backup power needs. Power Systems margins are likely to have improved, and capacity additions should help convert that demand into sales.The company is widening its data center role through natural gas generation and microgrid solutions. A firmer North American truck market has also lifted the Engine and Components outlooks, while steady dividend growth and regular buybacks add to the appeal.
That said, a few risks temper the picture. Mining demand is softening on elevated inventory, Accelera remains loss-making, and heavy capital spending keeps cash needs high. The EPA 2027 engine transition could also bring higher R&D and warranty costs as new products launch. As such, we recommend existing investors retain the stock for now rather than buy ahead of results.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Cummins Inc. (CMI): Free Stock Analysis Report
Caterpillar Inc. (CAT): Free Stock Analysis Report
Eaton Corporation, PLC (ETN): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).