

Thomson Reuters TRI reported unimpressive third-quarter 2026 results with adjusted earnings of 81 cents per share, missing the Zacks Consensus Estimate of 89 cents by 9%. However, earnings increased 14% year over year from 71 cents, supported by higher adjusted EBITDA and a lower share count.
Thomson Reuters Corp Price, Consensus and EPS Surprise
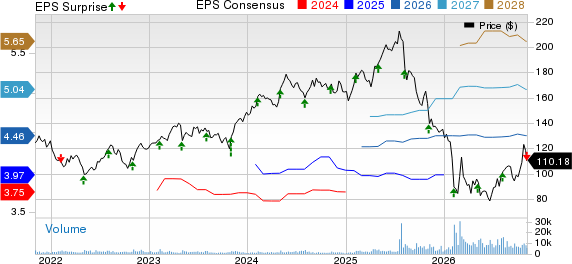
Thomson Reuters Corp price-consensus-eps-surprise-chart | Thomson Reuters Corp Quote
Revenues of $1.83 billion missed the consensus estimate of $1.91 billion by 3.9%, despite growing 10% year over year. Organic revenues increased 10%, driven by strength across the company's core businesses. Generative artificial intelligence (AI)-enabled products represented 34% of annualized contract value, up from 24% a year ago.
On Oct. 1, 2026, Thomson Reuters sold a 51% stake in its Global Print business, now operating independently as Westbridge Print. TRI’s current reported quarter and prior quarters’ figures reflect the exclusion of the impact of treating the divestiture of the Global Print business as discontinued operations.
Investors were not impressed with the earnings miss, as the stock declined 9.9% since the company released results on Nov. 3.
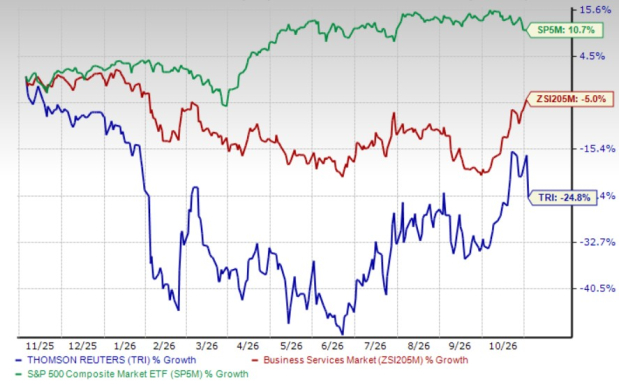
Over the past year, TRI's shares lost 24.8% compared with the industry's 5% decline. The Zacks S&P 500 composite gained 10.7% during the same period.
Image Source: Zacks Investment Research
TRI's Recurring Revenues Support Growth
Recurring revenues, accounting for 88% of total revenues, increased 9% year over year. Organic recurring revenues rose 8%, reflecting sustained demand for the company's professional information and technology solutions.
Transaction revenues climbed 27%, including 23% organic growth. The increase reflected contributions from Pagero implementations and generative AI-related content licensing. The company's three core segments, collectively known as the Big 3, contributed 88% of total revenues.
Thomson Reuters' Segment Revenues Rise
Legal Professionals revenues increased 9% year over year to $788 million, with 9% organic growth. Westlaw and CoCounsel Legal supported recurring revenue growth, while CLEAR, TRI’s online research, investigation and risk-management software platform contributed to higher transaction revenues.
Corporates revenues advanced 11% to $544 million, with organic growth of 10%. Pagero, CoCounsel Legal, CLEAR and international operations supported performance. Transaction revenues increased 32%, benefiting from e-invoicing implementation activity.
Tax, Audit & Accounting Professionals revenues increased 11% to $276 million. Organic growth was 10%, supported by CoCounsel Tax, Audit & Accounting, SafeSend, SurePrep and Latin American operations.
Reuters revenues rose 12% to $232 million, with organic growth of 12%. Results included approximately $19 million in transactional generative AI content licensing revenues. Excluding transactional AI licensing in both comparable periods, Reuters' organic growth was 7%.
TRI's Profitability Faces Cost Pressure
Adjusted EBITDA increased 10% year over year to $651 million. However, the adjusted EBITDA margin contracted 30 basis points to 35.5%, reflecting higher costs and the treatment of Global Print as discontinued operations.
The quarter included $22 million of severance expenses, reducing the adjusted EBITDA margin by approximately 120 basis points. Legal Professionals' margin declined 240 basis points to 46.6%, reflecting higher technology and other costs.
Corporates' adjusted EBITDA reached $197 million, while Tax, Audit and Accounting Professionals generated $83 million. Reuters' adjusted EBITDA increased 37% to $56 million, benefiting from higher transactional revenues.
Operating profit declined 22% to $402 million, primarily reflecting a gain from the sale of the company's remaining minority interest in Elite in the prior-year quarter and higher software amortization.
Thomson Reuters Advances AI Product Innovation
The next-generation CoCounsel Legal platform demonstrated encouraging adoption. Its active user base increased more than 60% in September from August, while users completed 2.4 times the work recorded at the previous version's peak.
The company also expanded Westlaw Brief Builder and introduced multinational legal research capabilities covering more than 100 countries. These developments strengthen its AI-enabled legal workflow offerings.
Meanwhile, the next-generation CoCounsel Tax, Audit and Accounting platform introduced agentic capabilities for producing finished professional work. Pagero expanded its geographic coverage by eight countries in 2026, supporting compliance requirements across more than 90 jurisdictions.
TRI's Cash Flow Declines, Balance Sheet Remains Strong
Net cash provided by operating activities declined 15% year over year to $599 million. Free cash flow decreased 23% to $408 million, reflecting unfavorable working capital movements, higher income tax payments and increased capital expenditures.
The company completed its $600 million share repurchase program and issued approximately $2 billion in notes during September. Net leverage stood at 1.0 times as of Sept. 30, 2026.
Thomson Reuters completed the sale of a 51% stake in Global Print to KKR-advised capital accounts for approximately $500 million in gross proceeds, retaining a 49% interest.
Thomson Reuters Updates Its 2026 Outlook
For 2026, Thomson Reuters expects total revenue growth of about 9.5% and organic revenue growth of 8.5-9%, reflecting the exclusion of Global Print. The Big 3 organic revenue growth outlook remains unchanged at 9.5-10%.
The company projects an adjusted EBITDA margin of approximately 39% and free cash flow of approximately $2.1 billion. Capital expenditures are expected to represent 8.5-9% of revenues, while net interest expense is projected at approximately $190 million.
For the fourth quarter of 2026, management expects organic revenue growth of about 8% and an adjusted EBITDA margin of approximately 42%. Reuters' slower growth and moderating transactional revenues are expected to influence the quarterly performance.
Thomson Reuters currently carries a Zacks Rank #5 (Strong Sell).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Recent Earnings Snapshots
Waste Connections, Inc. WCN reported impressive third-quarter 2026 results. WCN’s adjusted earnings of $1.58 per share outpaced the consensus mark by 4% and rose 9.7% from the year-ago quarter. WCN’s total revenues of $2.64 billion surpassed the consensus mark by 1.2% and increased 7.3% year over year.
Rollins, Inc. ROL posted unimpressive third-quarter 2026 results. ROL’s adjusted earnings of 34 cents per share missed the Zacks Consensus Estimate by 2.9% and declined 2.9% year over year. Total revenues of $1.09 billion fell short of the consensus estimate by 3.2% but increased 6.2% from the year-ago quarter.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Thomson Reuters Corp (TRI): Free Stock Analysis Report
Waste Connections, Inc. (WCN): Free Stock Analysis Report
Rollins, Inc. (ROL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).