

Western Digital Corporation WDC entered fiscal 2027 with faster revenue growth, wider margins and stronger pricing. The first-quarter beat also showed how higher-capacity hard disk drives are improving the company’s earnings profile as cloud and artificial intelligence storage demand expands.
The fiscal second-quarter outlook now tests whether that profitability can move higher again. Pricing, product mix and capacity gains remain central to the margin story, while technology execution and valuation still shape the risk-reward balance.
WDC’s Q1 Beat Shows Pricing Power Is Still Building
Fiscal first-quarter revenues rose 55% year over year to $4.38 billion. Non-GAAP earnings increased 161% to $4.64 per share and exceeded the Zacks Consensus Estimate of $4.09 by 13.5%. The sales figure also topped the consensus mark of $4.16 billion.
p>
Image Source: Zacks Investment Research
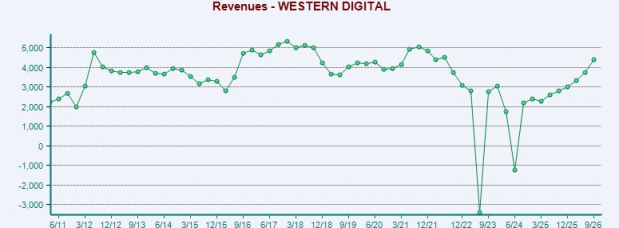
Pricing was an important contributor. Average price per terabyte increased 28% year over year, accelerating from growth in the high teens in the preceding quarter. Combined with a richer mix of higher-capacity drives, that pricing helped lift non-GAAP gross margin to 58.1%, up 1,420 basis points year over year.
Western Digital’s Q2 Guide Points to More Margin Gains
Management expects fiscal second-quarter revenues of $5.1 billion, plus or minus $100 million. The midpoint implies 69% year-over-year growth, while non-GAAP gross margin is projected at 60-61%.
That range would move profitability above the already elevated 58.1% first-quarter level. Management expects higher-capacity drives and favorable pricing to remain key supports, suggesting that the margin expansion is not relying on revenue growth alone.
WDC’s Product Transitions Could Expand Capacity
Western Digital expects its newest ePMR platform, with capacities of up to 40 terabytes, to approach 30% of nearline shipments in the fiscal second quarter and 50% in the third quarter. UltraSMR adoption is also expanding, while first-generation HAMR volume shipments remain planned for the first half of calendar 2027.
These transitions are designed to increase capacity per drive and support lower cost per terabyte over time. Seagate Technology Holdings plc STX is pursuing the same industry objective through its Mozaic HAMR platform, which has reached production with hyperscale customers. The broader move toward denser drives reinforces the importance of execution in maintaining storage economics.
Western Digital’s AI Storage Exposure Broadens Demand
Management sees inference, agentic AI and physical AI as recurring sources of data creation because these workloads generate logs, model outputs, video and system-performance data that must be retained. That demand adds to the company’s core cloud-storage opportunity.
The customer base is also widening beyond established hyperscalers toward neoclouds, frontier AI labs and enterprise environments. NetApp, Inc. NTAP is similarly investing in AI-oriented data infrastructure, including technologies aimed at scaling data access for AI workloads. The activity across storage vendors points to a broader infrastructure requirement as AI moves from model development toward sustained usage.
WDC’s Ratings Back Momentum but Flag Valuation
The operating setup remains favorable, but valuation leaves less room for execution setbacks. WDC’s forward 12-month price-to-earnings ratio of 11.5 stands above the 7.05 level for its sub-industry, while product qualification, input costs and customer concentration remain risks.
WDC currently carries a Zacks Rank #1 (Strong Buy). Its Growth Score of B and Momentum Score of B fit the favorable earnings and estimate-revision backdrop, including a 20.2% increase in the current-fiscal-year earnings estimate over the past four weeks. The Value Score of D and VGM Score of C temper that picture, indicating that investors seeking stronger value characteristics may see less support despite the company’s improving operating momentum. You can see the complete list of today’s Zacks #1 Rank stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Western Digital Corporation (WDC): Free Stock Analysis Report
NetApp, Inc. (NTAP): Free Stock Analysis Report
Seagate Technology Holdings PLC (STX): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).