

TransMedics Group, Inc. TMDX is well-poised for growth in the coming quarters, courtesy of its strength in Organ Care System (OCS) technology. The optimism, led by strength in OCS technology, is expected to contribute further. However, concerns due to gross margin pressure persist.
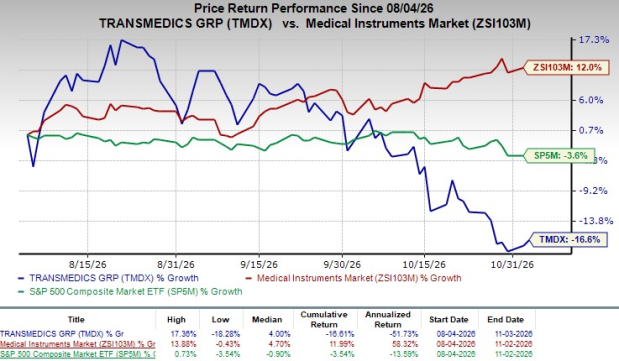
This Zacks Rank #3 (Hold) company has lost 16.6% in the last three months against 12% growth in the industry. The S&P 500 has witnessed 3.6% decline in the said time frame.
The renowned organ transplant therapy provider has a market capitalization of $2.3 billion. TransMedics’ earnings yield of 1.96% compares favorably with the industry’s negative 2.3%. The company’s earnings surpassed the Zacks Consensus Estimate in two of the trailing four quarters, missed twice, with the average surprise being 13.45%.
Image Source: Zacks Investment Research
Factors Favoring TMDX’s Growth
Strength in OCS Technology Driving Adoption: TransMedics’ OCS revolutionizes organ transplantation by replacing passive cold storage with a dynamic, physiologic approach that perfuses donor organs with warm, oxygenated, nutrient-rich blood. This innovation minimizes ischemic injury, allows real-time organ assessment and significantly increases the viability of organs, especially hearts and lungs, donated after circulatory death, that would otherwise go unused.
As the only FDA-approved, portable platform offering warm perfusion for heart, lung and liver transplants, the OCS standardizes care, reduces post-transplant complications and sets a new clinical benchmark in organ preservation. This positions TransMedics as a leader in the multi-billion-dollar transplant market with limited competition.
Robust Pipeline Supporting Growth: TransMedics continues to advance its next-generation Gen 3.0 OCS platform for heart, lung and liver, incorporating redesigned hardware, software and automation to improve usability, reliability and operating efficiency. The company is also pursuing ENHANCE Part B and DENOVO studies to expand its addressable heart and lung transplant populations, potentially unlocking 2,000-5,000 additional U.S. cases annually. Meanwhile, OCS Kidney development is progressing toward clinical testing in 2027, targeting a significant opportunity to improve utilization of recovered donor kidneys.
International expansion, supported by investments in European aviation infrastructure and plans to establish transplant logistics hubs, is another key growth driver. These initiatives could support TransMedics' longer-term goal of exceeding 10,000 annual transplants, although clinical timelines, regulatory approvals and execution remain key factors to watch.
Mixed Q2 Results: TransMedics delivered mixed second-quarter 2026 results, with revenues beating expectations but earnings missing the mark. Record revenues were driven by higher OCS utilization, strong liver and heart transplant volumes and accelerating logistics services. However, adjusted earnings declined sharply year over year as the company increased investments in clinical programs, product development and growth infrastructure.
Positively, growth remained balanced across product and service revenues, gross margin improved sequentially and logistics profitability strengthened. The company also covered 86% of NOP air transport missions using its owned fleet, up from 82% in the first quarter, reflecting improving operating efficiency.
A Factor That Can Offset TMDX’s Gains
Gross Margin Under Pressure: TransMedics is prioritizing revenue growth over near-term profitability, with the impact becoming more evident in second-quarter 2026. Gross margin declined 180 basis points year over year to 59.6%, pressured by a higher mix of lower-margin services and temporary product costs. Management expects margins to remain around 59% over the next two to three years as it continues investing internationally.
Adjusted R&D nearly doubled to $31.6 million, while adjusted operating margin contracted 960 basis points to 13.6%. Consequently, management lowered its 2026 adjusted operating-margin outlook to 12.5%-14% from approximately 16%, primarily reflecting higher OCS Kidney investments. The PAD Aviation acquisition is expected to add further near-term margin pressure, suggesting earnings growth could continue to trail revenue growth during the investment cycle.
Estimate Trend
TransMedics is witnessing a stable earnings estimate revision trend for 2026. In the past 30 days, the Zacks Consensus Estimate for its earnings has remained stable at $1.31 per share.
The Zacks Consensus Estimate for the company’s third-quarter 2026 revenues is pegged at $181.8 million, indicating a 26.4% improvement from the year-ago quarter’s reported number.
Key Picks
Some better-ranked stocks from the broader medical space are OPKO Health OPK, Globus Medical GMED and Merit Medical Systems MMSI.
OPKO Health, currently flaunting a Zacks Rank #1 (Strong Buy), reported a second-quarter 2026 adjusted loss of 1 cent per share, which surpassed the Zacks Consensus Estimate by 87.5%. Revenues of $163.6 million beat the Zacks Consensus Estimate by 24.7%. You can see the complete list of today’s Zacks #1 Rank stocks here.
OPK has an estimated earnings growth rate of 23.3% for 2026. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 95.1%.
Globus Medical, currently carrying a Zacks Rank #2 (Buy), reported a second-quarter 2026 adjusted earnings per share (EPS) of $1.34, which surpassed the Zacks Consensus Estimate by 19.6%. Revenues of $789.6 million beat the Zacks Consensus Estimate by 0.4%.
GMED has an estimated long-term earnings growth rate of 12.4%. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 27.9%.
Merit Medical Systems, carrying a Zacks Rank #2 at present, reported second-quarter 2026 adjusted EPS of $1.19, which beat the Zacks Consensus Estimate by 23.9%. Revenues of $418.8 million surpassed the Zacks Consensus Estimate by 3.5%.
MMSI has an estimated long-term earnings growth rate of 10.4%. Merit Medical Systems’ earnings surpassed estimates in the trailing four quarters, with the average surprise being 14.1%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
TransMedics Group, Inc. (TMDX): Free Stock Analysis Report
Merit Medical Systems, Inc. (MMSI): Free Stock Analysis Report
OPKO Health, Inc. (OPK): Free Stock Analysis Report
Globus Medical, Inc. (GMED): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).