

Solaris Energy Infrastructure, Inc. SEI emphasized expanding long-term power contracts, rising demand for dedicated generation and stronger earnings visibility during its third-quarter 2026 earnings call. Management also addressed regulatory uncertainty surrounding data center development.
The company raised near-term guidance following a record quarter, with executives highlighting equipment flexibility, growing services capabilities and opportunities beyond its contracted power portfolio.
In the third quarter of 2026, Solaris reported revenues of $341.1 million, up from the Zacks Consensus Estimate of $244.6 million. The company reported adjusted earnings of 45 cents per share, also exceeding the Zacks Consensus Estimate of 22 cents.
Solaris Energy Infrastructure, Inc. Price, Consensus and EPS Surprise
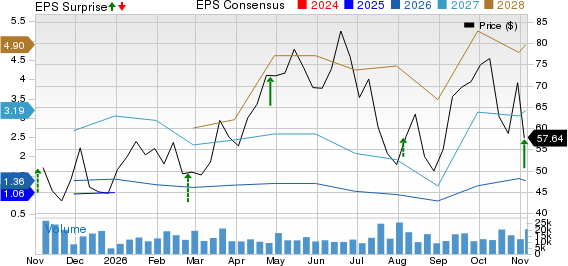
Solaris Energy Infrastructure, Inc. price-consensus-eps-surprise-chart | Solaris Energy Infrastructure, Inc. Quote
Solaris Expands Long-Term Power Commitments
Co-CEO Amanda Brock highlighted a new 15-year agreement covering approximately 900 megawatts (MW) of generation, balance-of-plant equipment and maintenance services. The contract includes an option for another 15 years.
The agreement brings contracted generation capacity to 3.2 gigawatts (GW), with a weighted average contract duration of approximately 11 years. Brock emphasized that equipment can serve multiple geographic locations.
President Kyle Ramachandran said the company expects high-teens project-level returns on capital across more than 3 GW of projects underway. The latest contract should begin energizing in the first half of 2027.
SEI Raises Guidance as Earnings Visibility Improves
CFO Stephan Tompsett raised fourth-quarter 2026 adjusted EBITDA guidance to $165-$185 million from $145-$180 million. First-quarter 2027 expectations increased to $220-$260 million from $200-$240 million.
Contracted revenue backlog exceeds $16 billion. Management expects annual run-rate adjusted EBITDA exceeding $1.6 billion once contracted projects and additional generation equipment are deployed. Third-quarter adjusted EBITDA reached $136 million, up 26% sequentially.
Solaris Builds a Broader Services Platform
Ramachandran said the Omega and GESA acquisitions expanded Solaris' engineering, construction, equipment refurbishment and maintenance capabilities. Both businesses performed better than management initially anticipated.
Power Solutions revenues increased 79% sequentially to $284 million, supported by higher owned-generation capacity and services activity. Segment adjusted EBITDA rose 32% to $127 million.
During the analyst discussion, Barclays questioned the durability of services earnings. Chairman and Co-CEO William Zartler acknowledged variability in construction activity but identified longer-term maintenance opportunities as generation equipment ages.
SEI Addresses Permitting and Contract Risks
Regulatory uncertainty emerged prominently during questions from Barclays, Stifel and Citigroup analysts, particularly regarding potential restrictions on data center development.
Zartler emphasized that Solaris' generation equipment can move between locations. Brock added that customers maintain geographically diverse development options, reducing dependence on individual project sites.
Responding to Stifel, Brock clarified that termination-for-convenience provisions generally require payments equivalent to 50% of undiscounted future revenues. Solaris also retains ownership of the equipment, providing contractual protection.
Solaris Targets Additional Generation Capacity
Ramachandran said Solaris acquired approximately 1 GW of additional generation equipment over the preceding 12 months, including 200 MW secured recently for deployment beginning in 2027.
Approximately 300 MW remains unallocated, with deployment anticipated in 2029. During questions from Wolfe Research, Zartler described increasingly coordinated capacity planning with customers over multiyear periods.
Management also discussed potential expansion beyond traditional generation technologies. Zartler identified opportunities to integrate different power sources and eventually connect dedicated generation infrastructure with broader electricity grids.
SEI Strengthens Financing for Expansion
Tompsett highlighted approximately $1.5 billion in additional financing secured during October, including $1.25 billion in senior unsecured notes and increased bank commitments.
The company's revolving credit facility now totals $850 million and remains undrawn. Management stated that announced projects and equipment commitments are fully funded.
Quarterly capital expenditures totaled approximately $547 million. Expected investment through 2029 increased approximately $600 million, reflecting additional generation equipment and supporting infrastructure.
Solaris Maintains Its Execution Focus
Management's overarching message centered on converting contracted capacity into operating infrastructure while expanding services that support deployment and reliability.
Executives expressed confidence in long-term power demand while acknowledging permitting challenges and less predictable services revenues. Near-term priorities remain project execution, capital discipline and operational expansion.
What SEI's Zacks Rank and Style Scores Indicate
SEI sports a Zacks Rank #1 (Strong Buy), indicating favorable earnings estimate revision trends and stronger near-term performance potential under the Zacks methodology. Its Growth Score and Momentum Score of A reinforce those characteristics. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
However, the Value Score of F indicates weak relative valuation characteristics, while the VGM Score of C reflects a less favorable combined profile. Investors should also recognize that the Zacks Rank can change as analysts revise earnings estimates following the reported results.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Solaris Energy Infrastructure, Inc. (SEI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).