

Microsoft MSFT kicked off fiscal 2027 with Azure in the driver’s seat, raising the question of whether investors should buy, sell or hold the stock now. First-quarter fiscal 2027 revenues rose 19% year over year to $92.3 billion, while Microsoft Cloud revenues climbed 30% to $63.9 billion. Azure generated $33.2 billion in revenues, which increased 48% year over year and came ahead of management’s expectations. However, surging capital spending, margin pressure and softness in consumer businesses suggest a balanced approach in the near term.
The Zacks Consensus Estimate for MSFT’s fiscal 2027 earnings is pegged at $19.87 per share. The estimate indicates 10.7% year-over-year growth.
Microsoft Corporation Price and Consensus
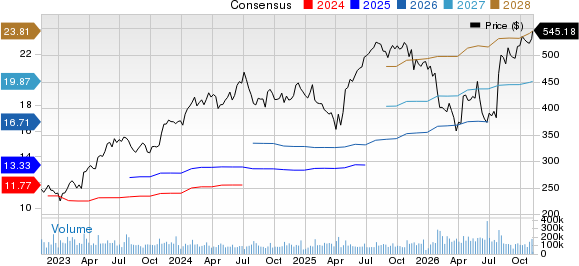
Microsoft Corporation price-consensus-chart | Microsoft Corporation Quote
Azure and AI Strengthen Microsoft’s Growth Engine
Microsoft’s fundamental appeal rests on its ability to monetize AI across infrastructure, platforms and applications. Foundry revenues more than tripled year over year, aided by GPU fleet efficiency gains and higher revenue per token. Daily Copilot usage rose nearly 50% sequentially and more than fivefold year over year, while customers consuming Copilot credits through usage-based billing grew more than 75%. Average revenue per user is being lifted by premium offerings, including Microsoft 365 Copilot, E5 and E7.
Infrastructure execution is also improving. Microsoft added 24 new data centers across five continents during the quarter, cut dock-to-live times for new GB300 systems in its largest regions by about 20% sequentially and docked its first Rubin GPUs. The company completed pre-training of MAI Base 2, its next first-party base model.
Still, there are pressure points. Microsoft Cloud gross margin declined to 66% as the mix shifted toward Azure, and commercial bookings fell 12% against a tough prior-year comparison. The Devices and Consumer segment revenues declined 3% to $15.5 billion, as Windows OEM and devices revenues dropped 22% and Xbox content and services revenues slipped 2%.
Recent Azure and AI Developments
Microsoft’s Azure blog highlights steady product momentum in October and November 2026. In October, Microsoft detailed the architecture of its Maia 300 chip, positioned as a single platform for cloud-scale agentic inference, and introduced the Microsoft Copilot harness in Foundry Agent Service in public preview. The company expanded its sovereign cloud and sovereign AI offerings, giving customers greater control over where workloads run. In November, MSFT showcased Azure Cobalt 200 virtual machines accelerating electronic design automation workloads and brought fal’s multimodal models to Microsoft Foundry. Microsoft Ignite, scheduled for Nov. 17-20, 2026, is likely to bring additional agent and infrastructure announcements.
Q2 Outlook Reflects Momentum, Rising Capex
For the second quarter of fiscal 2027, Microsoft expects revenues between $96 billion and $97.1 billion, indicating 18-19% year-over-year growth. Azure revenue growth is projected to accelerate to 49-50% in constant currency, supported by CPU and GPU fleet efficiencies. Second-quarter operating expense guidance includes the estimated cost of an employee voluntary exit offer.
The flip side is spending intensity. First-quarter capital expenditures, including finance leases, were $45.2 billion, with roughly three-fourths allocated to short-lived assets, mainly CPUs and GPUs. Microsoft expects second-quarter capex to exceed $50 billion, bringing projected calendar-year 2026 spending to approximately $170 billion, as demand continues to exceed available capacity. Management expects free cash flow to remain positive throughout fiscal 2027, while the company returned $10.2 billion to shareholders through dividends and buybacks in the first quarter.
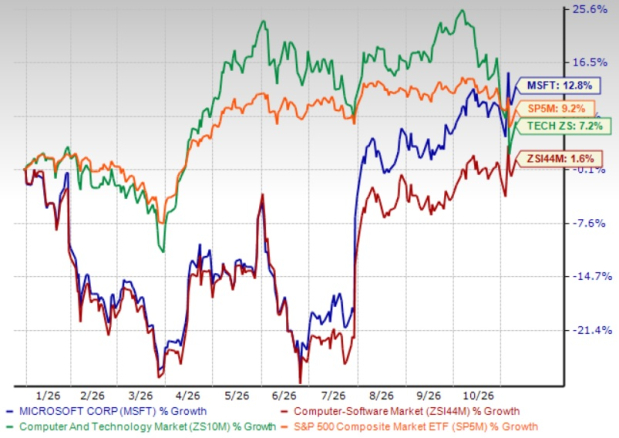
MSFT shares have gained 12.8% in the year-to-date (YTD) period compared with the Zacks Computer – Software industry’s 1.6% return. The Zacks Computer and Technology sector has appreciated 7.2% in the same time frame. The stock’s underperformance relative to the broader sector may reflect investor caution over the payback period for heavy AI infrastructure spending.
MSFT’s YTD Price Performance
Image Source: Zacks Investment Research
Valuation and Competition
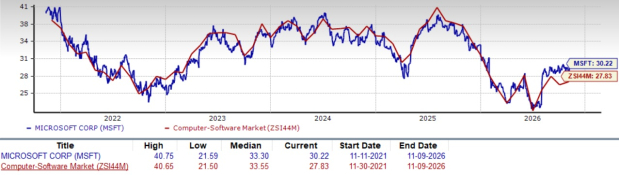
From a valuation standpoint, MSFT stock appears overvalued, trading at a trailing 12-month price/earnings ratio of 30.22X, higher than the industry’s 27.83X. MSFT has a Value Score of C. The premium faces intensifying competition from cloud and AI rivals. Amazon’s AMZN AWS revenues grew 39% to $46 billion in the third quarter of 2026, and Amazon projects AWS growth exceeding 40% in both 2027 and 2028. Investors can hold Amazon despite its premium valuation, as accelerating AWS growth and expanding operating income support long-term earnings. Alphabet’s GOOGL Google Cloud revenues jumped 103% to $30.7 billion in the third quarter, with Alphabet disclosing a cloud backlog of $561 billion, making Alphabet a fast-rising challenger. Nvidia NVDA posted data center revenues of $89 billion, up 117%, in the second quarter of fiscal 2027. While Nvidia supplies Vera Rubin systems to Azure, Nvidia’s expanding deals with rival clouds intensify the race for scarce AI capacity.
MSFT’s Valuation Appears Steep
Image Source: Zacks Investment Research
Conclusion
Accelerating Azure growth and expanding AI adoption support the long-term case, but elevated capex, margin pressure and a premium valuation suggest existing investors hold while new investors await a better entry point.
Microsoft currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Microsoft Corporation (MSFT): Free Stock Analysis Report
Amazon.com, Inc. (AMZN): Free Stock Analysis Report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
Alphabet Inc. (GOOGL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).