

Brown & Brown, Inc. BRO appears reasonably positioned to sustain organic revenue growth despite moderating insurance pricing, although a meaningful acceleration may remain challenging. Its diversified distribution network, specialty business portfolio, new business generation and cross-selling opportunities provide a foundation for growth. However, softer pricing across certain commercial insurance lines could limit commission expansion, increasing the importance of customer retention and exposure growth.
In the third quarter of 2026, BRO's organic revenues increased 1.2% year over year to $1.46 billion. Including contingent commissions, organic revenue growth was 1.5%. The Retail segment delivered 2.6% organic revenue growth to $854 million, supported by net new business, exposure-unit expansion and employee benefits and bond businesses. Employee benefits pricing remained favorable, with rates increasing 9-11%, while casualty rates rose 2-5%. These trends could continue to support organic growth.
However, Specialty Distribution organic revenues declined 0.8% to $610 million, reflecting softer wholesale market conditions and declining catastrophe and difference-in-conditions property rates. Weakness in standard property pricing could continue to constrain commission growth. Additionally, the company's adjusted EBITDAC margin contracted 200 basis points to 34.6%, highlighting potential operating margin pressures.
BRO's expanded distribution capabilities following the Accession acquisition offer opportunities to cross-sell products, deepen customer relationships and improve market penetration. Its increased Accession synergy target of $175 million by 2028 could also support profitability.
Overall, BRO has growth opportunities through new business, exposure expansion and acquisition synergies. However, sustained improvement across segments will be necessary to offset moderating pricing and wholesale market weakness. Thus, maintaining organic growth appears achievable, but accelerating it meaningfully in the near term could prove challenging.
What About Its Peers?
Arthur J. Gallagher & Co. AJG appears better positioned to sustain organic revenue growth despite moderating insurance pricing. In the third quarter of 2026, its combined Brokerage and Risk Management segments delivered 5% organic revenue growth, supported by strong client retention, new business generation and expanding client exposures. Organic supplemental revenues increased 14%, while base commissions and fees grew 4%. Its diversified business mix, cross-selling opportunities and acquisition strategy should support growth. However, softer commercial insurance pricing could constrain commission expansion, making volume growth and client retention increasingly important.
Willis Towers Watson WTW appears well positioned to sustain organic revenue growth despite moderating insurance pricing. In the third quarter of 2026, organic revenues increased 4%, supported by 5% growth in Risk & Broking and 4% growth in Health, Wealth & Career. Strong new business activity, client renewals, specialty insurance demand and technology sales supported performance. Its diversified consulting and brokerage businesses, alongside investments in AI and technology, should provide additional growth opportunities. However, softer commercial insurance pricing and competitive market conditions could constrain brokerage revenue expansion.
BRO’s Price Performance
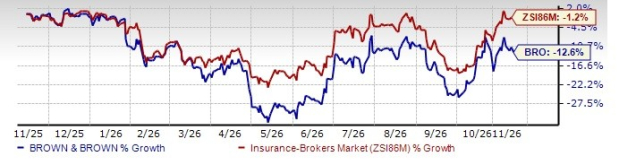
BRO shares have lost 12.6% over the past year compared with the industry’s decline of 1.2%.
Image Source: Zacks Investment Research
BRO’s Undervaluation
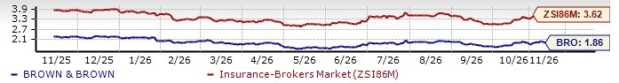
The stock is undervalued compared with its industry. It is currently trading at a price-to-book value multiple of 1.86, lower than the industry average of 3.62.
Image Source: Zacks Investment Research
Estimate Movement for BRO
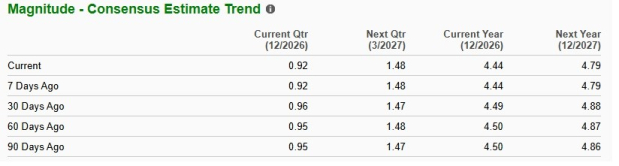
The Zacks Consensus Estimate for BRO’s fourth-quarter 2026 earnings has moved down 4.2% in the past 30 days. The same for the full-year 2026 and 2027 earnings per share has moved down 1.1% and 1.8%, respectively, in the past 30 days.
Image Source: Zacks Investment Research
The consensus estimate for BRO’s 2026 and 2027 EPS and revenues indicates a year-over-year increase.
BRO stock currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Brown & Brown, Inc. (BRO): Free Stock Analysis Report
Arthur J. Gallagher & Co. (AJG): Free Stock Analysis Report
Willis Towers Watson Public Limited Company (WTW): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).