

Shares of healthcare giants UnitedHealth Group UNH) and Humana HUM) retreated roughly 5% and 4% on Tuesday, respectively, amid renewed regulatory scrutiny.
The pullback interrupted their recent rallies as investors have increasingly gravitated toward defensive healthcare stocks during the broader technology selloff.
However, renewed regulatory concerns have emerged following proposed Medicare Advantage regulations that could recover approximately $9 billion annually in improper payments across the industry.
That said, with both companies recently beating Q3 expectations and benefiting from upward earnings estimate revisions, could the selloff present an intriguing buying opportunity for long-term investors?
UnitedHealth & Humana's Improving Earnings Outlooks
UnitedHealth most recently delivered Q3 adjusted earnings of $4.69 per share, beating the Zacks Consensus Estimate by nearly 14%. Quarterly revenue totaled $112.7 billion, supported by its UnitedHealthcare insurance and Optum healthcare services businesses.
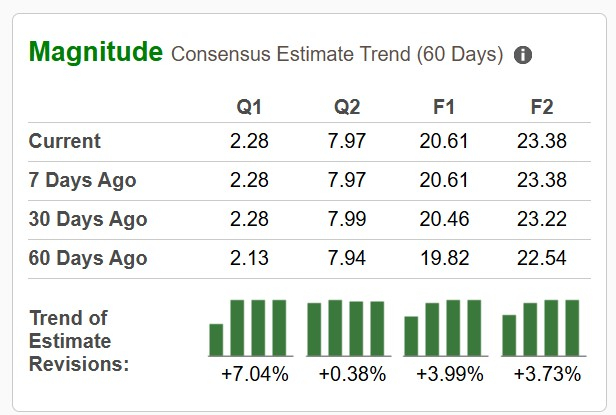
More encouragingly, UnitedHealth raised its full-year adjusted EPS guidance to at least $20.50, with improving medical cost management and operating efficiencies supporting its profitability outlook. Analysts have responded by raising their earnings estimates, with the Zacks Consensus for UNH’s FY26 and FY27 EPS up nearly 4% in the last 60 days, reinforcing expectations for a continued recovery.
Annual earnings are now expected to surge 26% this year and are projected to increase another 13% in FY27 to $23.38 per share.
Image Source: Zacks Investment Research
Humana also exceeded Q3 expectations, reporting an adjusted loss of $0.70 per share compared with the Zacks Consensus Estimate that called for a loss of $1.03. Although the results were better than anticipated, the loss reflected elevated medical costs and seasonal Medicare Advantage pressures.
Third-quarter revenue increased 25% YoY to $41 billion, aided by Medicare Advantage membership growth and expansion of its CenterWell primary care operations, pharmacy, and home health services.
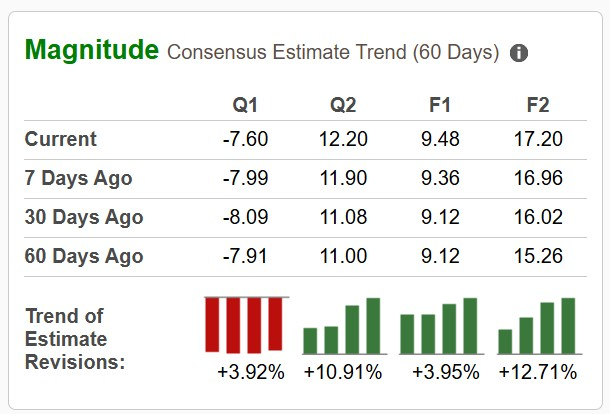
Humana subsequently raised its full-year adjusted EPS outlook to at least $9.50 from $9.00, with positive earnings estimate revisions underscoring improving profitability expectations despite ongoing medical cost and regulatory headwinds.
In the last two months, FY26 and FY27 EPS estimates have risen nearly 4% and 13%, respectively. Humana’s EPS is projected to contract from $17.14 last year, although FY27 earnings are projected to rebound 81% to $17.20 per share.
Image Source: Zacks Investment Research
Recent Performance & Valuation Comparison
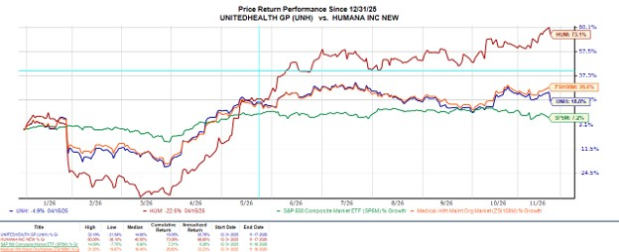
Humana has significantly outperformed UnitedHealth in 2026, with HUM stock still up over 70% year-to-date despite Tuesday's selloff, compared with gains of 18% for UNH.
Image Source: Zacks Investment Research
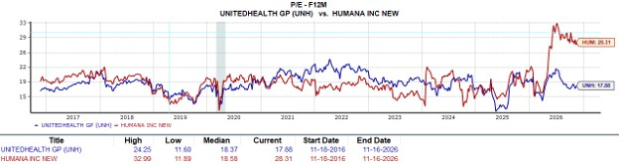
However, UnitedHealth offers a more attractive valuation, trading at 17X forward earnings compared with 28X for Humana.
Appealing to value-oriented investors, UNH trades roughly on par with their Zacks Medical-HMOs Industry average and offers a slight discount to the benchmark S&P 500’s forward earnings multiple.
Image Source: Zacks Investment Research
UNH & HUM Dividend Comparison
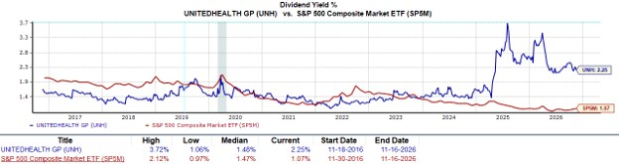
UnitedHealth also has a more generous dividend, paying $2.32 per share quarterly for an annualized yield over 2%. Humana's quarterly payout of $0.89 translates to a yield of roughly 1%, making UNH the more appealing choice for income-focused investors as well, despite HUM’s stronger performance.
Image Source: Zacks Investment Research
Bottom Line: Buy the Dip in UNH or HUM?
Despite renewed regulatory scrutiny, UnitedHealth and Humana's improving operating outlooks and positive earnings estimate revisions suggest Tuesday's selloff could present a buying opportunity for patient, long-term investors.
Humana currently sports a Zacks Rank #1 (Strong Buy), reflecting the sharp increase in earnings revisions and its recovery prospects, while UnitedHealth carries a Zacks Rank #2 (Buy), supported by its increased profitability, more reasonable valuation, and higher dividend yield.
Although tighter Medicare Advantage oversight and elevated medical costs remain risks, both healthcare giants appear worth considering on the dip, with UNH offering a more balanced value and income proposition and HUM providing stronger recent momentum.
Still, monitoring earnings estimate revisions will be crucial, as increased regulatory scrutiny could pressure future profitability.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
UnitedHealth Group Incorporated (UNH): Free Stock Analysis Report
Humana Inc. (HUM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).